
Military Wearable Medical Device Market Report Scope & Overview:
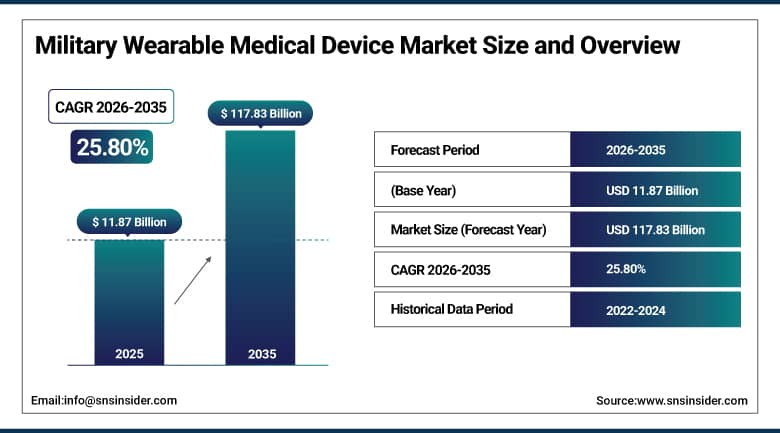
The Military Wearable Medical Device Market was valued at USD 11.87 Billion in 2025 and is expected to reach USD 117.83 Billion by 2035, growing at a CAGR of 25.80% from 2026-2035.
The Military Wearable Medical Device Market is expanding as armed forces use body-worn sensors to track heart rate, core temperature, hydration, sleep and fatigue in soldiers, sailors and aircrew. Chest straps, patches, smart rings, wristbands and sensor-embedded garments stream physiological data to medics and commanders in training and in the field. Early warning of heat illness, exhaustion and injury can protect lives and keep units combat ready. Defense health agencies are testing commercial devices and funding ruggedized, secure designs. Artificial intelligence is turning raw signals into alerts that leaders can act on.
⮞In May 2026, the Defense Health Agency reported 518 heat stroke cases among U.S. active-component service members in 2025, a rate of 39.4 per 100,000 and an increase of 6.9% over the prior year. Rising heat injury counts strengthen the case for continuous physiological monitoring.
To Get More Information On Military Wearable Medical Device Market - Request Free Sample Report
Military Wearable Medical Device Market Trends:
-
Commercial smart rings and wristbands adopted for fatigue and readiness monitoring
-
Artificial intelligence models that predict heat stroke before collapse
-
Smart textiles and sensor patches built into uniforms and body armor
-
Secure, low-power data links that work without cellular coverage
-
Medic dashboards that combine vital signs from whole squads
U.S. Military Wearable Medical Device Market Outlook:
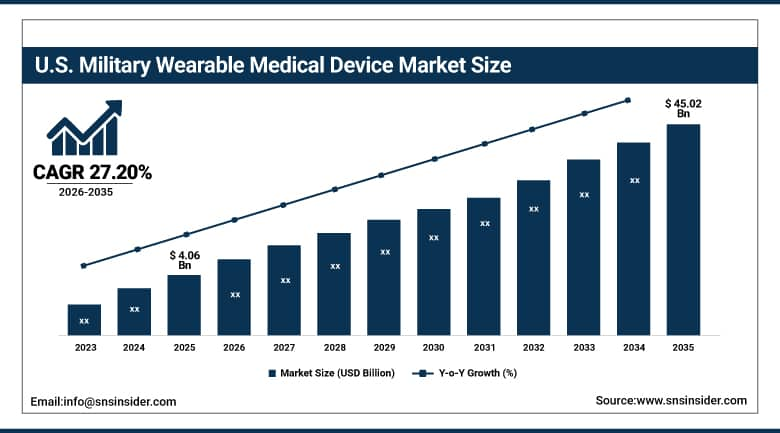
The U.S. Military Wearable Medical Device Market was valued at USD 4.06 Billion in 2025 and is expected to reach USD 45.02 Billion by 2035, growing at a CAGR of 27.20% from 2026-2035.
The U.S. Military Wearable Medical Device Market is the largest national market, driven by the Department of Defense's focus on readiness, heat injury prevention and battlefield casualty care. The Army, Navy and Air Force are all running pilots with commercial and purpose-built sensors. Research laboratories test devices for accuracy and cybersecurity before fielding. A strong base of wearable technology companies supplies the programs. Funding for human performance research supports steady development.
⮞In July 2026, the U.S. Army Heat Center reported that its HIPS wearable system detects heatstroke up to 12 minutes sooner than current methods. Earlier detection gives medics a larger window to start cooling treatment.
Military Wearable Medical Device Market Segment Analysis:
-
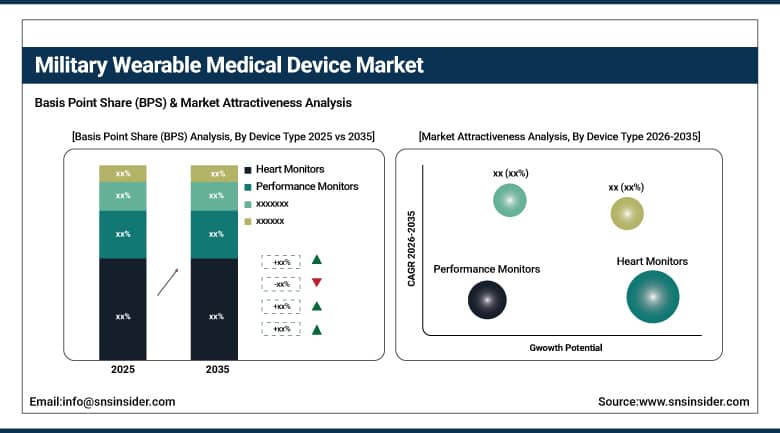
By Device Type, the Heart Monitors segment dominated the Military Wearable Medical Device Market with approximately 56.90% share in 2025, while the Performance Monitors segment is the fastest growing with a CAGR of approximately 27.40%.
-
By Wearable Form, the Bodywear segment dominated the Military Wearable Medical Device Market with approximately 40.85% share in 2025, while the Wristwear segment is the fastest growing with a CAGR of approximately 27.00%.
-
By End User, the Army segment dominated the Military Wearable Medical Device Market with approximately 57.62% share in 2025 and is also the fastest growing with a CAGR of approximately 26.90%.
-
By Connectivity, the Bluetooth and Short-Range segment dominated the Military Wearable Medical Device Market with approximately 51.34% share in 2025, while the Cellular and Satellite segment is the fastest growing with a CAGR of approximately 28.10%.
By Device Type, Heart Monitors Dominate the Military Wearable Medical Device Market and Performance Monitors Grow Fastest
Heart monitors lead because heart rate and rhythm are the most established indicators of exertion, stress and cardiac risk. Electrocardiogram straps, patches and optical sensors are mature, validated and easy to issue in large numbers. Medics read the data to spot overexertion, and training commands use it to manage workloads. Clear clinical meaning supports acceptance by military physicians.
Performance monitors are the fastest growing as forces seek to track core temperature, hydration, sleep, fatigue and recovery together. These devices turn physiological signals into readiness scores that commanders can use to schedule training and rest. Advances in sensors and machine learning improve accuracy, and special operations units are early adopters. Demand for injury prevention and cognitive readiness keeps interest high.
⮞In June 2026, the Israel Defense Forces began trials of the Accurate Mini blood pressure sensor for service members. The trials show militaries testing compact vital-sign sensors beyond heart rate.
By Wearable Form, Bodywear Dominates the Military Wearable Medical Device Market and Wristwear Grows Fastest
Bodywear leads because chest straps, adhesive patches and sensor-embedded garments sit close to the torso, where signals are most reliable. They suit physically demanding tasks and can be worn under uniforms and armor. Medical-grade electrocardiogram and respiration sensing is easier from the chest than from the wrist, so units responsible for casualty care prefer it.
Wristwear is the fastest growing as rugged watches and bands are cheap, familiar and comfortable for long wear. Soldiers already use them for navigation and fitness, so training time is short. Battery life, secure data handling and sensor accuracy are improving, and rings and bands now track sleep and recovery. Procurement offices find wrist devices easy to pilot at scale.
⮞In 2026, the European Commission opened a European Defence Fund call for smart textile materials, running from 11 February to 29 September. Textile-based sensing is moving toward funded defense projects.
By End User, Army Dominates the Military Wearable Medical Device Market and Is Also the Fastest Growing
The Army leads because ground forces are the largest group and face heat, load carriage, long marches and combat injuries. Large training populations create heat illness risk, so commands invest in monitoring that can prompt rest and cooling. Casualty care on the battlefield also benefits from remote vital-sign tracking, which helps medics prioritize the most serious cases.
The Army is also the fastest growing as programs move from pilots to wider fielding across brigades and training centers. Soldier-worn sensors support heat injury prevention, fatigue management and medic triage. Research laboratories partner with industry to test devices in field exercises. Navy and Air Force programs are growing but start from smaller bases.
⮞In September 2025, the Walter Reed Army Institute of Research reported a study in which 47 military medical students wore LifeLens patches to track vital signs. The study shows research units validating wearable sensors with service members.
By Connectivity, Bluetooth and Short-Range Dominates the Military Wearable Medical Device Market and Cellular and Satellite Grows Fastest
Bluetooth and short-range links lead because they use little power and pair sensors with phones, radios and body-worn hubs. Most commercial devices already rely on them, so units can field products quickly. They suit squad-level monitoring, where a team leader or medic collects data in close range and passes it on through tactical networks.
Cellular and satellite connectivity is the fastest growing as commanders want vital signs reported from remote locations and long-range operations. Devices that connect without a nearby gateway reduce the equipment soldiers must carry. Secure encryption and low-power designs are needed, and tactical network upgrades are expanding coverage in training areas and deployed theaters.
⮞In May 2025, researchers at TNO in the Netherlands reported a machine learning model that predicted exertional heat stroke 33 to 69 minutes before collapse using wearable sensor data. Streaming data to analytics tools is a clear use case for reliable links.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
92.31 |
|
Europe |
United Kingdom |
24.64 |
|
Asia Pacific |
China |
33.57 |
|
Latin America |
Brazil |
41.85 |
|
Middle East & Africa |
Israel |
31.72 |
North America Military Wearable Medical Device Market Insights
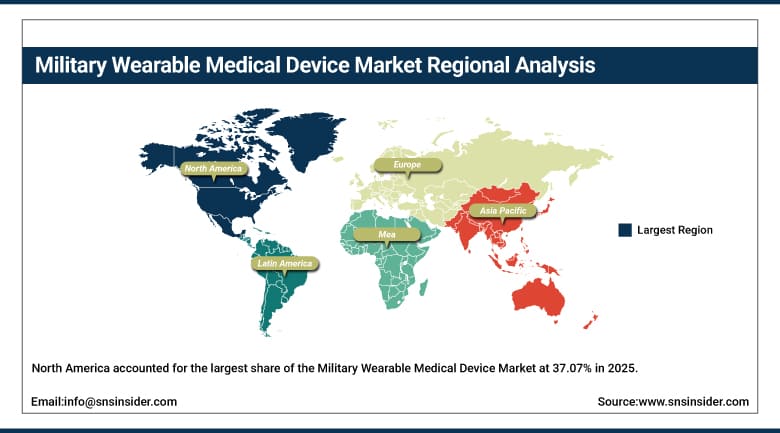
North America accounted for the largest share of the Military Wearable Medical Device Market at 37.07% in 2025, led by the United States and followed by Canada. The region is also the fastest growing, at a CAGR of 27.20% over 2026-2035. The Department of Defense funds human performance research and operates large training centers where heat illness risk is high.
Commercial wearable makers work closely with military laboratories, which speeds the move from prototypes to fielded devices. Canada is modernizing soldier equipment and buying physiological sensors. Security reviews and long testing cycles slow procurement, and agencies have cancelled or reshaped solicitations when requirements changed.
⮞In May 2026, Canada's Department of National Defence closed a tender through Public Services and Procurement Canada for physiological sensors. The tender shows Canadian forces preparing to buy body-worn monitoring.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Military Wearable Medical Device Market Insights
Europe held about 26.80% of the Military Wearable Medical Device Market in 2025 and is led by the United Kingdom, Germany, France, Italy and the Netherlands. Defense budgets are rising across the continent, and national research institutes work on heat stress, fatigue and smart uniforms with industry partners.
European Defence Fund projects bring together universities and companies to develop textile sensors and soldier systems. Strict data protection and medical device rules shape product design, and procurement is fragmented across national forces. NATO interoperability goals encourage common standards for soldier-worn systems.
⮞In December 2024, the CAPSARII consortium led by Politecnico di Milano and NTNU began a 36-month project funded by the European Defence Fund. The project develops wearable systems to monitor soldier health and performance.
Asia Pacific Military Wearable Medical Device Market Insights
Asia Pacific held about 24.90% of the Military Wearable Medical Device Market in 2025. China, Japan, India, South Korea and Australia lead, supported by larger armies, rising defense spending and active soldier modernization programs. Japan's ground forces and Australia's army are both trialing commercial sensors.
Local electronics makers supply low-cost wearable hardware, and regional militaries seek devices that handle tropical heat and humidity. Procurement rules differ widely between countries, and many programs remain at trial stage. Partnerships with global sensor firms help transfer technology, while export controls can limit access to some components.
⮞In October 2025, the Australian Army trialed a wearable heat-risk monitor for soldiers, as reported by Defence Connect. The trial addresses heat illness during training in hot conditions.
MEA & Latin America Military Wearable Medical Device Market Insights
Latin America and the Middle East and Africa together hold about 11.23% of the Military Wearable Medical Device Market. In the Middle East, Israel, Saudi Arabia and the United Arab Emirates lead, investing in soldier technology and health monitoring. In Latin America, Brazil, Mexico, Chile and Colombia are the main buyers.
Gulf countries buy advanced systems through partnerships with foreign suppliers, while Israel's forces develop and test sensors in the field. Latin American armies work with tight budgets and often rely on research institutes and imported devices. Maturity of local technology is limited, and procurement cycles are long.
⮞In June 2025, a Brazilian Army study from EsPCEx and FAMA TECH concluded that most military biosensors are at technology readiness levels 5 to 7. The finding shows the technology is still approaching full operational use.
Market Dynamics:
Growth Drivers: Heat Injury Prevention and Readiness Monitoring Drive Growth in the Military Wearable Medical Device Market
Heat injury prevention is the main driver. Heat stroke and exhaustion cases remain a serious problem in training and operations, and early warnings from wearable sensors can trigger rest, cooling and medical response. Commanders see monitoring as a way to protect personnel and avoid lost training days.
Readiness monitoring adds momentum. Fatigue, sleep and recovery data help leaders manage workloads and reduce injuries. Artificial intelligence models turn sensor streams into alerts that medics can act on. Commercial wearables are cheap enough to field widely, and militaries are now writing requirements around them.
⮞In May 2026, the Naval Health Research Center reported that the Navy's CREW fatigue system uses commercial smart rings to track sleep and readiness. The system shows commercial devices entering official military programs.
Restraints: Validation Burden and Data Security Concerns Restrain Growth in the Military Wearable Medical Device Market
Validation burden restrains growth. Commercial devices vary widely in accuracy, and military laboratories must test them under heat, sweat, motion and armor before approval. Testing takes time and money, and many promising products stay in pilot status. Procurement offices struggle to compare devices with different sensors and software.
Data security concerns add further limits. Physiological data can reveal location, fitness and readiness, so commanders worry about leaks and tracking by adversaries. Devices must meet strict cybersecurity rules, and cloud storage raises policy questions. Soldiers may also worry about privacy, which can reduce willingness to wear devices.
⮞In July 2025, the Joint Program Executive Office for Chemical, Biological, Radiological and Nuclear Defense reported screening nearly 400 commercial wearable devices, with the WARP platform's first operational test held in November 2024. The scale of screening shows how demanding validation is.
Opportunities: Smart Textiles and Predictive Analytics Create Opportunities in the Military Wearable Medical Device Market
Smart textiles offer a major opportunity. Sensors woven into uniforms, base layers and body armor remove the need for separate devices and can track vital signs continuously. European and U.S. research programs are funding materials, and companies that develop washable, durable fabrics can win long-term supply contracts.
Predictive analytics offer further potential. Models trained on large sets of physiological data can forecast heat stroke, injury and fatigue before symptoms appear. Platforms that combine data from many soldiers give commanders a unit-level picture. Software subscriptions can add recurring value for suppliers, and allied forces can share validated algorithms.
⮞In April 2026, the Air Force Research Laboratory's 711th Human Performance Wing awarded a three-year contract to AeroVironment's UES unit. The award signals continued federal support for human performance research.
Recent Developments:
-
In April 2026, WHOOP announced a contract with MIT Lincoln Laboratory connected to the U.S. Navy's CREW fatigue monitoring program. The agreement expands the use of the company's wearable in a formal military research effort.
-
In September 2025, MOTHER Labs, part of MEDIROM, announced work involving its REMONY wearable and the Japan Ground Self-Defense Force's 8th Division. The collaboration points to Asian forces testing commercial health monitors.
-
In August 2025, Oura announced a Department of Defense partnership and plans for a manufacturing facility in Fort Worth, Texas. The company said the facility supports production of its smart rings for U.S. government customers.
Military Wearable Medical Device Market Key Players:
-
Oura
-
WHOOP, Inc.
-
LifeLens Technologies
-
Hexoskin
-
Equivital
-
Garmin Ltd.
-
Medtronic plc (Zephyr)
-
Aptima, Inc.
-
Odic
-
MOTHER Labs (MEDIROM)
-
Masimo Corporation
-
Empatica Inc.
-
Pison Technology
-
NIRSense
-
Vivonics, Inc.
-
cosinuss GmbH
-
Rheinmetall AG
Military Wearable Medical Device Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.87 Billion |
| Market Size by 2035 | USD 117.83 Billion |
| CAGR | CAGR of 25.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Heart Monitors and Performance Monitors) • By Wearable Form (Bodywear, Wristwear, Headwear, and Others) • By End User (Army, Navy, and Air Force) • By Connectivity (Bluetooth and Short-Range, Cellular and Satellite, and Mesh Radio) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Oura, WHOOP, Inc., LifeLens Technologies, Hexoskin, Equivital, Garmin Ltd., Medtronic plc (Zephyr), Aptima, Inc., Odic, MOTHER Labs (MEDIROM), Masimo Corporation, Empatica Inc., Pison Technology, NIRSense, Vivonics, Inc., cosinuss GmbH, Rheinmetall AG |

Frequently Asked Questions
Key players include Oura, WHOOP, LifeLens Technologies, Hexoskin, Equivital, Garmin, Medtronic (Zephyr), Aptima, Odic, MOTHER Labs (MEDIROM), Masimo, Empatica, Pison Technology, NIRSense, Vivonics, cosinuss and Rheinmetall.
Key opportunities include smart textiles built into uniforms, predictive analytics for heat stroke and fatigue, secure long-range connectivity and wider fielding in the Army, Navy and Air Force.
Heat injury prevention and the push for continuous readiness monitoring of personnel are the main growth factors.
By Device Type, the Heart Monitors segment dominated the market in 2025 with an estimated 56.90% share, supported by mature and validated cardiac sensing.
North America dominated the market with a share of 37.07% in 2025, driven by Department of Defense funding and close links between laboratories and wearable makers.
