
Automation Control Components and Devices Market Report Scope and Overview
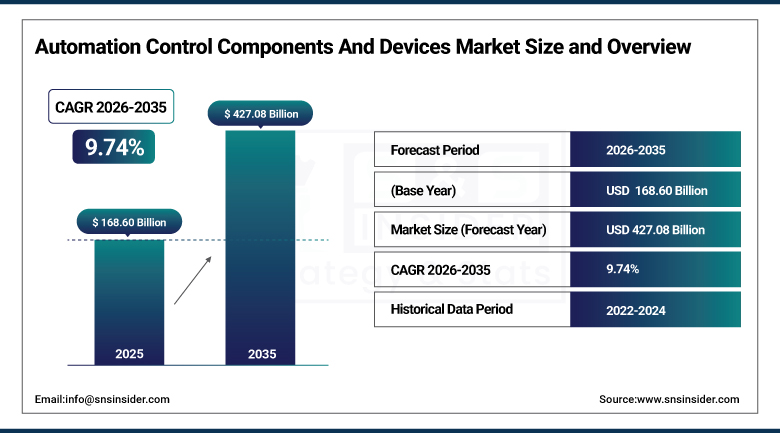
The Automation Control Components and Devices Market was valued at USD 168.60 Billion in 2025 and is estimated at USD 185.02 Billion in 2026. The market is forecast to reach USD 427.08 Billion by 2035, registering a CAGR of 9.74% from 2026 to 2035. Growth reflects investment in factory modernization, rising use of robots and motion systems, and wider adoption of connected controllers and sensors. The scope covers revenue from the controllers, drives, sensors, actuators, relays, switches, and communication devices that run automated equipment. Both stand-alone parts and components sold inside packaged machine kits are counted.
To Get more information On Automation Control Components And Devices Market - Request Free Sample Report
Key Market Trends & Insights
-
By component: Servo motors, drives and motion components held the largest market share of 23.40% in 2025.
-
By technology: Conventional programmable automation held the largest market share of 36.20% in 2025.
-
By end use: Automotive and EV held the largest market share of 21.60% in 2025.
-
Asia Pacific accounted for the largest regional share of 37.80% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 11.28% from 2026 to 2035.
-
The U.S. is the leading country market, supported by reshoring of manufacturing, a large base of installed factory equipment, and strong spending on robots and controls.
Growth Outlook
Robot installations are climbing, and each robot cell pulls in servo drives, controllers, sensors, and safety devices. In September 2026, the International Federation of Robotics reported more than 600,000 industrial robot installations worldwide in 2025, an increase of 11.00%, taking the operational stock to about 5 million units. China installed 354,000 units, which is 59.00% of the global total. Such volumes show how factory investment translates into steady orders for control components, and suppliers of motion and sensing parts benefit directly from every new line.
Factory activity in the United States is strengthening. In November 2026, the Institute for Supply Management reported that its October manufacturing index reached 55.50%, the tenth consecutive month of expansion, with the production index at its highest level since late 2021. Strong output and rising order books encourage plant managers to replace aging controllers and to add sensors and drives, and the improving mood also supports capital budgets for automation projects that were delayed in earlier years. Suppliers report firmer quotations.
Market Dynamics
Driver: Smart Factory Programs, Robot Adoption, and Industrial Connectivity Support Demand
The government is trying to automate the industries through its initiatives. In October 2026, China's Ministry of Industry and Information Technology revealed that it is coming up with smart manufacturing policies for the next generation to adopt the use of artificial intelligence in manufacturing. They have tiered smart factories with more than 13,000 factories classified at an advanced level of operations. The upgrade of each factory requires controllers, edge devices, industrial networks, and sensors. Such policy trends create opportunities for the manufacturers for several years to come because the electronics, automotive, and machinery companies will need to upgrade their plants and purchase components for several years to come. Provinces also subsidize equipment upgrade expenses, which speeds up the replacement of older controllers.
European demand is recovering as order books fill. In November 2026, the German electrical industry association ZVEI reported that orders in the country rose 9.60% year on year in its latest monthly release, with foreign orders up 2.10% and real production up 3.40%. Automation hardware is a large share of electrical output, so rising orders signal stronger shipments of drives, controls, and sensors, and machine builders that supply factories worldwide are adding capacity and renewing product lines to meet the pickup in demand. Distributors in the region report improving inventory turns, and replacement cycles for drives and controllers are shortening as energy efficiency rules reward modern products.
Restraint: Trade Actions, Cyber Risk, and Cyclical Capital Spending Limit Growth
The policy on trade creates an uncertain environment for supply chain management. The White House signed a proclamation in October 2026, indicating that imports of robotics, industrial machines, and the parts and components pose a risk to national security, even though there was not imposition of tariff charges and negotiation with trading partners to be done within 180 days. Buyers of components are at risk of duties imposed on imports of drives, controllers, and sensors, thus creating uncertainties in procurement of supplies and pricing, and buyers prefer to wait for the negotiations' results before ordering. There is also an increased burden of documentation to importers, while manufacturers with facilities in different regions are moving production around to avoid delays and customer price hikes.
The cyber threat represents the second issue for plant owners. The joint alert from the Cybersecurity and Infrastructure Security Agency was issued together with other federal agencies in April 2026 concerning that Iran-linked entities were using vulnerabilities in internet-connected programmable controllers and manipulating project files and operator interface displays. Such events make operators careful about the connection of their legacy equipment, and cybersecurity assessment extends project timelines and budgets. Moreover, automation capital investments drop if the productivity in the factory declines, and this leads to irregular orders of suppliers. Small-scale plants do not have their own cybersecurity teams, and suppliers need to provide easy-to-use products in order to get these clients, which increases the development expenses.
Opportunity: Security-Ready Products, Local Component Manufacturing, and Machine Compliance Create New Revenue
New rules are creating demand for secure and compliant devices. In September 2026, the European Union Agency for Cybersecurity began operating the single reporting platform for vulnerability and incident notices under the Cyber Resilience Act, with a 24-hour early warning duty for manufacturers. A new Machinery Regulation also applies from the start of 2027, and both rules favor suppliers that build security and safety functions into controllers and drives, while customers replace products that cannot meet the standards. Suppliers that certify products against recognized security standards can charge higher prices, and system integrators are building services around compliance audits and upgrade programs for existing lines.
India is building a local base for electronic components. In August 2026, the Ministry of Electronics and Information Technology approved the first tranche of 31 projects under its electronics component manufacturing scheme. Such programs expand the supply of sensors, connectors, and power parts inside the country and create a growing customer base for automation suppliers. Demand for retrofit kits and wireless sensors is also rising among small and medium-sized manufacturers that want gradual upgrades. Electronics, medical device, and packaging producers in the country are also expanding, and suppliers that localize assembly, training, and service can win long-term supply agreements with these customers.
Market Characteristics & Concentration
The Automation Control Components and Devices Market is Moderately Consolidated. A group of large global suppliers from Europe, Japan, and North America hold broad portfolios that span controllers, drives, sensors, and software, while specialist firms compete in sensors, pneumatics, connectors, and safety devices. Installed base, brand trust, and integration skills shape purchasing decisions. Distributor networks and system integrators extend the reach of large suppliers into smaller plants. Pricing power rests on product breadth.
There has been a shift towards open platforms and software in terms of competition. The suppliers have embedded artificial intelligence capabilities, edge computing, and cloud connectivity in their controllers, and the customers are increasingly asking for interconnectivity with industrial networks. There have been several suppliers restructuring their portfolio through mergers and acquisitions, while the regional suppliers in China and India have increased their market shares in the low-cost range of products.
Public programs also guide product design. In May 2026, the National Institute of Standards and Technology released an initial public draft of guidance on responding to and recovering from cyber attacks in the manufacturing sector. Such guidance pushes suppliers to build recovery and monitoring features into their products and shapes the requirements that plant owners place on new equipment. Standards bodies and industry groups also guide product certification and interoperability.
Analyst Perspective
Automation control components sit at the center of factory investment, and demand now reaches well beyond automotive plants into electronics, logistics, food, and energy. Servo and motion products lead revenue, while industrial communication devices and artificial intelligence enabled systems are growing fastest. Product lifecycles are long, which supports steady spare part and upgrade sales for suppliers with large installed bases. Trade actions and cyber risk create caution, yet reshoring, labor shortages, and smart factory programs keep order books healthy across regions. An SNS Insider Analyst, Santosh Bhul, commented, "Suppliers that combine secure, interoperable controllers with strong motion and sensing portfolios will outgrow the market, and Asia Pacific will add the fastest demand through 2035."
Segment Analysis
Component Insights
The share of servo motors, drives and motion components was the highest at 23.40% in 2025. Such components are responsible for moving and positioning equipment in robotic systems, packaging lines, machine tools, and conveyors, and practically every automated cell requires such components. Accuracy, responsiveness, energy-efficiency and compatibility with the best controllers are among the most important features buyers seek, thus suppliers with full motion systems and service capabilities are at an advantage. Safety features, feedback from encoders and network capabilities are being added to drives by suppliers, and each additional capability increases the value of the drive.
Industrial communication and I/O devices are projected to grow at the fastest CAGR of 11.72% from 2026 to 2035. Plants connect more machines to networks, and gateways, remote I/O modules, and industrial Ethernet switches are needed to move data to controllers and analytics tools. Controllers, sensors, and actuators remain large product groups with steady replacement demand. Demand is also supported by retrofit projects, since older equipment can be linked to plant networks through add-on modules without replacing the main controllers. Security features and time-sensitive networking are becoming common requirements in new purchases.
Technology Insights
Conventional programmable automation held the largest share of 36.20% in 2025. Fixed programs running on programmable controllers still operate most production lines in automotive, electronics, and consumer goods plants, and the installed base requires spare parts, upgrades, and expansion modules. Proven reliability, trained maintenance staff, and long product lifecycles keep this approach in wide use even as newer technologies spread across factories. Suppliers continue to release faster controllers with open programming languages and built-in networking, which helps plants extend the life of existing lines while preparing for gradual upgrades. Upgrades are gradual.
AI-enabled automation is projected to grow at the fastest CAGR of 14.86% from 2026 to 2035. Vision systems, predictive maintenance, and adaptive control use artificial intelligence to raise yield and reduce downtime. Flexible and modular automation also gains ground as manufacturers produce smaller batches and need lines that can be reconfigured quickly. Adoption is strongest in electronics, automotive, and pharmaceutical plants that have large volumes of sensor data. Suppliers are embedding models in controllers and edge devices so that decisions are made close to the machine, and software subscriptions are growing alongside hardware.
End Use Insights
Automotive and EV held the largest share of 21.60% in 2025. Vehicle plants run welding, assembly, painting, and battery production lines that depend on drives, controllers, sensors, and safety devices, and electric vehicle programs add new battery and motor lines. Capital spending follows model launches and plant retooling cycles, so orders can vary from year to year, although long programs support steady demand. Tier one suppliers also invest in flexible lines that handle several vehicle models, which increases the number of sensors and servo axes per station and keeps component demand healthy despite slower unit volumes in some markets.
Logistics and warehousing is projected to grow at the fastest CAGR of 12.38% from 2026 to 2035. Sorting systems, conveyors, shuttles, and mobile robots need motors, sensors, and controllers in large numbers, as e-commerce and retail operators automate fulfillment centers. Electronics, food, and energy producers also add steady demand. Parcel carriers, grocery chains, and manufacturers are building automated storage and retrieval systems, and these projects specify drives, safety scanners, and networked I/O. Labor shortages and rising wages strengthen the business case, and payback periods are shortening as equipment prices become more stable.
Regional Insights
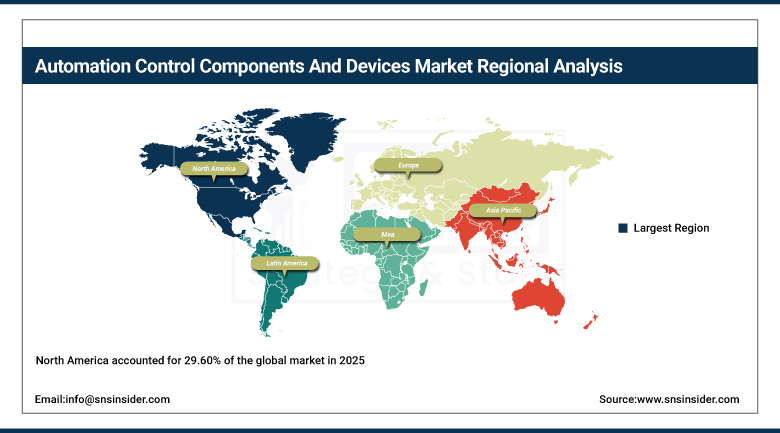
North America accounted for 29.60% of the global market in 2025. The region has a large base of installed factory equipment, strong demand from automotive, aerospace, food, and logistics operators, and growing reshoring of production. Labor shortages push plants to automate, and federal and state incentives support new factories. Canada adds demand through mining, energy, and automotive plants. Distributors and system integrators are well developed, which helps suppliers reach small and mid-sized plants that buy through local channels.
Get Customized Report as per Your Business Requirement - Enquiry Now
U.S. Automation Control Components and Devices Market
The U.S. market was valued at USD 40.92 Billion in 2025 and is expected to register a CAGR of 9.12% from 2026 to 2035. Demand is led by automotive and EV plants, semiconductor and battery factories, food and beverage processors, and warehouse automation, while aerospace and defense producers add specialized orders. Reshoring programs and labor shortages are raising investment in robots, drives, and controllers. Large suppliers have also announced new assembly and training centers in the country to serve growing orders. Defense contractors also add orders.
Buyers weigh reliability, cyber security features, local service, and compatibility with installed systems. Trade policy shapes sourcing decisions, and suppliers are expanding assembly and repair capacity in the country. Distributors and system integrators play a large part in sales to small and medium-sized manufacturers, and many plants favor retrofit projects that extend equipment life. Plant owners also ask for longer warranties and remote support. Suppliers also train technicians and integrators through certified programs, and large customers sign multi-year supply agreements to secure delivery of drives, controllers, and sensors while lead times remain uneven across product groups.
Europe Automation Control Components and Devices Market
Europe accounted for 25.40% of the global market in 2025, with Germany, Italy, France, the United Kingdom, and Spain as the largest country markets. The region is home to leading suppliers of controllers, drives, and sensors, and machine builders export equipment worldwide. Energy efficiency rules, new machinery and cyber security regulations, and investment in battery and renewable energy plants support demand across the region. Suppliers also focus on sustainable manufacturing and retrofit projects. Retrofit demand remains steady.
Asia Pacific Automation Control Components and Devices Market
Asia Pacific accounted for 37.80% of the market in 2025 and is anticipated to register the fastest regional CAGR of 11.28% from 2026 to 2035. China, Japan, South Korea, India, and Taiwan lead demand, supported by electronics, automotive, and battery manufacturing. China is the largest national buyer of robots and controls, while Japan and South Korea are major suppliers and Southeast Asia attracts new plants. Local suppliers are growing quickly and compete on price in standard products.
Latin America Automation Control Components and Devices Market
Latin America accounted for 4.00% of the market in 2025, with Brazil as the leading country market followed by Mexico, Argentina, and Chile. Demand comes from automotive assembly, food and beverage processing, mining, and oil and gas operations, and most components are imported. Nearshoring investment in Mexico is raising orders for controllers, drives, and sensors from plants that serve North American customers. Distributors provide most local service and technical support. Currency swings affect import prices.
Middle East & Africa Automation Control Components and Devices Market
Middle East & Africa accounted for 3.20% of the market in 2025, with Saudi Arabia, the United Arab Emirates, Turkey, South Africa, and Israel as the main country markets. Oil, gas, petrochemical, mining, and power projects use large volumes of process control and motor control devices, and industrial diversification programs in Gulf countries are adding factories. Most devices are imported. Plant builders and engineering contractors choose most of the devices used in large projects. Service contracts matter.
Key Automation Control Components and Devices Market Company Insights
Companies in the automation control components and devices market are focusing on software-defined control, industrial artificial intelligence, secure connectivity, and portfolio reshaping. Large suppliers are acquiring software and edge computing firms, while others are separating non-core businesses to concentrate on industrial automation.
Key Automation Control Components and Devices Companies:
-
Siemens
-
Rockwell Automation
-
Schneider Electric
-
ABB
-
Emerson Electric
-
Honeywell Technologies
-
Mitsubishi Electric
-
Omron
-
Yokogawa Electric
-
Fanuc
-
Phoenix Contact
-
Eaton
Recent Developments
-
In November 2026, Yokogawa Electric was selected as main automation contractor for the second phase of the LNG Canada project, covering control and safety systems.
-
In November 2026, Rockwell Automation reported fiscal 2026 sales of USD 8.99 Billion, up 8.00%, with its software and control segment growing 18.00%.
-
In November 2026, ABB said that China's foreign investment security review office blocked the China part of the planned sale of its robotics division, and the transaction had not closed.
-
In October 2026, Schneider Electric reported record third-quarter revenue and raised its 2026 adjusted EBITA growth target to between 18.00% and 21.00%.
-
In October 2026, Mitsubishi Electric agreed to form a joint venture for its low-voltage power distribution business, with a European partner taking a 51.00% controlling stake.
-
In July 2026, Siemens agreed to acquire Precision Innovations, a developer of artificial intelligence chip-planning software, with closing expected in the third quarter.
-
In June 2026, Honeywell Technologies began operating as an independent industrial automation company after the spin-off of its aerospace business was completed.
Scope and Research Methodology
This report defines the automation control components and devices market as the revenue generated by controllers, programmable logic controllers, drives, servo motors, sensors, actuators, relays, switches, and industrial communication devices that control automated equipment and processes. Coverage includes conventional, flexible, and artificial intelligence enabled systems, used in automotive, electronics, food, logistics, energy, and other plants. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Software licenses and engineering services are outside the scope. Standalone software and engineering services are not counted, and robots are included only to the extent of the control components inside them.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, controls engineers, procurement managers, and other stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test the direction of demand in each region and end use before any figure is finalized for the study. Interviews follow a structured guide so that responses are comparable across respondents and regions, and findings are logged against the assumptions they affect.
Market engineering follows a bottom-up build from device shipments, price bands by component type, and supplier revenue, cross-checked top-down against factory investment, robot installations, and industrial production. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate the drivers that shape demand, including regulation, technology maturity, and macroeconomic conditions. Senior analysts review every estimate, assumption, and narrative section for consistency before release, and figures are checked against the segment and regional totals so that the final model remains internally coherent. Where inputs differ, analysts revisit the underlying assumptions with sector experts and adjust the model only when the evidence supports a change, so that the published figures stay traceable to documented inputs.
Automation Control Components and Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 168.60 Billion |
| Market Size by 2035 | USD 427.08 Billion |
| CAGR | CAGR of 9.74% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Servo Motors, Drives and Motion Components, Controllers, PLCs and Industrial PCs, Sensors and Measurement Devices, Industrial Communication and I/O, and Others) • By Technology (Conventional Programmable Automation, Flexible and Modular Automation, AI-Enabled Automation, and Others) • By End Use (Automotive and EV, Electronics and Semiconductor, Food and Beverage, Logistics and Warehousing, Energy and Power, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens, Rockwell Automation, Schneider Electric, ABB, Emerson Electric, Honeywell Technologies, Mitsubishi Electric, Omron, Yokogawa Electric, Fanuc, Phoenix Contact, Eaton |

Frequently Asked Questions
The market was valued at USD 168.60 Billion in 2025 and is projected to reach USD 427.08 Billion by 2035.
The market is expected to register a CAGR of 9.74% from 2026 to 2035.
Asia Pacific led the market with a 37.80% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 11.28% from 2026 to 2035.
Servo motors, drives and motion components led the component segment with a 23.40% share in 2025, and conventional programmable automation led the technology segment.
