
Automotive Active Health Monitoring System Market Report Scope & Overview:
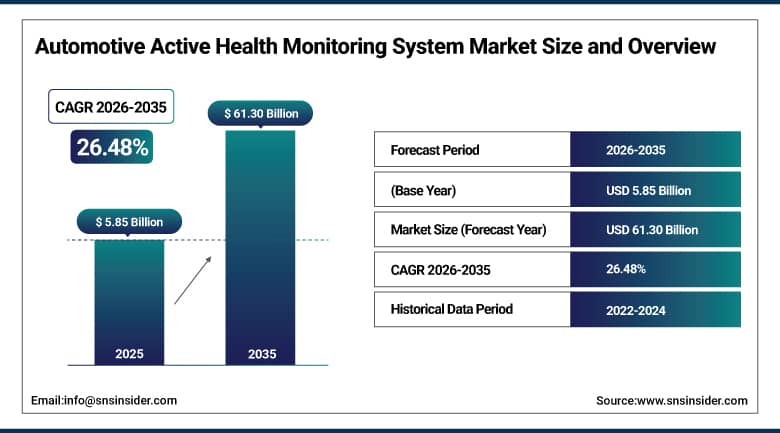
The Automotive Active Health Monitoring System Market was valued at USD 5.85 Billion in 2025 and is expected to reach USD 61.30 Billion by 2035, growing at a CAGR of 26.48% from 2026-2035.
The Automotive Active Health Monitoring System Market growth will be significantly propelled by rising safety regulations, which require driver monitoring technologies as well as the emergence of technological convergence to provide biometric sensors in steering wheels, seats, and dashboard with accuracy that surpasses 95%. The systems have been designed to make use of state-of-the-art sensors and artificial intelligence algorithms to check the driver's and passenger's health status such as fatigue, distraction, and cardiovascular status among others. According to World Health Organization reports, there were around 1.19 million fatalities caused by traffic accidents per year, where developing countries account for most of them despite having fewer vehicles in the world.
In January 2025, Continental presented its Invisible Biometrics Sensing Display at CES in Las Vegas, a CES Innovation Award Honoree that tracks the vital parameters of vehicle occupants using a concealed camera and eye-safe laser dot projector installed behind a high-resolution OLED display, remaining completely invisible to the naked eye while supporting a wide range of safety and comfort functions. The technology reflects continued supplier investment in unobtrusive, aesthetically integrated biometric sensing solutions, reinforcing the competitive importance of combining advanced health monitoring capability with seamless interior design as automakers increasingly compete on cabin experience alongside traditional safety performance.
To Get More Information On Automotive Active Health Monitoring System Market - Request Free Sample Report
Automotive Active Health Monitoring System Market Trends
- Rising integration of AI-driven analytics enabling continuous evaluation of fatigue, stress, and cardiovascular indicators.
- Growing adoption of invisible and unobtrusive biometric sensing technology concealed within dashboard and display components.
- Expanding integration of in-vehicle health monitoring with external wearable devices for continuous health tracking.
- Increasing OEM investment in biometric authentication combined with health and wellness monitoring capability.
- Rising extension of health monitoring systems toward autonomous-vehicle handover and emergency response functions.
- Growing regulatory attention to driver-monitoring technology mandates across major automotive markets.
U.S. Automotive Active Health Monitoring System Market Outlook
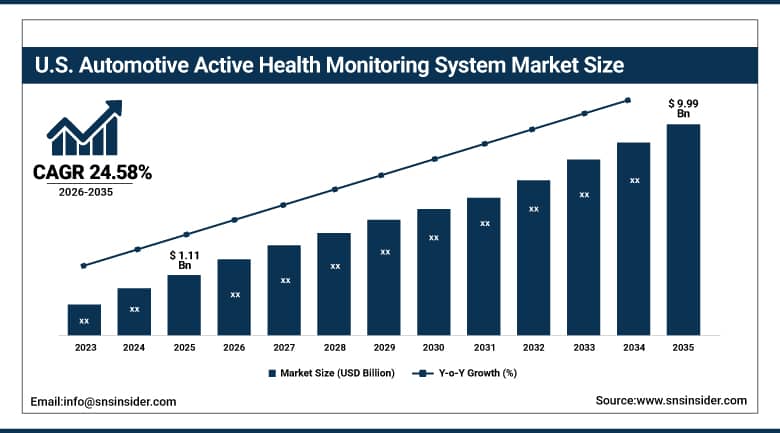
The U.S. Automotive Active Health Monitoring System Market was valued at USD 1.11 Billion in 2025 and is expected to reach USD 9.99 Billion by 2035, growing at a CAGR of 24.58% from 2026-2035.
The U.S. Automotive Active Health Monitoring System Market growth continues to be reinforced by domestic automakers' continued investment in driver-monitoring and wellness technology, exemplified by systems including facial-recognition-and-steering-feedback drowsiness detection and cabin AI platforms that evaluate biometric and environmental data to personalize driving conditions. Leading premium electric vehicle programs continue to pioneer medical-grade biometric monitoring capability, extending health monitoring integration to include compatibility with external wearable devices for continuous monitoring that extends beyond the vehicle itself. Rising numbers of long-distance commuters and connected drivers continue to elevate fatigue, stress, and health-related emergency concerns as a growing safety priority for domestic automakers and fleet operators. Growth is further supported by continued domestic supplier investment in AI-based health algorithms and biometric sensor integration.
In February Ford Motor Company highlighted continued development of its BlueCruise driver-monitoring technology, which uses a driver-facing camera to track eye gaze and head position and provide escalating alerts when attention shifts from the road. With BlueCruise deployed across multiple Ford and Lincoln vehicle lines in the U.S., its continued software development supports domestic adoption of camera-based driver-state monitoring and strengthens demand for AI-enabled in-cabin safety technologies.
Automotive Active Health Monitoring System Market Segment Analysis
- By Component, the Sensors segment dominated the Automotive Active Health Monitoring System Market with approximately 49.60% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 28.60%.
- By Location, the Driver Seat segment dominated the Automotive Active Health Monitoring System Market with approximately 58.60% share in 2025, while the Dashboard segment is the fastest growing with a CAGR of approximately 27.80%.
- By Application, the Fatigue/Drowsiness Detection segment dominated the Automotive Active Health Monitoring System Market with approximately 34.60% share in 2025, while the Stress Level Monitoring segment is the fastest growing with a CAGR of approximately 28.40%.
- By Vehicle Type, the Passenger Cars segment dominated the Automotive Active Health Monitoring System Market with approximately 59.60% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 27.60%.
By Component, Sensors Dominates the Automotive Active Health Monitoring System Market and Software Grows Fastest
Sensors dominated the market since biometric sensing devices such as electrodes, cameras, and pressure sensors that are incorporated into seating, steering wheel, and seat belt are the core technological requirements in gathering the physiological and behavioral information on which health monitoring systems rely. The unique technical accuracy and manufacturing process of automotive biometric sensors are the factors that keep sensors at the top of the component hierarchy.
The software sector is growing faster because AI-based analytics help the active health monitoring platforms distinguish each other using better pattern recognition and prediction of alerts along with their connection to wider vehicle safety and autonomous driving solutions. This trend is facilitated by the growing need for advanced algorithms able to distinguish true medical emergencies from typical driving activity, which still requires improvements of the software part.
By Location, Driver Seat Dominates the Automotive Active Health Monitoring System Market and Dashboard Grows Fastest
The driver seat dominates the market because seat-integrated sensors offer continuous, unobtrusive contact with the driver throughout the journey, enabling reliable heart rate, temperature, and posture monitoring without requiring the driver to wear or interact with additional equipment. This continuous contact advantage continues to sustain the driver seat's position as the largest location category for active health monitoring sensor integration.
Dashboard are the fastest-growing location category as cost-efficient camera integration and wide OEM adoption continue to extend dashboard-based monitoring, including facial recognition and increasingly invisible biometric sensing displays, across a broadening range of vehicle segments. This growth is reinforced by dashboard systems' compatibility with existing driver-monitoring camera infrastructure already being deployed to satisfy advanced driver assistance system requirements, reducing incremental integration cost relative to dedicated seat or steering wheel sensor systems.
By Application, Fatigue/Drowsiness Detection Dominates the Automotive Active Health Monitoring System Market and Stress Level Monitoring Grows Fastest
Fatigue and drowsiness detection dominates the market because impaired driver alertness represents one of the most common and well-documented causes of traffic accidents, making it the foundational and most widely deployed active health monitoring use case across both passenger and commercial vehicle segments. Regulatory and consumer safety expectations continue to reinforce fatigue and drowsiness detection's position as the largest application category for active health monitoring suppliers.
Stress level monitoring is the fastest-growing application as automakers increasingly recognize that elevated driver stress can meaningfully impair reaction time and decision-making even without overt drowsiness symptoms. This growth is reinforced by rising integration of stress monitoring with vehicle response systems capable of suggesting or initiating autonomous control handover when elevated stress levels are detected, extending active health monitoring's role beyond passive alerting into active vehicle intervention.
By Vehicle Type, Passenger Cars Dominates the Automotive Active Health Monitoring System Market and Commercial Vehicles Grows Fastest
The passenger cars dominance is an indicator of the volume of passenger vehicle manufacturing around the world, along with the fact that the majority of safety and wellness features development efforts focus on passenger vehicle platforms, especially high-end and electric vehicles. Manufacturers increasingly include active health monitoring systems in the interiors of passenger vehicles, as wellness systems are introduced from flagships to mainstream models.
Commercial vehicles are the fastest growing segment within the vehicle population, as companies use health monitoring systems to guarantee the safety of drivers and ensure efficiency during operations, especially long-distance hauling of goods or where there is high risk due to tiredness among drivers. This is because more and more fleet managers are using health monitoring systems as a risk reduction measure and to control costs associated with insurance.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
83.60% |
|
Latin America |
Brazil |
28.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Europe Automotive Active Health Monitoring System Market Insights
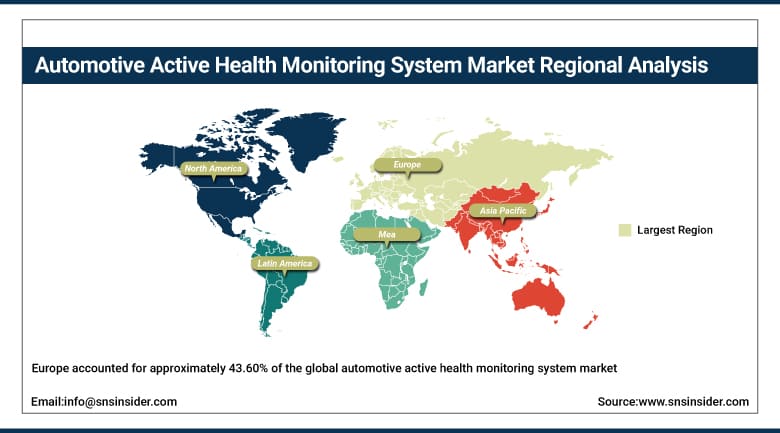
Europe accounted for approximately 43.60% of the global automotive active health monitoring system market in 2025, making it the largest regional market, driven by the presence of major automotive manufacturers, extensive research and development investment in in-car health systems, and new European Union safety regulations. The extensive automotive manufacturing facilities in Germany and presence of high-end automakers have helped support demand in the region with suppliers taking a leading role in the development of new biometric sensors and displays.
Other contributors to growing demand in the region include France, the UK, and Sweden, as regional automakers integrate health monitoring technology from high-end automobiles to mass market vehicles. EU regulations on driver monitoring technology requirements are expected to help Europe maintain its leading position throughout the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Active Health Monitoring System Market Insights
The Asia Pacific region is the fastest-growing regional market and will grow at a CAGR of about 28.20% between 2026 and 2035 due to a number of factors including rapidly increasing vehicle manufacturing, increased consumer demand for safety features, and an increase in government initiatives aimed at encouraging the use of safety technologies in the automotive industry in China, Japan, and South Korea. The domestic vehicle manufacturing base in China continues to drive growth in this sector.
South Korea is contributing significant innovation, with established domestic automakers pursuing bio-signal database development to support smart cabin technology addressing stress management and driver wellness. Growth from India and the Southeast Asia market segments is adding value as increasing car manufacturing drives safety features down to lower pricing, thereby cementing the status of Asia Pacific as the fastest-growing region during the forecast period.
North America Automotive Active Health Monitoring System Market Insights
North America represents a significant share of the global automotive active health monitoring system market, anchored by the United States' concentration of technology-forward automakers and continued investment in driver-monitoring and wellness technology. Domestic automakers continue to pioneer medical-grade biometric monitoring capability, particularly across premium electric vehicle platforms, while extending integration with external wearable devices for continuous health tracking.
Canada is contributing incremental demand as regional automotive safety technology adoption continues to expand. Continued domestic supplier investment in AI-based health algorithms and biometric sensor integration is expected to sustain steady regional growth through the forecast period.
MEA & Latin America Automotive Active Health Monitoring System Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing demand for premium, well-equipped vehicles across the United Arab Emirates and Saudi Arabia sustains gradual interest in advanced safety and wellness features. Regional vehicle assembly remains limited, with much of the region's active health monitoring component supply continuing to be imported from Asian, European, and North American manufacturers.
In Latin America, Brazil is the leader of the market, and the growth of demand for premium and advanced technology vehicles is pushing the integration of active health monitoring systems slowly but surely. In Mexico, there is a contribution to the growth because of the expansion of the automotive production industry in the region.
Market Dynamics
Growth Drivers: Safety Regulation and Biometric Sensor Technology Convergence
Growing safety regulations mandating driver-monitoring technologies represent the primary driver of Automotive Active Health Monitoring System Market growth, as regulatory bodies across major automotive markets increasingly require enhanced driver attention and health monitoring capability to reduce traffic accidents caused by medical emergencies and impaired alertness. This regulatory pressure is directly translating into expanding OEM adoption of biometric sensing technology across a widening range of vehicle segments.
Technological convergence enabling biometric sensors integrated into steering wheels, seats, and dashboards represents a second major growth driver, as detection accuracy exceeding 95% in leading systems continues to build automaker and consumer confidence in active health monitoring reliability. Strategic automotive-industry investment in AI-driven wellness ecosystems supporting the broader autonomous-vehicle transition continues to reinforce this technology convergence, as health monitoring increasingly serves as a foundational input for higher levels of vehicle automation.
Restraints: Privacy Concerns and High Integration Costs
Privacy concerns regarding continuous biometric data collection represent a meaningful restraint on market growth, as consumers and regulators increasingly scrutinize how vehicle manufacturers collect, store, and potentially share sensitive health and biometric information gathered through in-cabin sensing systems. This privacy sensitivity requires automakers to navigate an increasingly complex data governance landscape alongside the underlying sensor technology development.
The high cost of integrating comprehensive biometric sensing hardware and AI-driven analytics software represents a further restraint, as advanced active health monitoring systems require substantial engineering investment that can be prohibitive for cost-sensitive, mass-market vehicle segments. This cost consideration continues to concentrate active health monitoring adoption among premium and luxury vehicle platforms ahead of broader mainstream market penetration.
Opportunities: Wearable Device Integration and Autonomous Vehicle Handover Applications
Continued integration of in-vehicle health monitoring with external wearable devices represents a substantial opportunity, as automakers increasingly enable compatibility with smartwatches and fitness trackers to extend continuous health tracking capability beyond the vehicle cabin itself. Suppliers that can develop seamless, interoperable wearable integration are positioned to capture demand from health-conscious consumers seeking continuity between their vehicle and personal health monitoring ecosystems.
The continued extension of health monitoring systems toward autonomous-vehicle handover and emergency response functions offers a further avenue for growth, as detected medical emergencies or elevated stress levels increasingly trigger automated safety responses, including autonomous control handover or direct emergency service contact. Suppliers that can reliably integrate health monitoring output with vehicle control systems are well positioned to capture demand as automakers pursue increasingly sophisticated, safety-integrated autonomous driving architecture.
Recent Developments:
- 2026: Aptiv launched Advanced Occupancy Classification, using AI and a single interior camera to detect occupant characteristics and support driver-attention, safety, and cabin-monitoring functions.
- 2026: Qualcomm and Bosch expanded their strategic partnership to next-generation ADAS and cockpit solutions, supporting intelligent, connected, and increasingly personalized vehicle experiences through Snapdragon-powered computing.
- 2026: Aptiv showcased next-generation Driver and Cabin Monitoring Systems at CES 2026, combining vision and radar sensing with AI to support safer, personalized in-vehicle experiences.
Automotive Active Health Monitoring System Market Key Players are:
- Robert Bosch GmbH
- Continental AG
- DENSO Corporation
- Valeo SA
- Aptiv PLC
- Magna International Inc.
- NXP Semiconductors N.V.
- Texas Instruments Incorporated
- Harman International Industries, Incorporated
- Tata Elxsi Limited
- Acellent Technologies, Inc.
- Pioneer India Electronics Pvt. Ltd.
- Teletrac Navman
- Qualcomm Technologies, Inc.
- Hoana Medical, Inc.
- Faurecia SE (Forvia)
- Flex Ltd.
- Hyundai Mobis Co., Ltd.
- Kritikal Solutions Pvt. Ltd.
- LORD MicroStrain Sensing Systems
Automotive Active Health Monitoring System Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.85 Billion |
| Market Size by 2035 | USD 61.30 Billion |
| CAGR | CAGR of 26.48% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Sensors, Software, Processing & Control Units, Others) • By Location (Driver Seat, Dashboard, Steering Wheel, Seatbelt, Others) • By Application (Fatigue/Drowsiness Detection, Pulse Rate Monitoring, Blood Pressure Monitoring, Stress Level Monitoring, Others) • By Vehicle Type (Passenger Cars, Commercial Vehicles) • By Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Continental AG, DENSO Corporation, Valeo SA, Aptiv PLC, Magna International Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, Harman International Industries, Incorporated, Tata Elxsi Limited, Acellent Technologies, Inc., Pioneer India Electronics Pvt. Ltd., Teletrac Navman, Qualcomm Technologies, Inc., Hoana Medical, Inc., Faurecia SE (Forvia), Flex Ltd., Hyundai Mobis Co., Ltd., Kritikal Solutions Pvt. Ltd., LORD MicroStrain Sensing Systems |
Frequently Asked Questions
Key players include Robert Bosch GmbH, Continental AG, DENSO Corporation, Valeo SA, Aptiv PLC, Magna International Inc., and Harman International Industries, Incorporated, among other automotive safety technology suppliers.
Continued integration with external wearable devices and continued extension of health monitoring toward autonomous-vehicle handover and emergency response functions represent the primary opportunities.
Growth is primarily driven by growing safety regulations mandating driver-monitoring technologies combined with technological convergence enabling biometric sensors integrated into steering wheels, seats, and dashboards.
By Component, Sensors dominated the market with approximately 49.60% share in 2025, reflecting their foundational role in capturing physiological and behavioral driver data.
Europe dominated the market with approximately 43.60% share in 2025, driven by the presence of major automotive manufacturers and new EU safety regulations.
