
Automotive E-Compressor Market Report Scope & Overview:
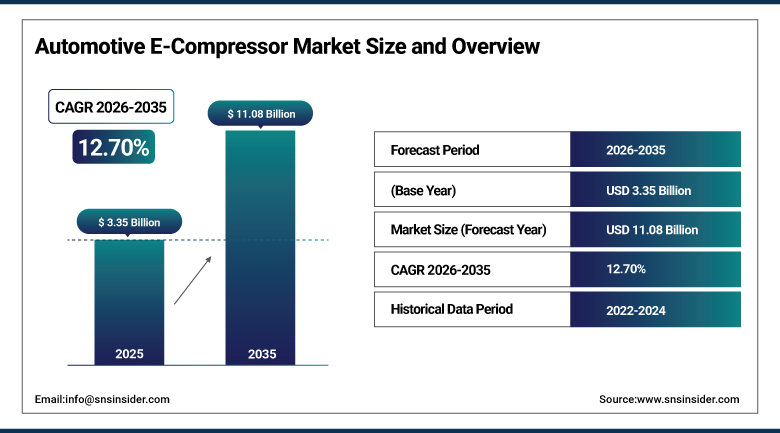
The Automotive E-Compressor Market was valued at USD 3.35 Billion in 2025 and is expected to reach USD 11.08 Billion by 2035, growing at a CAGR of 12.70% from 2026-2035.
The growth in the market for the Automotive E-Compressor is being propelled mainly by the rising output of electric and hybrid vehicles. These vehicles will need electric compressors that are not dependent on the mechanical power of the engine to regulate the climate inside the cabin, cool down the batteries, and maintain temperatures within the electronic systems. Unlike the traditional belt-operated compressors, these e-compressors can operate on high-voltage electrical power and function regardless of whether the internal combustion engine or electric drive system of the automobile is running, something which has become an absolute necessity as manufacturers are going electric with their lineup.
In October 2024, Hanon Systems announced plans to build its first North American electric compressor manufacturing plant in Woodbridge, Ontario, Canada, representing a USD 111 million investment with annual production capacity of up to 900,000 electric scroll compressors. The facility, expected to begin production in the first half of 2025, underscores how leading thermal management suppliers are localizing electric compressor manufacturing closer to major North American vehicle assembly plants to serve growing automaker demand for hybrid and battery electric vehicle components.
To Get more information Automotive E-Compressor Market - Request Free Sample Report
Automotive E-Compressor Market Trends
-
Growing adoption of high-voltage e-compressor platforms enabling faster cabin climate control and rapid thermal cycling.
-
Rising integration of e-compressors into medium and heavy commercial vehicle electrification programs.
-
Continued refinement of scroll compressor designs for improved efficiency and reduced noise, vibration, and harshness.
-
Increasing use of R744 (CO2) refrigerant-based e-compressor systems to extend electric vehicle driving range.
-
Expanding automaker investment in localized e-compressor manufacturing capacity near vehicle assembly hubs.
U.S. Automotive E-Compressor Market Outlook
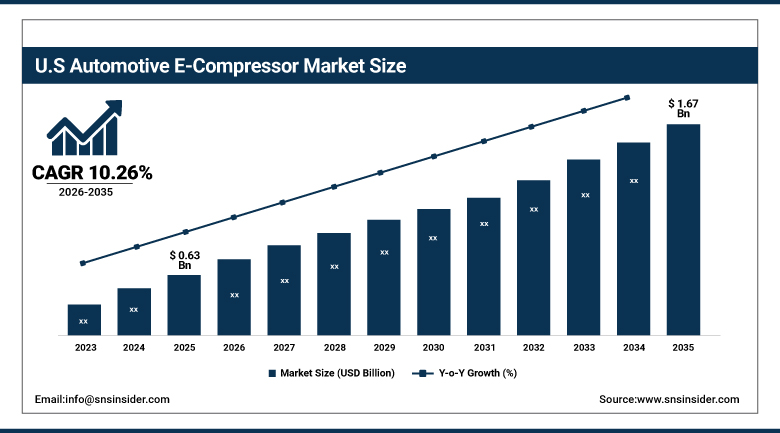
The U.S. Automotive E-Compressor Market was valued at USD 0.63 Billion in 2025 and is expected to reach USD 1.67 Billion by 2035, growing at a CAGR of 10.26% from 2026-2035.
U.S. Automotive E-Compressor Market is expected to continue gaining traction due to the presence of continuous production of electric vehicles/hybrid vehicles domestically, increasing investments made by automakers into the manufacture of thermal management components in local environments, and increased customer expectations with regard to the level of comfort in the vehicle’s cabin and performance during winter months. Increased demand is also due to the continued policy support in favor of vehicle electrification that continues the investments by manufacturers in electric and hybrid platforms requiring e-compressor technology.
In March 2024, Cummins unveiled its first electric compressor designed exclusively for fuel cell engine applications, featuring a 45 kW high-speed electric motor capable of a maximum design speed of 110,000 rpm, intended for fuel cell engines in the 150 kW to 260 kW range operating under energy recovery turbine systems. The launch reflects Cummins' continued investment in zero-emission technology components as part of its broader strategy to support the commercialization of hydrogen fuel cell commercial vehicles.
Automotive E-Compressor Market Segment Analysis
-
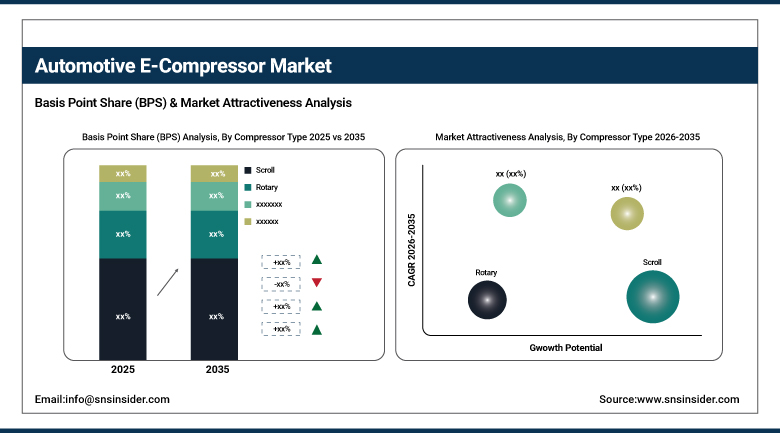
By Compressor Type, the Scroll segment dominated the Automotive E-Compressor Market with approximately 41.60% share in 2025, while the Rotary segment is the fastest growing with a CAGR of approximately 9.80%.
-
By Application, the Air-Conditioning Systems segment dominated the Automotive E-Compressor Market with approximately 46.73% share in 2025, while the Thermal Management Systems segment is the fastest growing with a CAGR of approximately 12.27%.
-
By Propulsion, the Battery Electric Vehicles segment dominated the Automotive E-Compressor Market with approximately 61.22% share in 2025, and is also the fastest growing with a CAGR of approximately 12.19%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive E-Compressor Market with approximately 58.74% share in 2025, while the Medium & Heavy Commercial Vehicles segment is the fastest growing with a CAGR of approximately 12.25%.
By Compressor Type, Scroll dominates and Rotary grows fastest
Scroll compressors are still regarded as the primary compressor type segment in the Automotive E-Compressor market due to their high volumetric efficiency and ability to offer continuous compression, which is desirable in the passenger vehicle HVAC systems. This segment features quiet operation and reduced number of mechanical parts compared to other compressor types, thus facilitating the widespread adoption of this segment as a key differential factor in the compact electric/hybrid vehicles market.
The rotary compressors segment has emerged as the fastest growing compressor type segment, targeting applications in compact vehicles that need an efficient space-saving cooling solution. This segment specializes in providing reliable performance at varying speeds through a mechanical design, making this compressor type a lucrative choice for the future.
By Application, Air-Conditioning Systems dominates and Thermal Management Systems grows fastest
Automotive E-Compressor Market owing to the key importance of e-compressors in ensuring the climate control of the passenger compartment in all electric and hybrid vehicles currently available in the market. The sector leverages the long experience of compressor engineering gained in the design and implementation of belt-driven compressors and re-engineered for electric use to meet customer demands with respect to passenger compartment climate control.
Thermal Management Systems are likely to be the fastest-growing application segments due to the vital importance of e-compressors in the temperature control of batteries, electric motors, and power electronics to enhance the performance and the driving range of vehicles. The segment is dedicated to integrated thermal management solutions combining cabin cooling with the temperature management of batteries and powertrain.
By Propulsion, Battery Electric Vehicles dominates and grows fastest
Battery Electric Vehicles remain both the dominant and fastest-growing propulsion segment within the Automotive E-Compressor Market, characterized by their complete reliance on electrically driven compressors since no engine-driven alternative exists on a pure electric powertrain. This segment benefits from continued global growth in battery electric vehicle production, which directly and proportionally drives e-compressor demand given the technology's essential role in every battery electric vehicle's climate control and thermal management systems.
This segment also focuses on advanced heat pump integration and R744 refrigerant-based systems that extend driving range by improving cold-weather heating efficiency, an increasingly important competitive differentiator as automakers work to address consumer range anxiety. As global battery electric vehicle production continues to scale across established and emerging automotive markets, this segment is positioned to sustain its leadership across both current market share and forward growth.
By Vehicle Type, Passenger Cars dominates and Medium & Heavy Commercial Vehicles grows fastest
Passenger Cars continue to dominate the vehicle type segment for the Automotive E-Compressor Market due to the huge number of global electric and hybrid passenger cars produced compared to the commercial vehicles segments. The segment is supported by carmakers who are continuously launching more electric and hybrid passenger car models, leading to consistent demand for e-compressors from various vehicles at different price points.
Medium & Heavy Commercial Vehicles are expected to be the fastest-growing vehicle type segment, spurred by increasing interest among fleet owners and manufacturers for electric and hybrid regional delivery trucks, buses, and other commercial vehicle types. The segment targets bigger capacity e-compressors, which can handle the larger cabin and cargo volume of the vehicles, enabling medium and heavy commercial vehicles to register disproportionate growth even with high payload and duty cycle demands compared to passenger vehicle applications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
58.60% |
|
North America |
United States |
81.50% |
|
Europe |
Germany |
27.80% |
|
Latin America |
Brazil |
45.60% |
|
Middle East & Africa |
Saudi Arabia |
31.20% |
Asia Pacific Automotive E-Compressor Market Insights
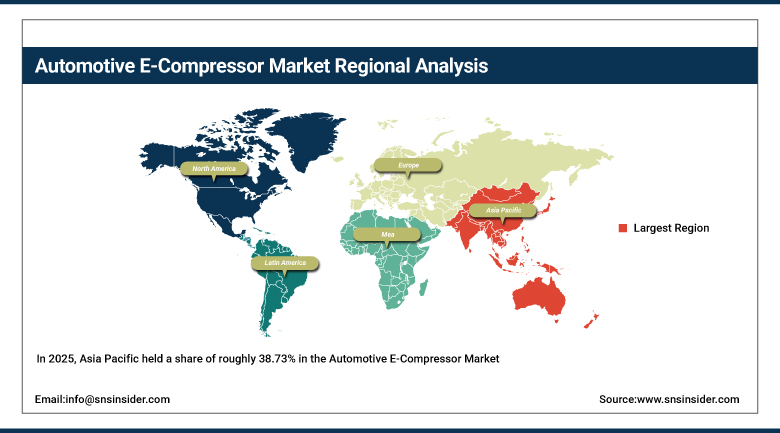
In 2025, Asia Pacific held a share of roughly 38.73% in the Automotive E-Compressor Market, owing to the fact that the region is the largest producer of electric vehicles worldwide. China is the largest producer among all the countries in the region, which is backed by its large-scale electric vehicle manufacturing system along with the abundant supply of thermal management components in the region.
Apart from that, Japan and South Korea are some of the significant contributors to the demand in the region because of their existing e-compressor producers having experience in the automotive thermal management systems for decades. Growth in electric vehicles production in India and Southeast Asian countries has further strengthened the manufacturing capabilities of the region.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa Automotive E-Compressor Market Insights
The Middle East & Africa region is projected to expand at the fastest CAGR of approximately 12.22% across the Automotive E-Compressor Market during the 2026-2035 forecast period, reflecting the region's comparatively low current adoption base and accelerating vehicle electrification initiatives in select Gulf Cooperation Council markets. Saudi Arabia accounts for the largest share of regional demand, supported by government-backed electric vehicle investment programs and growing domestic automotive assembly initiatives.
The United Arab Emirates and other Gulf Cooperation Council markets contribute additional regional growth, driven by rising consumer demand for electric and hybrid vehicles suited to the region's extreme climate conditions, where efficient cabin cooling directly affects vehicle range and driver comfort. South Africa continues to anchor automotive component demand on the African continent, supported by its more developed automotive assembly and export base.
North America Automotive E-Compressor Market Insights
The North American region constitutes an important market for automotive e-compressors owing to the rising production of electric and hybrid cars in the United States, and rising investment in the manufacture of thermal management components by auto makers. The US makes up for the lion’s share of regional demand, which can be attributed to both its production levels and increasing investments in the manufacture of electric compressor components.
The other North American countries – Canada and Mexico – constitute additional demand from the region on account of cross-country integration within the automotive value chain, with Canada furthering the case with recent investments in thermal management components manufacture. Domestic policies supporting electric vehicles and increasing commercial vehicle electrification activities will ensure sustained demand for e-compressor technology in the region.
MEA & Latin America Automotive E-Compressor Market Insights
Latin America's Automotive E-Compressor Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic vehicle assembly base and its role as a regional hub for automotive production. Gradual growth in domestic hybrid and electric vehicle adoption continues to support steady, if comparatively modest, regional market development.
Middle East & Africa's broader regional dynamics are detailed above given the region's status as the fastest-growing market; South Africa continues to anchor component demand on the African continent through its established automotive assembly and export operations, while Gulf Cooperation Council markets increasingly prioritize electric vehicle infrastructure investment suited to the region's climate conditions.
Market Dynamics
Growth Drivers: Vehicle Electrification and Advanced Thermal Management Requirements Fuel the Market Growth
Increasing production of electric and hybrid vehicles across the globe is seen as the key factor fueling the Automotive E-Compressor Market, since the use of an electric compressor is necessary for each battery electric vehicle due to the lack of an engine-driven one. While the demand for e-compressors from increased production of electric vehicles continues to foster market growth, the growth of global vehicle production growth is seen as relatively modest.
Increasing complexity of vehicle thermal management systems that involve coordination of climate control and battery and power electronics cooling is another important factor generating demand for automotive e-compressors as car manufacturers aim to enhance driving range and performance. The increasing popularity of the use of e-compressors in medium and heavy commercial vehicle electrification initiatives is another important factor fueling the market.
Restraints: Higher Component Costs and Battery Range Trade-offs Hamper Market Expansion
The higher unit cost of electrically driven compressors relative to conventional belt-driven alternatives represents a significant restraint on the Automotive E-Compressor Market, as automakers balance thermal management performance against overall vehicle cost targets, particularly in more price-sensitive vehicle segments. This dynamic is compounded by the additional electrical load e-compressors place on vehicle battery systems, which can meaningfully reduce driving range if not carefully managed through efficient system design.
Medium and heavy commercial vehicle applications face particular restraint from higher payload requirements and demanding duty cycles that increase the technical complexity and cost of e-compressor integration relative to passenger vehicle applications. Continued raw material and semiconductor component cost volatility adds further uncertainty to long-term manufacturing cost planning across the broader thermal management supply chain.
Opportunities: Heat Pump Integration and Commercial Vehicle Electrification Create Growth Opportunities
The higher cost per unit of electric motors compared to traditional belt-driven motors is a major constraint for the Automotive E-Compressor Market as car manufacturers consider the impact of thermal management performance vis-à-vis vehicle cost, especially when the vehicles are from price-sensitive categories.
There will be additional constraints for medium and heavy commercial vehicles because of the higher payloads and the complexity involved due to the nature of their operations when compared with those in passenger vehicles.
In addition to this, there is an electrical load that is placed by e-compressors, which reduces the distance that can be traveled by the car depending on how efficiently the system has been designed.
Recent Developments:
-
In September 2023, Brose unveiled an 800-volt climate compressor enabling rapid vehicle charging in under 30 minutes, introducing the high-voltage variant first in China and establishing a new performance standard for thermal management systems supporting fast-charging electric vehicle architectures.
-
In August 2023, Valeo presented its REVO-E-HP R744 electric compressor at Busworld 2023, showcasing an R744 refrigerant-based heat pump compressor solution designed to improve thermal management efficiency and extend driving range for electrified commercial bus platforms.
-
In February 2024, Hanon Systems opened a new engineering center at its compressor manufacturing campus in Palmela, Portugal, supporting the plant's role as the company's European flagship facility for electric scroll compressor production and testing.
Automotive E-Compressor Market Key Players
-
Denso Corporation
-
Hanon Systems
-
Valeo S.A.
-
MAHLE GmbH
-
Sanden Holdings Corporation
-
Toyota Industries Corporation
-
Panasonic Corporation
-
Halla Mechatronics Corporation
-
BorgWarner Inc.
-
Bitzer Kühlmaschinenbau GmbH
-
LG Electronics Inc.
-
Guangzhou Highly Group Co., Ltd.
-
Zhejiang Sanhua Automotive Co., Ltd.
-
Shanghai Baolong Automotive Corporation
-
Aisin Corporation
-
Continental AG
-
Marelli Corporation
-
Subros Limited
-
Robert Bosch GmbH
-
Brose Fahrzeugteile SE & Co. KG
Automotive E-Compressor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.35 Billion |
| Market Size by 2035 | USD 11.08 Billion |
| CAGR | CAGR of 12.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Compressor Type (Scroll, Rotary, and Piston) • by Application (Air-Conditioning Systems, Thermal Management Systems, and Refrigeration Systems) • by Propulsion (Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, and Hybrid Electric Vehicles) • by Vehicle Type (Passenger Cars, Light Commercial Vehicles, and Medium & Heavy Commercial Vehicles) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Denso Corporation, Hanon Systems, Valeo S.A., MAHLE GmbH, Sanden Holdings Corporation, Toyota Industries Corporation, Panasonic Corporation, Halla Mechatronics Corporation, BorgWarner Inc., Bitzer Kühlmaschinenbau GmbH, LG Electronics Inc., Guangzhou Highly Group Co., Ltd., Zhejiang Sanhua Automotive Co., Ltd., Shanghai Baolong Automotive Corporation, Aisin Corporation, Continental AG, Marelli Corporation, Subros Limited, Robert Bosch GmbH, Brose Fahrzeugteile SE & Co. KG |
Frequently Asked Questions
Leading companies in the Automotive E-Compressor Market include Denso Corporation, Hanon Systems, Valeo, MAHLE, and Sanden Holdings, among others.
Key opportunities include continued advancement of heat pump-based thermal management systems using R744 refrigerant to extend electric vehicle driving range, and growing electrification of medium and heavy commercial vehicle platforms.
Accelerating global electric and hybrid vehicle production, combined with growing sophistication of vehicle thermal management systems coordinating cabin and battery cooling, is the major factor driving market growth.
The Battery Electric Vehicles segment dominated the Automotive E-Compressor Market with approximately 61.22% share in 2025.
Asia Pacific dominated the Automotive E-Compressor Market in 2025 with approximately 38.73% share, underpinned by the region's position as the world's largest electric vehicle production base, led by China.
