
Automotive Fasteners Market Report Scope & Overview:
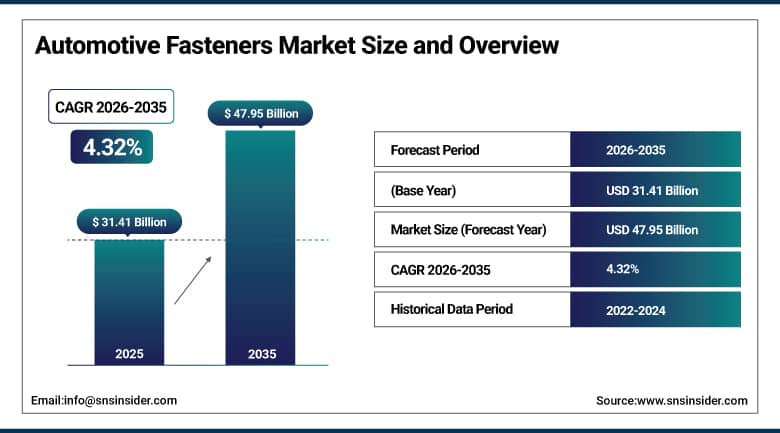
The Automotive Fasteners Market was valued at USD 31.41 Billion in 2025 and is expected to reach USD 47.95 Billion by 2035, growing at a CAGR of 4.32% from 2026-2035.
The Automotive Fasteners Market consists of bolts, nuts, screws, clips, and rivets used for securing parts and assemblies in automobiles, retaining their low cost but necessity in being critical due to the large number of fastening points found in contemporary automobiles in their engine, chassis, interior, and electrical and electronics assemblies. The booming vehicle industry around the world, along with growing number of automobile production units and the necessity of fastening in every single assembly operation in the automobile industry, keeps this demand stable, although fastener types and materials required continue to change. There is a noticeable trend in leading companies in the market to move away from using common fasteners towards custom fasteners designed for use in specific automobile models.
In March 2025, Fontana Gruppo purchased a controlling interest in India’s Right Tight Fasteners, thus enhancing its position in the market of automotive fasteners as well as increasing its production facilities in Asia. The transaction supports Fontana Gruppo’s strategy to broaden its product portfolio and enhance its position in the automotive fasteners sector, particularly across India’s growing automotive manufacturing ecosystem.
To Get More Information On Automotive Fasteners Market - Request Free Sample Report
Automotive Fasteners Market Trends
- Rising adoption of mixed-material vehicle architectures continues to drive demand for adhesive-fastener hybrid joining solutions.
- EV production growth is increasing demand for specialized fasteners used in battery systems and electrical assemblies.
- Non-threaded fasteners including clips and rivets continue gaining share as mixed-material vehicle designs expand.
- Aftermarket fastener demand continues to grow as rising vehicle age and right-to-repair regulation support replacement part sales.
- Additive manufacturing and 3D printing technologies continue to advance customized, application-specific fastener production capability.
U.S. Automotive Fasteners Market Outlook
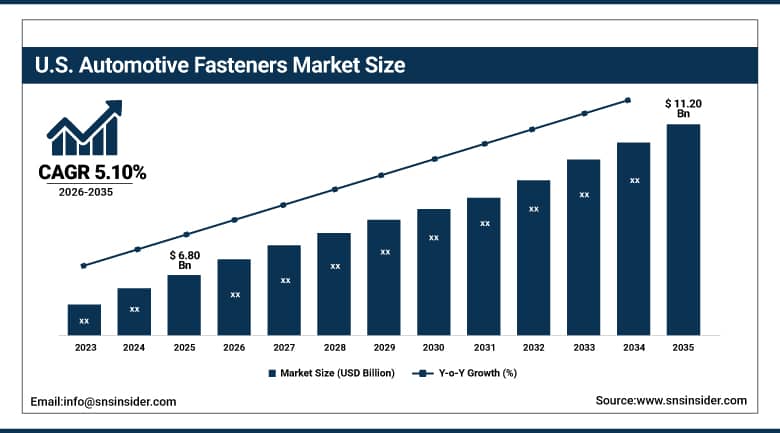
The U.S. automotive fasteners market was valued at approximately USD 6.80 Billion in 2025 and is expected to reach approximately USD 11.20 Billion by 2035, growing at a CAGR of approximately 5.10%.
The U.S. automotive fasteners market grows from the reshoring trend of automotive manufacturing in local facilities, along with high production volumes of electric cars which require unique fastening components for batteries and electronic modules assembly. Such fastener needs significantly vary from those required by internal combustion engine vehicles. At the same time, old cars and regular need in maintenance create a consistent demand for replacement fasteners. The legislative measures which advocate for right-to-repair and better availability of spare parts only reinforce such trends for the local automotive service industry. Investments in automotive manufacturing, batteries production, and automotive technologies will drive the demand for unique fastener products.
In 2025, Bosch announced its operating margin at 1.9%. This emphasizes the cost pressure challenges that are prevailing in the automotive value chain. The annual cost reductions targets set by car manufacturers between 1% to 4% or more are prompting American fastener manufacturers to automate, improve their manufacturing efficiency, and engineer solutions for fastening.
Automotive Fasteners Market Segment Analysis
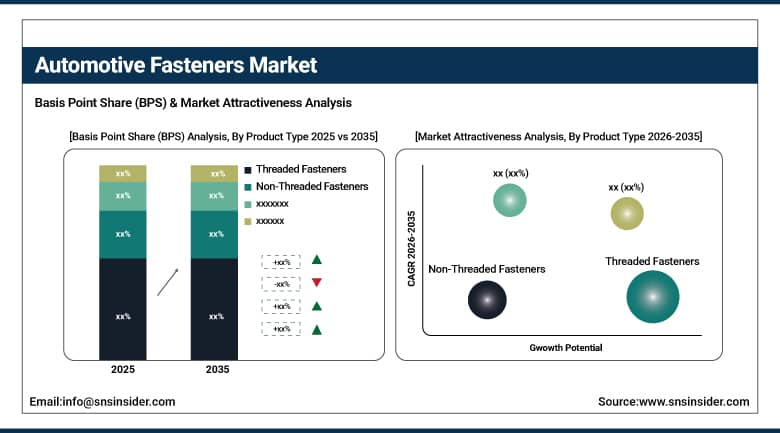
- By Product Type, the threaded fasteners segment dominated the automotive fasteners market with approximately 67.00% share in 2025, while the non-threaded fasteners segment is the fastest growing with a CAGR of approximately 6.20%.
- By Material, the metal segment dominated the automotive fasteners market with approximately 52.30% share in 2025, while the plastic/composite segment is the fastest growing with a CAGR of approximately 6.80%.
- By Distribution Channel, the OEM segment dominated the automotive fasteners market with approximately 87.83% share in 2025, while the aftermarket segment is the fastest growing with a CAGR of approximately 6.40%.
- By Vehicle Type, the passenger cars segment dominated the automotive fasteners market with approximately 72.00% share in 2025, while commercial vehicles is the fastest-growing vehicle type segment with a CAGR of approximately 4.50% from 2026–2035.
- By Propulsion Type, the internal combustion engine vehicles segment dominated the automotive fasteners market with approximately 75.00% share in 2025, while battery electric vehicles is the fastest-growing propulsion segment with a CAGR of approximately 4.66% from 2026–2035.
By Product Type, threaded fasteners dominates, non-threaded fasteners grows fastest
Threaded fasteners dominated the product type segment in 2025, encompassing the bolts and nuts frequently inserted into a hole and secured mechanically that remain the default choice across the large majority of structural and powertrain fastening applications given their proven reliability and reusability. Continued refinement of thread-locking and torque-retention technology keeps this fastener category the default engineering choice across nearly every powertrain and chassis assembly application worldwide.
Non-threaded fasteners are the fastest-growing product type segment, driven by increasing use of mixed-material vehicle designs where clips, rivets, and industrial adhesives are widely adopted to join dissimilar materials that threaded fasteners alone cannot reliably or efficiently connect. Since battery packs need thin and light-weight enclosures, their assembly increases the use of non-threaded fasteners due to the fact that clips and rivets go well with such enclosures.
By Material, metal dominates, plastic/composite grows fastest
Metal dominated the material segment in 2025, given its proven structural strength and reliability across engine, chassis, and safety-critical fastening applications where mechanical load-bearing performance cannot be compromised regardless of weight or cost considerations. Safety-critical structural components including chassis mounts and suspension assemblies continue to specify metal fasteners almost exclusively, given the fatigue resistance and load-bearing consistency these applications demand.
Plastics and composites are the most rapidly expanding material segment because of the increasing usage of plastics and composites within car interiors and electronics due to the efforts of auto manufacturers to make their cars lighter for better mileage and increased electric car range. Another factor that is contributing to this high level of growth in the segment is the increasing emphasis on sustainability from auto manufacturers.
By Distribution Channel, OEM dominates, aftermarket grows fastest
The OEM distribution channel ruled the roost when it came to the distribution channels segment, because the original equipment manufacturers demand a consistent flow of fasteners incorporated into the vehicle assembly line. Such is the dominant position held by the OEM distribution channel in the entire automotive fastener supply chain. The long-term contracts between fastener producers and major automobile producers will further solidify the OEM distribution channel position.
Aftermarket is the fastest-growing distribution channel segment, as rising vehicle age and frequent maintenance cycles drive steady demand for replacement fasteners including clips, screws, and underbody components, reinforced by regulatory frameworks increasingly supporting right-to-repair access. Growing independent repair shop network expansion continues to reinforce aftermarket channel growth, supported by improving parts distribution logistics across most major markets.
By Vehicle Type, passenger cars dominates, commercial vehicles grows fastest
Passenger Cars was the major segment of the fasteners market in the automotive industry in 2025. The high number of passenger car productions globally and the widespread application of fasteners in vehicle body construction, chassis, interior, engine, and electronic components have helped this segment to be the leader. Additionally, growing vehicle complexity is fueling demand for fasteners with high strength and lightweight characteristics. Continued adoption of advanced safety and electronic technologies is further expanding fastening requirements.
The commercial vehicles segment is projected to register the fastest growth in the automotive fasteners market. The increasing demand for trucks, buses, delivery trucks, and fleets has led to increased demand for durable fastening products. Commercial vehicles need durable fasteners that can withstand high pressure, vibrations, and challenging environments. The development of infrastructure, logistics, e-commerce, and modernization of fleet have also increased the demand for automotive fasteners.
By Propulsion Type, internal combustion engine vehicles dominates, battery electric vehicles grows fastest
The internal combustion engine vehicles segment dominated the automotive fasteners market in 2025. The category is aided by the massive number of ICE vehicles in use and production across the world. ICE vehicles have many fastening needs, in their engines, transmissions, exhaust systems, chassis, and bodies. Manufacturing operations, aftermarkets, and vehicle maintenance needs are driving the demand for traditional metal fasteners in the global automotive value chain.
The segment of battery electric vehicles is expected to witness highest growth rate within the propulsion segment from 2026-2035. High volume of EV production and increased incorporation of battery systems are generating the need for fasteners that can be used in the manufacture of batteries, thermal management system, electrical modules, and lightweight body parts. Corrosion resistance, electrical compatibility, light weight, and high strength are some key characteristics needed in the fasteners used in the manufacturing of electric vehicles.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
48.60% |
|
North America |
United States |
77.40% |
|
Europe |
Germany |
29.20% |
|
Latin America |
Brazil |
31.60% |
|
Middle East & Africa |
Saudi Arabia |
21.30% |
Asia Pacific Automotive Fasteners Market Insights
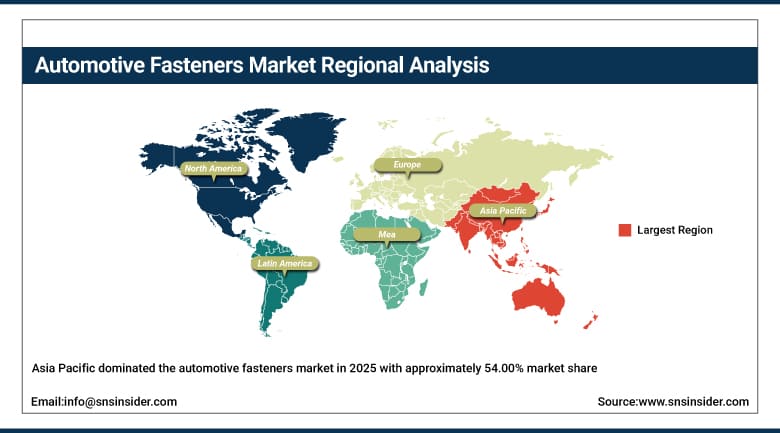
Asia Pacific dominated the automotive fasteners market in 2025 with approximately 54.00% market share, supported by expanding vehicle production across China and India and a massive domestic automotive component manufacturing base serving both regional and export markets. Government-backed automotive manufacturing investment across the region continues to expand domestic fastener production capacity ahead of what private investment alone would support.
Demand in the region is anchored by China, which is the world leader in production capacity for automobiles, and by India, whose growing automobile manufacturing industry creates incremental demand. Japan and South Korea continue contributing advanced fastener engineering technology supporting the broader regional supplier base. Southeast Asian markets including Thailand and Indonesia continue expanding domestic automotive component manufacturing capacity to serve both regional and export vehicle production.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Fasteners Market Insights
North America is the fastest-growing region in the automotive fasteners market, expanding at a CAGR of approximately 5.60% over the forecast period, driven by re-shoring trends bringing automotive manufacturing back to domestic facilities and strong electric vehicle production growth requiring specialized fastening solutions. Growing domestic battery and electric vehicle component manufacturing investment continues to reinforce this reshoring trend beyond simple final assembly relocation alone.
The United States accounts for the substantial majority of regional demand, with suppliers increasingly investing in automation to meet demanding automaker cost-reduction targets. The manufacture of automotive parts in Canada and Mexico is expanding together with vehicle production in North America. The manufacture of automotive parts in Mexico is expanding together with the vehicle production integration in North America.
Europe Automotive Fasteners Market Insights
Europe represents a mature, technologically advanced automotive fasteners market, with Germany leading regional demand through its large premium automotive manufacturing base and strong domestic fastener engineering and supply chain infrastructure. Growing European automaker investment in vehicle electrification programs continues to reinforce demand for lightweight, specialized battery and electrical system fasteners.
France and Italy contribute additional demand, both markets favoring advanced, lightweight fastening solutions supporting regional vehicle electrification programs. Growing multi-material vehicle architecture adoption continues to reinforce demand for adhesive-fastener hybrid joining technology across the region. Eastern European component manufacturers continue expanding production capacity to serve growing regional automotive supply chain demand.
MEA & Latin America Automotive Fasteners Market Insights
The Middle East and Africa represent a smaller but growing market, with Saudi Arabia driving regional demand through expanding domestic automotive assembly capacity tied to broader economic diversification initiatives. Growing regional automotive assembly investment continues to expand the addressable market for fastener suppliers across Gulf state markets.
Latin America is a growing market led by Brazil, where an expanding domestic vehicle production sector continues to drive automotive fastener demand. Mexico contributes meaningful secondary demand through its large automotive export manufacturing sector serving North American vehicle platforms. Argentine and Colombian automotive component manufacturers continue to gradually expand production capacity as regional vehicle production grows.
Market Dynamics
Growth Drivers: Rising vehicle production and electrification fueling fastener demand
Increasing production of vehicles around the world, in conjunction with an increase in electronics in current vehicles, still plays a major role in the automotive fastener demand, since the number of fasteners for one new vehicle platform is very high. Vehicle complexity, especially in terms of advanced driver assistance systems and infotainment systems, is causing the electronic module fasteners per vehicle to increase to a historical level.
Rising electric vehicle production continues to expand demand for specialized fasteners supporting battery systems, electrical module assemblies, and lightweight multi-material vehicle architectures that differ meaningfully from conventional internal combustion vehicle fastening requirements.
Restraints: Margin pressure and supply chain disruption limiting supplier profitability
Persistent automaker cost-reduction expectations, typically ranging between 1% and 4% annually or higher, continue to compress supplier margins across the automotive supply ecosystem, forcing fastener manufacturers to invest heavily in automation and efficiency to maintain profitability. Fastener manufacturers increasingly negotiate multi-year pricing agreements specifically to provide some insulation against this persistent annual cost-reduction pressure.
Global sourcing disruptions and supply chain volatility continue to complicate fastener procurement planning for both suppliers and automakers, particularly for specialized, application-specific fasteners requiring long-lead-time tooling and qualification processes.
Opportunities: Customized fastening solutions and additive manufacturing widening demand
Growing automaker shift away from standard, off-the-shelf fasteners toward customized fastening solutions engineered for specific vehicle platforms presents a significant opportunity for suppliers capable of differentiating through engineering expertise rather than competing purely on commodity pricing. Suppliers that build genuine engineering design collaboration relationships with automakers early in vehicle platform development stand to capture more durable, higher-margin program business than commodity suppliers competing purely on unit price.
Advancement of additive manufacturing and 3D printing technology presents a substantial opportunity for fastener producers to develop increasingly customized, application-specific products, particularly for low-volume or highly specialized vehicle platforms where traditional manufacturing setup costs would otherwise be prohibitive.
Recent Developments:
- 2025: Jaguar expanded its aluminum body architecture, increasing adhesive bonding length by 50% to 154 meters alongside the use of 2,840 rivets to join dissimilar vehicle materials.
- 2024: ITW Automotive expanded its engineered fastening solutions portfolio, targeting automakers seeking customized, application-specific fasteners for electric vehicle battery and structural applications.
- 2024: LISI GROUP announced expanded manufacturing capacity for lightweight, corrosion-resistant fasteners supporting multi-material vehicle architecture and EV battery system assembly.
- 2023: Wurth Group expanded its automotive fastener distribution network, targeting both OEM production line customers and growing aftermarket replacement demand.
Automotive Fasteners Market Key Players are:
- Illinois Tool Works Inc. (ITW Automotive)
- Stanley Black & Decker, Inc.
- LISI GROUP
- Wurth Group
- SFS Group
- Nifco Inc.
- Sundram Fasteners Ltd.
- Phillips Screw Co.
- Rocknel Fastener Inc.
- Bulten AB
- Kamax Holding GmbH & Co. KG
- Fontana Group
- Arconic Corporation
- Nedschroef Holding B.V.
- Precision Castparts Corp. (Berkshire Hathaway)
- Shanghai Prime Machinery Co., Ltd.
- MEIDOH Co., Ltd.
- Bollhoff Group
- Marina Fasteners, Inc.
- Acument Global Technologies
Automotive Fasteners Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 31.41 Billion |
| Market Size by 2035 | USD 47.95 Billion |
| CAGR | CAGR of 4.32% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Threaded Fasteners, Non-Threaded Fasteners, Specialty/Safety-Critical) • By Material (Metal, Plastic/Composite, Hybrid) • By Distribution Channel (OEM, Aftermarket) • By Vehicle Type (Passenger Cars, Commercial Vehicles) • By Propulsion Type (Internal Combustion Engine Vehicles, Hybrid Electric Vehicles, Battery Electric Vehicles, Fuel Cell Electric Vehicles) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Illinois Tool Works Inc. (ITW Automotive), Stanley Black & Decker, Inc., LISI GROUP, Wurth Group, SFS Group, Nifco Inc., Sundram Fasteners Ltd., Phillips Screw Co., Rocknel Fastener Inc., Bulten AB, Kamax Holding GmbH & Co. KG, Fontana Group, Arconic Corporation, Nedschroef Holding B.V., Precision Castparts Corp. (Berkshire Hathaway), Shanghai Prime Machinery Co., Ltd., MEIDOH Co., Ltd., Bollhoff Group, Marina Fasteners, Inc., Acument Global Technologies |
Frequently Asked Questions
Key players in the Automotive Fasteners Market include Illinois Tool Works Inc. (ITW Automotive), Stanley Black & Decker, Inc., LISI GROUP, Wurth Group, and SFS Group, among others.
Key opportunities include growing automaker shift toward customized fastening solutions engineered for specific vehicle platforms, and advancement of additive manufacturing technology enabling application-specific fastener production.
The market is driven by increased global vehicle production and growing electronics content in vehicles, alongside rising electric vehicle production requiring specialized battery and electrical assembly fasteners.
The Threaded Fasteners segment dominated the Automotive Fasteners Market, accounting for approximately 67.00% market share.
Asia Pacific dominated the Automotive Fasteners Market in 2025 with approximately 54.00% share, supported by expanding vehicle production across China and India.
