
Automotive Heat Shield Market Report Scope & Overview:
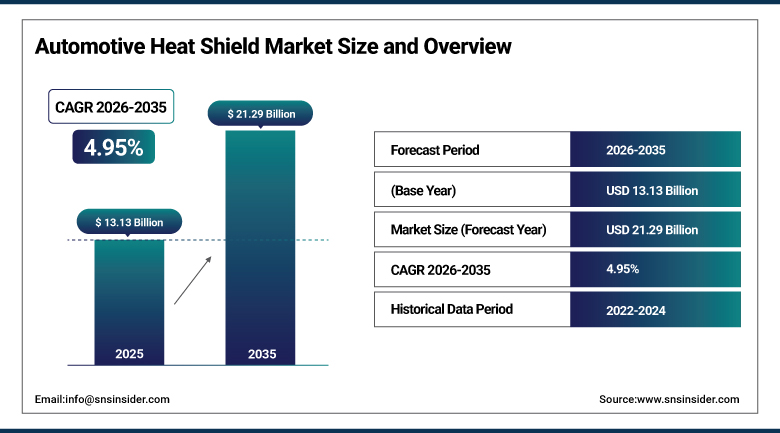
The Automotive Heat Shield Market was valued at USD 13.13 Billion in 2025 and is expected to reach USD 21.29 Billion by 2035, growing at a CAGR of 4.95% from 2026-2035.
The Automotive Heat Shield Market growth is fueled mainly by an increase in the demand for thermal management due to the rise in adoption of forced induction engine technology in automobiles, both gasoline and diesel, leading to the rise in demand for heat shields that ensure heat resistance and provide protection to other parts. The growing demand for heat shield material is directed toward lightweight, low-density, and high-temperature heat-resistant material that does not add extra weight to the car. Simultaneously, the development in the trend of electric vehicles is creating thermal management needs associated with battery, power electronics, and charging system, and heat shields are being utilized to control heat dissipation.
The improvements in heat shield insulation to improve heat resistance and strict regulations on fuel economy and emissions will help to sustain the growth of the automotive heat shield market.
CERTINA completed its acquisition of ElringKlinger's Heat and Noise Shielding facilities in Switzerland and the United States, following a year of detailed discussions and a three-month post-signing transition period.
To Get more information Automotive Heat Shield Market - Request Free Sample Report
Automotive Heat Shield Market Trends
- Growing adoption of lightweight, multilayer heat shield designs to reduce vehicle weight without compromising protection.
- Rising demand for battery and power-electronics thermal protection across electric and hybrid vehicle platforms.
- Continued expansion of turbocharger-specific heat shielding as forced-induction engine adoption increases.
- Increasing supplier investment in composite and non-metallic heat shield materials for space-constrained designs.
- Growing industry consolidation as suppliers combine complementary thermal management manufacturing capabilities.
U.S. Automotive Heat Shield Market Outlook
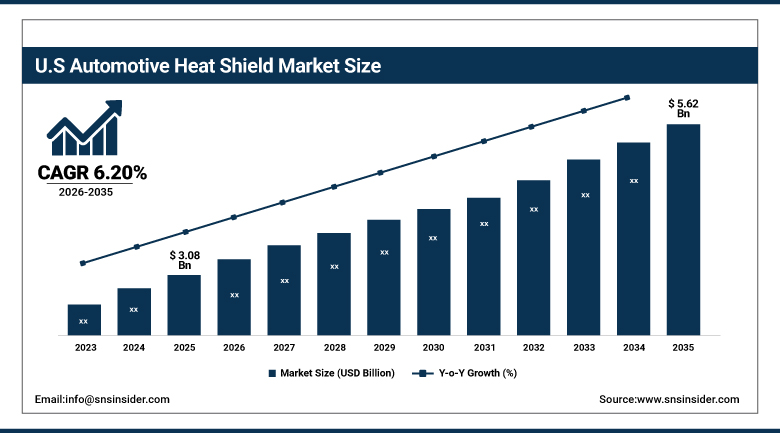
The U.S. Automotive Heat Shield Market was valued at USD 3.08 Billion in 2025 and is expected to reach USD 5.62 Billion by 2035, growing at a CAGR of 6.20% from 2026-2035.
The growth in the U.S. Automotive Heat Shield market will keep getting further boosted by an increasing number of domestic automobile productions largely attributed to light trucks, domestic production of electric and hybrid automobiles necessitating battery heat protection, and the developments in lightweight materials and manufacturing technologies that have improved the performance of heat shields. Demand from domestic markets is also aided by the presence of numerous suppliers of heat shield and thermal management products who happen to be located within the country, and who continue to grow their EV-oriented range of products.
In 2024, Tenneco introduced a new generation of ultra-lightweight, high-performance heat shields designed specifically for electric vehicle battery packs, targeting improved thermal protection and reduced vehicle weight.
Automotive Heat Shield Market Segment Analysis
- By Material, the Metallic segment dominated the Automotive Heat Shield Market with approximately 86.00% share in 2025, while the Non-Metallic segment is the fastest growing with a CAGR of approximately 6.20%.
- By Component, the Engine Compartment segment dominated the Automotive Heat Shield Market with approximately 79.00% share in 2025, while the Turbocharger segment is the fastest growing with a CAGR of approximately 6.13%.
- By Vehicle Propulsion, the ICE segment dominated the Automotive Heat Shield Market with approximately 88.95% share in 2025, while the Battery Electric segment is the fastest growing with a CAGR of approximately 13.72%.
- By Vehicle Type, the Passenger Cars segment dominated the Automotive Heat Shield Market with approximately 54.50% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 4.72%.
By Material, Metallic dominates and Non-Metallic grows fastest
The metallic heat shields represent the overwhelming leader material segment in the Automotive Heat Shields market, thanks to their well-known durability, heat-resistance, and existing manufacturing technology infrastructure, based on stamping and shaping processes of aluminum and stainless steel. The segment is well-established due to the decades-long experience in producing stamped and formed metal heat shields.
The non-metallic heat shields, including composites and multi-layer laminates, represent the fastest-growing material segment of the Automotive Heat Shield market, as car manufacturers aim to reduce the weight of their vehicles and require a flexible design of heat shields, suitable for the tight geometry of electric cars. The material segment is focused on developing advanced insulation materials, which can withstand the constant high temperature, as well as conform to the complicated geometry of battery and power electronics enclosures.
By Component, Engine Compartment dominates and Turbocharger grows fastest
Engine Compartment shields remain the dominant component segment within the Automotive Heat Shield Market, reflecting the broad-based need to protect surrounding wiring, plastic components, and structural elements from heat generated by the engine and adjacent systems. This segment benefits from consistent, high-volume specification across virtually every internal combustion and hybrid vehicle produced, given the fundamental thermal protection requirements of the engine bay environment.
Turbocharger shields are emerging as the fastest-growing component segment, driven by increasing adoption of forced-induction engines across both gasoline and diesel vehicle platforms seeking to improve fuel efficiency and power output. This segment focuses on high-temperature-resistant designs capable of withstanding the extreme heat generated by turbocharger housings, positioning turbocharger-specific shielding to capture growing demand as automakers continue downsizing engines while maintaining performance through forced induction.
By Vehicle Propulsion, ICE dominates and Battery Electric grows fastest
Internal combustion engine-based vehicles constitute the dominant segment in the automotive heat shields market, owing to the requirement of maintaining the temperature of the catalytic substrate at an optimal level for conversion of emissions without allowing any scorching of the nearby parts. The internal combustion engine vehicle-based segment is a mature one, owing to years of expertise in designing of heat shields in relation to the exhaust and engine compartment of internal combustion engines.
Battery electric vehicles represent the fastest-growing segment in the automotive heat shield market, primarily on account of the crucial need to protect the traction batteries, inverters, and DC-DC converter from overheating, especially while doing fast DC charging. The battery electric segment consists of flexible ceramic papers, intumescent foams, and copper mesh spreaders to shift hot spots from the battery cells.
By Vehicle Type, Passenger Cars dominates and Commercial Vehicles grows fastest
Passenger Cars remain the dominant vehicle type segment within the Automotive Heat Shield Market, reflecting the sheer scale of global passenger vehicle production relative to commercial vehicle segments. This segment benefits from consistent heat shield content across sedans, SUVs, and crossover models, with multiple shield locations per vehicle further reinforcing demand density.
Commercial Vehicles are emerging as the fastest-growing vehicle type segment, driven by growing heavy commercial vehicle production and the more demanding thermal protection requirements associated with larger engines, extended duty cycles, and higher exhaust system temperatures in trucks and buses. This segment focuses on heavier-duty, more durable heat shield designs suited to the extended service life and demanding operating conditions of commercial vehicle applications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
54.60% |
|
North America |
United States |
87.50% |
|
Europe |
Germany |
32.80% |
|
Latin America |
Brazil |
45.60% |
|
Middle East & Africa |
United Arab Emirates |
29.80% |
Asia Pacific Automotive Heat Shield Market Insights
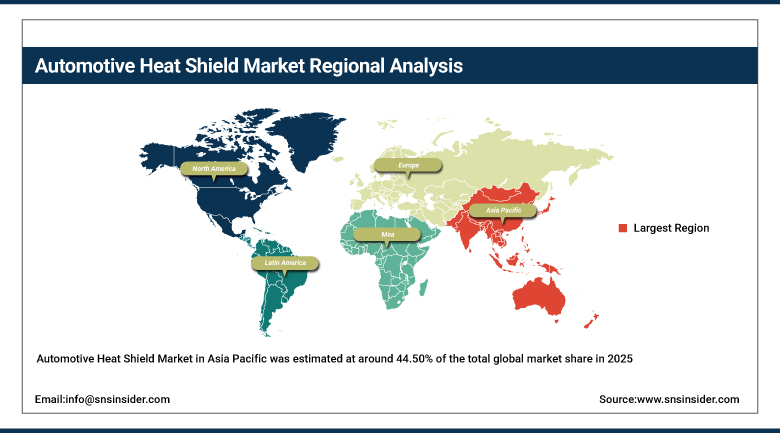
The Automotive Heat Shield Market in Asia Pacific was estimated at around 44.50% of the total global market share in 2025 owing to increasing automotive manufacturing activities in emerging nations like India, China, and Japan. China emerges as the largest single market in Asia Pacific, owing to extensive production of vehicles along with increased interest in investing in heat shield products due to efficiency considerations and compliance issues.
Apart from China, India and Japan too add value to this segment through the growth in manufacture and sale of commercial and passenger vehicles which have increased demands for heat shield to protect their parts against high-temperature emissions from the exhaust system of the vehicle. Increased production of hybrid and electric vehicles in Asia Pacific adds to this growth, especially in China.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Heat Shield Market Insights
North America is projected to expand at the fastest CAGR of approximately 6.20% across the Automotive Heat Shield Market during the 2026-2035 forecast period, driven by growth in vehicle production led primarily by light trucks and continued expansion of domestic electric vehicle manufacturing. The United States accounts for the substantial majority of regional demand, reflecting both its vehicle production scale and its concentration of leading heat shield and thermal management suppliers.
Canada and Mexico contribute additional regional volume through cross-border automotive supply chain integration linked to broader North American vehicle assembly. Continued advancements in lightweight materials and manufacturing processes, combined with rising demand for battery and power-electronics thermal protection, further reinforce North America's position as the fastest-growing regional market for automotive heat shields.
Europe Automotive Heat Shield Market Insights
Europe is a substantial regional market for heat shields in the automotive industry owing to its significant base of automobile manufacturers, which includes some high-end car manufacturers needing sophisticated thermal management systems. The German share in the European market is an indication of the German market's dominance of regional car manufacturing and the presence of top heat shield and thermal management suppliers in the country.
France and UK are other countries contributing to the regional demand due to their strong bases of automobile manufacturing. The increasing adoption of electrification and turbochargers along with stringent emission and fuel-efficiency standards in Europe are fueling the need for thermal management systems.
MEA & Latin America Automotive Heat Shield Market Insights
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where rising vehicle imports and growing automotive assembly initiatives are gradually increasing component demand. South Africa continues to anchor heat shield-related demand on the African continent, supported by its comparatively more developed automotive assembly and export base.
Latin America's Automotive Heat Shield Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic vehicle assembly base and its role as a regional export hub for automakers operating in the region. Gradual growth in domestic vehicle production continues to support steady regional demand growth.
Market Dynamics
Growth Drivers: Forced-Induction Engines and Vehicle Electrification
The rise in usage of turbochargers in internal combustion engine automobiles is seen as one of the main reasons for the growth in the Automotive Heat Shield Market, as the temperature generated in these types of engines with forced induction technology becomes much more localized and hence requires heat shields to avoid damage to nearby components. This trend is augmented by the strategy of engine downsizing adopted by automobile manufacturers through the use of forced induction or turbochargers.
The increased use of plug-in hybrid and electric cars also serves as an important demand driver for the market, as both these types of cars require heat shields not just for their engines but also for other components such as their batteries, inverters, and chargers.
Restraints: Higher Costs and Integration Complexity in Electric Vehicle Architectures
The higher cost and technical sophistication of complex multilayer and composite heat shields are seen as major constraints in the Automotive Heat Shield Market, considering that the engineering and manufacturing of the products are relatively complicated compared to simple metal single-shell shields. This challenge is especially pertinent to the need for thermal management of batteries, which requires specific ceramic paper and intumescent foam materials.
Constraints related to integration within novel automobile systems and limited space available in electric vehicles prevent any accelerated development of standardized designs, where suppliers have to design custom fit heat shields for ever-smaller and more complex battery and electronics packaging. Volatility in the cost of metals such as aluminum and steel continues to create uncertainties in cost forecasting for manufacturing.
Opportunities: Battery Thermal Protection and Lightweight Material Innovation
Continued growth in battery electric vehicle production presents a substantial growth opportunity for the Automotive Heat Shield Market, as these vehicles require specialized thermal protection for traction batteries, inverters, and DC-DC converters that did not exist in conventional internal combustion vehicle architectures. Suppliers that can demonstrate validated, cost-competitive battery thermal protection solutions are well positioned to capture share as global electric vehicle production continues to accelerate.
Rising demand for lightweight, non-metallic heat shield materials presents a longer-term opportunity for suppliers to extend their product portfolios beyond conventional metallic designs into advanced composite and multilayer laminate solutions. As automakers continue pursuing vehicle weight reduction to offset battery mass in electric vehicles, suppliers with established lightweight material engineering capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2026: ElringKlinger highlighted its role in New Energy Vehicle programs at Auto China 2026, showcasing thermal-management sealing solutions and battery cell contacting systems, reflecting increasing supplier focus on electrified-vehicle thermal protection.
- 2026: Dana reaffirmed its 2026 business outlook and highlighted new business opportunities associated with next-generation vehicle platforms, supporting continued development of advanced thermal-management and heat-shielding solutions.
Automotive Heat Shield Market Key Players are:
- Tenneco Inc.
- Dana Incorporated
- ElringKlinger AG
- Autoneum Holding AG
- Alkegen
- Sumitomo Riko Co., Ltd.
- Lydall, Inc.
- Morgan Advanced Materials plc
- Zircotec Ltd.
- DuPont de Nemours, Inc.
- 3M Company
- Carcoustics International GmbH
- MAHLE GmbH
- Hutchinson SA
- Boyd Corporation
- Nichias Corporation
- Talbros Automotive Components Ltd.
- Happich GmbH
- Heatshield Products, Inc.
- Thermo-Tec Automotive Products, Inc.
Automotive Heat Shield Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.13 Billion |
| Market Size by 2035 | USD 21.29 Billion |
| CAGR | CAGR of 4.95% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Metallic and Non-Metallic) • By Component (Engine Compartment, Exhaust System, Turbocharger, and Others) • By Vehicle Propulsion (ICE, Hybrid, and Battery Electric) • By Vehicle Type (Passenger Cars and Commercial Vehicles) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tenneco Inc.; Dana Incorporated; ElringKlinger AG; Autoneum Holding AG; Alkegen; Sumitomo Riko Co., Ltd.; Lydall, Inc.; Morgan Advanced Materials plc; Zircotec Ltd.; DuPont de Nemours, Inc.; 3M Company; Carcoustics International GmbH; MAHLE GmbH; Hutchinson SA; Boyd Corporation; Nichias Corporation; Talbros Automotive Components Ltd.; Happich GmbH; Heatshield Products, Inc.; Thermo-Tec Automotive Products, Inc. |
Frequently Asked Questions
Leading companies in the Automotive Heat Shield Market include Tenneco, Dana Incorporated, ElringKlinger, Autoneum, and Alkegen, among others.
Key opportunities include continued growth in battery electric vehicle production requiring specialized thermal protection, and rising demand for lightweight, non-metallic heat shield materials.
Increasing use of turbochargers in internal combustion engine vehicles, combined with the rise in plug-in hybrid and battery electric vehicles requiring both engine and battery thermal protection, is the major factor driving market growth.
The Engine Compartment segment dominated the Automotive Heat Shield Market with approximately 79.00% share in 2025.
Asia Pacific dominated the Automotive Heat Shield Market in 2025 with approximately 44.50% share, driven by the surge in automotive manufacturing across developing countries, led by China.
