
Automotive Hinges Market Report Scope & Overview:
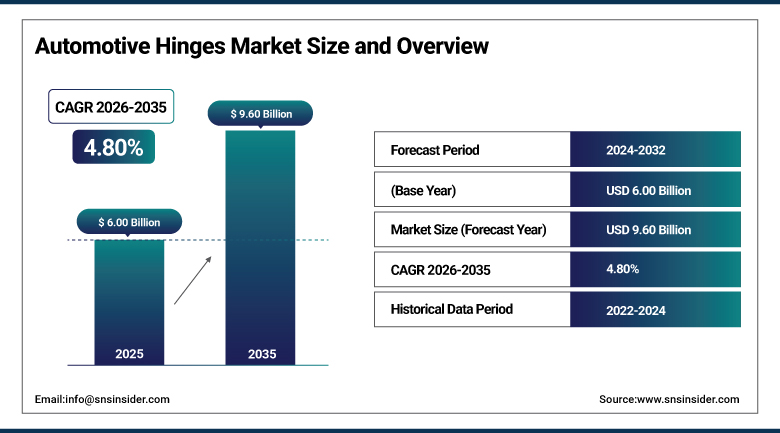
The Automotive Hinges Market was valued at USD 6.00 Billion in 2025 and is expected to reach USD 9.60 Billion by 2035, growing at a CAGR of 4.80% from 2026-2035.
This growth is driven by the continuous growth in the worldwide production of automobiles, which in turn results in an equal growth in demand for hinge assemblies for doors, hoods, and trunks that come with all the new platforms for vehicles. An increasing trend towards light-weight materials like aluminum alloys and advanced high-strength steel is influencing the specifications for the components because of the need for increased fuel efficiency and electric vehicle range among other benefits. Additionally, sensor-enabled power hinge assemblies for high and mid-end vehicle classes are widening the value addressable to the segment from mechanical assembly, alongside growing manufacturing volumes in Asia Pacific and emissions regulations in Europe.
The Magna International's SmartAccess power door assembly used in the Ferrari Purosangue uses a combination of a power door drive, a SmartLatch, cinch actuator, and Haptronik motion control software in a segment that previously only included simple mechanical components. The use of such components shows a general trend in the industry where hinge systems will have to have embedded software and sensors as opposed to the structural components alone.
To Get more information Automotive Hinges Market - Request Free Sample Report
Automotive Hinges Market Trends
-
Increasing substitution of conventional stamped steel with aluminum alloys and ultra-high-strength steel to reduce component weight
-
Growing incorporation of sensor-enabled, automated door systems across mid-tier vehicle trims in addition to flagship models
-
Rising adoption of soft-close and power-operated hinge mechanisms as a differentiating feature in premium and luxury vehicle segments
-
Expanding requirement for hinge architectures engineered specifically for battery-electric vehicle body structures and load paths
-
Growing utilization of magnet-assisted hinge designs to enhance durability and performance across electric vehicle platforms
-
Increasing OEM preference for modular hinge platforms that can be standardized across multiple vehicle lines to reduce tooling expenditure
U.S. Automotive Hinges Market Outlook
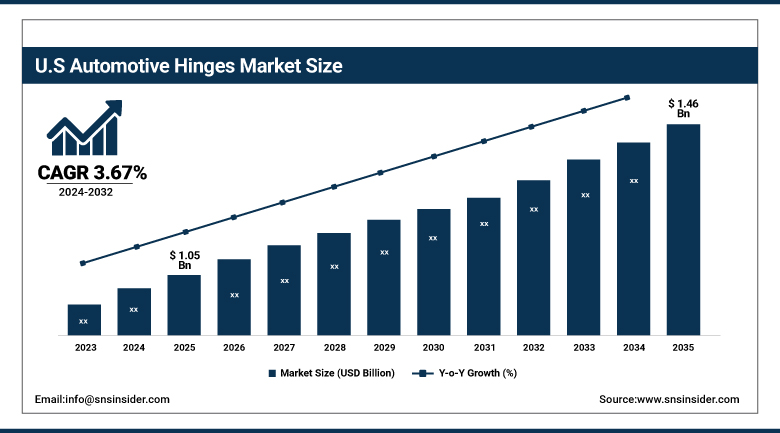
The U.S. Automotive Hinges Market was valued at approximately USD 1.05 Billion in 2025 and is expected to reach approximately USD 1.46 Billion by 2035, growing at a CAGR of approximately 3.67% from 2026-2035.
Demand within the United States is shaped substantially by vehicle segment mix rather than production volume alone, as full-size pickup trucks and sport utility vehicles impose heavier structural and load-bearing requirements on hinge assemblies relative to the compact and mid-size vehicle platforms more prevalent across Asia-Pacific markets. This distinction has enabled domestic suppliers to develop specialized engineering capabilities around heavy-duty vehicle applications. Trade policy affecting imported aluminum and steel continues to influence sourcing decisions across the domestic supply chain, with tariff-related cost pass-through contributing modestly to overall production expenses, while an aging vehicle fleet continues to generate consistent replacement demand across the aftermarket channel.
North American hinge suppliers, including Milwaukee-based Strattec Security, continue to develop specifications aligned with the heavier-load requirements of full-size trucks such as the Ford F-150 and Chevrolet Silverado, platforms that impose structural demands not typically encountered in Asia-Pacific vehicle architectures. Current U.S. tariffs on aluminum and steel imports, set at 10% and 25% respectively, are estimated to add 80 cents to $1.50 per unit in production costs, a modest but measurable factor that disproportionately affects suppliers reliant on imported components relative to domestically integrated manufacturers.
Automotive Hinges Market Segment Analysis
-
By Hinge Type, the Butt Hinges segment dominated the Automotive Hinges Market with approximately 44.60% share in 2025, while the Concealed/Pivot Hinges segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Position, the Front segment dominated the Automotive Hinges Market with approximately 56.40% share in 2025, while the Rear segment is the fastest growing with a CAGR of approximately 5.90%.
-
By Application, the Door Hinges segment dominated the Automotive Hinges Market with approximately 62.40% share in 2025, while the Hood Hinges segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Material, the Steel segment dominated the Automotive Hinges Market with approximately 62.00% share in 2025, while the Aluminum segment is the fastest growing with a CAGR of approximately 6.60%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive Hinges Market with approximately 58.00% share in 2025, while the Light Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.40%.
-
By Sales Channel, the OEM segment dominated the Automotive Hinges Market with approximately 68.40% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.80%.
By Hinge Type, Butt Hinges dominates, Concealed/Pivot Hinges grows fastest
Butt Hinges held the leading share in terms of revenue generated in 2025, around 44.60%, owing to its well-established manufacturing base, efficient manufacturing process, and wide applicability across the majority of passenger car door designs manufactured today. The widespread use of this type of hinges is additionally attributed to the fact that most electric cars retain a similar structure of doors inherited from their traditional predecessors.
Concealed/Pivot Hinges is expected to record the highest growth rate, a CAGR of about 6.80%, fueled by growing automotive manufacturers' preference for concealable mechanical components for power-operated door mechanisms and improved aesthetics of the exterior design. Installation of sensors for automated door operation is one of the factors pushing the popularity of the hinge type in question.
By Position, Front dominates, Rear grows fastest
The Front segment held the largest share of the position segment, at approximately 56.40%, in 2025, owing to higher usage frequency, greater structural loading from mirror and window mechanisms, and more stringent crash-safety reinforcement requirements typically specified for front door assemblies. These factors collectively position front hinges as the primary focus of ongoing engineering development within the category.
The Rear segment is projected to expand at the fastest rate, with a CAGR of approximately 5.90%, supported by rising production of three-row sport utility vehicles, minivans, and rear-hinged door configurations increasingly featured on select electric and luxury vehicle platforms. Growing consumer emphasis on rear passenger comfort and accessibility continues to elevate engineering investment directed toward this position.
By Application, Door Hinges dominates, Hood Hinges grows fastest
Door Hinges application was the highest in terms of market share at around 62.40% in 2025 due to higher units per car compared to hood and trunk applications, and because of stringent safety certifications for door hardware parts. It is the combination of both of these factors that makes this application area maintain its leadership.
The Hood Hinges application is projected to experience the highest growth rate with a CAGR of around 6.20%. This is due to increasing pedestrian-safety regulations that affect the way the hood bends and pivots in case of a frontal collision. It is this balancing act that engineers continue to address in such an application area.
By Material, Steel dominates, Aluminum grows fastest
The Steel segment retained the highest share of approximately 62.00%, in 2025, owing to its low-cost nature, existing stamping process, and durable nature under the cyclic load conditions. This continues to make steel the choice material specification in most of the standard hinge applications.
The Aluminum segment is expected to be the fastest-growing at a CAGR of around 6.60%, driven by the trend towards light-weighting across the industry, given that as per the estimate by International Energy Agency, reducing the weight of vehicles by 10% increases their fuel efficiency by 6% to 8%. The ultra-high-strength steel hinge line by Gestamp, which has brought about a weight saving of 15% without compromising on durability, is another such example.
By Vehicle Type, Passenger Cars dominates, Light Commercial Vehicles grows fastest
The Passenger Cars segment accounted for the largest vehicle-type share, at approximately 58.00%, in 2025, consistent with global vehicle production statistics, as passenger vehicles continue to outnumber commercial vehicles by a substantial margin across nearly every major automotive market worldwide.
The Light Commercial Vehicles segment is anticipated to grow at the fastest rate, with a CAGR of approximately 6.40%, as expanding e-commerce and last-mile delivery fleets increase the frequency of cargo door operation relative to conventional passenger vehicle usage patterns. Growing adoption of multi-leaf hinge designs, which distribute structural load across multiple connection points, is reinforcing this above-average growth trajectory.
By Sales Channel, OEM dominates, Aftermarket grows fastest
The OEM category was the most significant in terms of market share, accounting for about 68.40% in 2025. This is an indication of how far the inclusion of hinges in original vehicle design and assembly goes beyond the consumer decision-making process after purchase.
On the other hand, the Aftermarket category is forecasted to grow at the highest rate of about 6.80% annually, due to vehicles reaching their end of warranty and start exhibiting signs of wear, such as sagging and lack of proper alignment. This is because of the growing number of vehicles globally.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.60% |
|
North America |
United States |
79.80% |
|
Europe |
Germany |
26.20% |
|
Latin America |
Brazil |
34.60% |
|
Middle East & Africa |
UAE |
29.40% |
Asia Pacific Automotive Hinges Market Insights
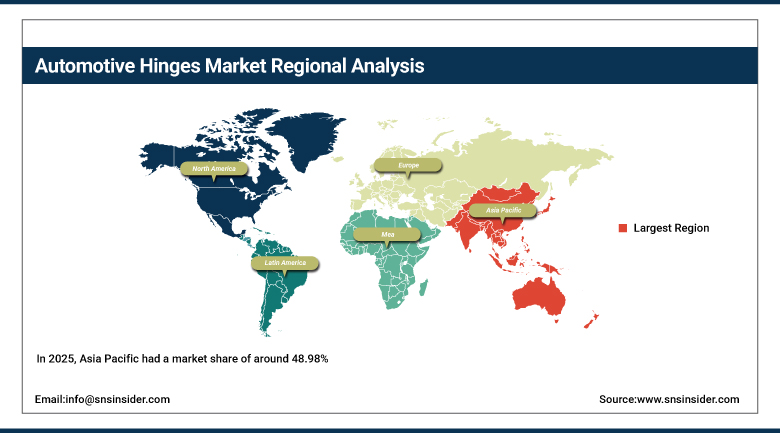
In 2025, Asia Pacific had a market share of around 48.98%, which was on account of the presence of large-scale manufacturing capability of vehicles in both China and India and the quick pace of industrialization in the region. The level of manufacturing output will ensure that Asia Pacific will remain the leading contributor to hinge demand in the world.
The huge automobile manufacturing base in China will act as a great base of support for demand in the region, whereas the auto industry of India is witnessing great investments in terms of technology and innovation.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Automotive Hinges Market Insights
Europe is projected to register the fastest regional growth, at a CAGR of approximately 6.40% from 2026 to 2035, driven primarily by regulatory pressure rather than incremental vehicle production, as Euro 7 emission standards compel automakers including Audi, Mercedes-Benz, Renault, and BMW to prioritize component-level weight reduction. Germany anchors regional demand through its established automotive manufacturing base and expanding electric vehicle production.
France and Italy contribute meaningful additional volume, with both countries navigating the same emissions-driven lightweighting requirements shaping component specifications across the broader European market.
North America Automotive Hinges Market Insights
North America represents a substantial automotive hinges market characterized by steady, replacement-driven growth rather than rapid expansion, as light-duty truck platforms impose heavier-load hinge specifications not typically required across Asia-Pacific vehicle architectures. This specialization continues to support the competitive position of established domestic suppliers.
Canada contributes additional demand through its domestic vehicle manufacturing sector, while Mexico's market continues to expand in line with nearshoring-driven manufacturing investment. Cross-border supply relationships continue to integrate production across all three North American markets.
MEA & Latin America Automotive Hinges Market Insights
The Middle East and Africa region represents a comparatively smaller but developing market, with the UAE contributing the largest share of regional demand through expanding vehicle sales and automotive retail investment tied to broader economic diversification initiatives. Growth across the remainder of the region remains closely correlated with the pace of automotive manufacturing infrastructure development.
Latin America is led by Brazil, where expanding vehicle production and rising commercial vehicle demand continue to support market growth. Mexico and Argentina contribute additional secondary demand aligned with their respective automotive manufacturing sectors.
Market Dynamics
Growth Drivers: Rising vehicle production and lightweighting demand fueling adoption
The increasing production of vehicles across the globe is still the main force behind the growth of the market, as the launch of new car models and increased competition among manufacturers, who strive to distinguish themselves through unique products, continues to support hinge market demand. This link between vehicle production and hinge demand creates the base for sustainable market growth.
Growing application of lightweight materials can be seen as the other key factor driving market growth, as automakers introduce aluminum, steel, and composites into hinge production in order to enhance fuel economy and decrease the weight of vehicles. An increase in the production of electric vehicles adds another factor to this trend in demand for hinges.
Restraints: Raw material cost volatility and engineering complexity limiting margin stability
Volatility in raw material prices constitutes a major constraint, since hinge producers are vulnerable to changes in commodity prices of steel and aluminum as well as trade policies that influence their manufacturing costs. Manufacturers who lack long-term material supply contracts are especially vulnerable to changes in cost structures, which reduce margins even in the absence of demand-side issues.
Technical complexity involved in the production of electronic and power-operated hinge products is yet another constraint, since embedding sensors and automatic actuators in hinge systems is a far more costly process than manufacturing mechanical hinges. Such a financial constraint usually favors large firms compared to smaller local firms.
Opportunities: Smart hinge technology and EV-specific design opening new growth avenues
The increasing implementation of intelligent hinge systems using sensors for automatic operation offers substantial growth potential for the market, considering the move of the feature from luxury car models to regular trim versions. Companies having the ability to integrate sensors into hinge systems can leverage the market demand to a considerable extent.
Specialized hinge system designs are another avenue through which companies can earn premium pricing from auto manufacturers, considering the need for unique designs due to the growing electric vehicle production in the coming years. The use of hinge systems with magnets is one such design that provides greater strength.
Recent Developments:
-
In May 2024, Inteva Products opened a new manufacturing plant in Suining, Sichuan Province, China, dedicated to supplying closure and hinge-related components to automakers across the Chengdu-Chongqing manufacturing corridor. The facility supports Inteva's strategy of expanding regional production capacity closer to fast-growing Chinese OEM customers while advancing the company's sustainability-focused manufacturing initiatives.
-
In May 2023, Kiekert AG introduced a new generation of lightweight, high-strength door closure hardware, including hinge-adjacent structural components, engineered specifically for electric vehicle platforms carrying additional battery-related reinforcement. The launch strengthened Kiekert's competitive position in premium and EV-focused vehicle segments across Europe and North America, where automakers increasingly specify components validated for higher body loads.
-
In 2025, Voestalpine continued fulfilling its multi-year Volkswagen Group contract for soft-close hinge systems, ramping production toward the agreed 300,000 units per year as the automaker's compact and mid-size platforms entered full-scale production across European assembly plants. The contract, worth approximately $185 million cumulatively through 2030, reflects Voestalpine's growing role as a specialized soft-close hardware supplier to Europe's largest automotive group.
-
In 2025, Aisin Seiki advanced its capital expenditure program for aluminum hinge casting capacity in Thailand, progressing toward the planned 2026 production ramp intended to supply lightweight hinge components to electric vehicle platforms operated by Toyota and BYD in the Southeast Asian market. The investment reflects Aisin's broader strategy of positioning regional casting capacity closer to fast-growing EV assembly operations across ASEAN markets.
Automotive Hinges Market Key Players
-
Dura Automotive Systems LLC
-
Gestamp Automoción, S.A.
-
Thyssenkrupp AG
-
Aisin Seiki Co., Ltd.
-
Magna International Inc.
-
Multimatic Inc.
-
Midlake Products & Manufacturing Co., Inc.
-
Eberhard Manufacturing Company
-
Inteva Products, LLC
-
Strattec Security Corporation
-
Voestalpine AG
-
IFB Automotive Pvt. Ltd.
-
Martinrea International Inc.
-
Ningbo Huaxiang Electronic Co., Ltd.
-
Benteler International AG
-
JTEKT Corporation
-
Yorozu Corporation
-
Hi-Lex Corporation
-
Faurecia SE (FORVIA)
-
Motherson Sumi Systems Limited
Automotive Hinges Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.00 Billion |
| Market Size by 2035 | USD 9.60 Billion |
| CAGR | CAGR of 4.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Hinge Type (Butt Hinges, Multi-Leaf Hinges, Concealed/Pivot Hinges, Others) • by Position (Front, Rear) • by Application (Door Hinges, Hood Hinges, Trunk/Tailgate Hinges, Others) • by Material (Steel, Aluminum, Composite) • by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles) • by Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Dura Automotive Systems LLC, Gestamp Automoción, S.A., Thyssenkrupp AG, Aisin Seiki Co., Ltd., Magna International Inc., Multimatic Inc., Midlake Products & Manufacturing Co., Inc., Eberhard Manufacturing Company, Inteva Products, LLC, Strattec Security Corporation, Voestalpine AG, IFB Automotive Pvt. Ltd., Martinrea International Inc., Ningbo Huaxiang Electronic Co., Ltd., Benteler International AG, JTEKT Corporation, Yorozu Corporation, Hi-Lex Corporation, Faurecia SE (FORVIA), Motherson Sumi Systems Limited |
Frequently Asked Questions
Leading companies include Dura Automotive Systems LLC, Gestamp Automoción, S.A., Thyssenkrupp AG, Aisin Seiki Co., Ltd., and Magna International Inc., among other major automotive body component manufacturers.
Opportunities include smart hinge technology integrating sensors for automated door systems and EV-specific hinge design engineered for unique battery-electric vehicle architectures.
Growth is driven by rising global vehicle production, use of lightweight materials for automotive products, and growth of electric vehicle production necessitating specialized hinge systems.
Butt Hinges dominates by hinge type with approximately 44.60% share, Door Hinges dominates by application with roughly 62.40% share, Steel dominates by material with about 62.00% share, and Passenger Cars dominates by vehicle type with approximately 58.00% share; Concealed/Pivot Hinges, Hood Hinges, Aluminum, and Light Commercial Vehicles are the fastest-growing segments within their respective categories.
Asia Pacific is the largest regional market with approximately 48.98% share, led by China, while Europe is the fastest-growing region at approximately 6.40% CAGR through the 2026-2035 forecast period, supported by renowned automakers and strict EU emission norms.
