
Automotive Horn Systems Market Report Scope & Overview:
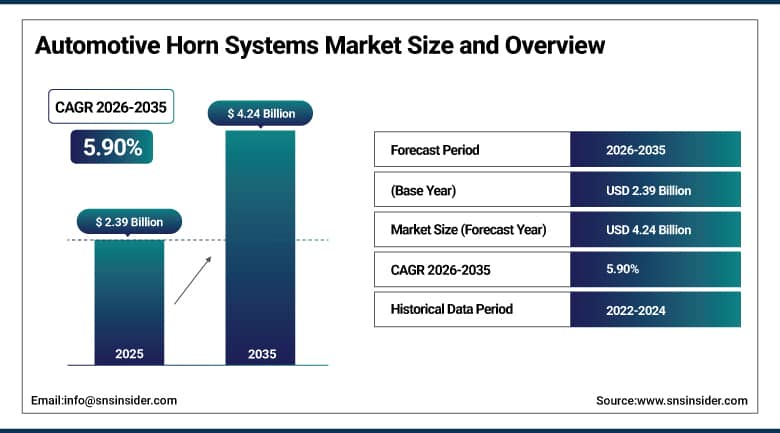
The Automotive Horn Systems Market was valued at USD 2.39 Billion in 2025 and is expected to reach USD 4.24 Billion by 2035, growing at a CAGR of 5.90% from 2026-2035.
The main reasons behind the expansion of the Automotive Horn Systems Market include increasing automobile production across the globe, increasingly stringent safety norms requiring sound alert systems, and consumer demand for unique quality acoustic alerts in all types of cars, such as passenger cars, commercial automobiles, and two wheelers. There is an increasing preference for electronic horns over the traditional air horns in cars because car manufacturers are now using small and electronically controlled signaling units that fit well in the electrical framework of today’s cars. The increasing trend of electrical vehicles across the world is pushing manufacturers of horns to come up with specialized sound systems that can function in accordance with pedestrian safety laws related to silent electric vehicles. Increasing use of two wheelers in cities, especially in Asia Pacific, is adding to the market potential for horns.
In April 2024, Uno Minda Limited, a global automotive solutions manufacturer based in India, acquired Clarton Horn S.A.U., a Spain-based automotive horn manufacturer, securing the No. 2 position among horn manufacturers worldwide. The acquisition also introduced Clarton's Premium C80 horn range to the Indian aftermarket, illustrating how leading regional suppliers are pursuing international consolidation to expand their global manufacturing footprint and product portfolio breadth.
To Get More Information On Automotive Horn Systems Market - Request Free Sample Report
Automotive Horn Systems Market Trends:
-
Continued shift from conventional air horns toward compact, electronically controlled electric horns.
-
Growing development of specialized, regulation-compliant horn systems for electric and hybrid vehicles.
-
Rising popularity of two-wheelers for urban commuting supporting horn demand across Asia Pacific.
-
Increasing adoption of trumpet and multi-tone horn designs for premium and luxury vehicle segments.
-
Expanding aftermarket customization demand for higher-decibel and distinctive-sound horn products.
U.S. Automotive Horn Systems Market Outlook:
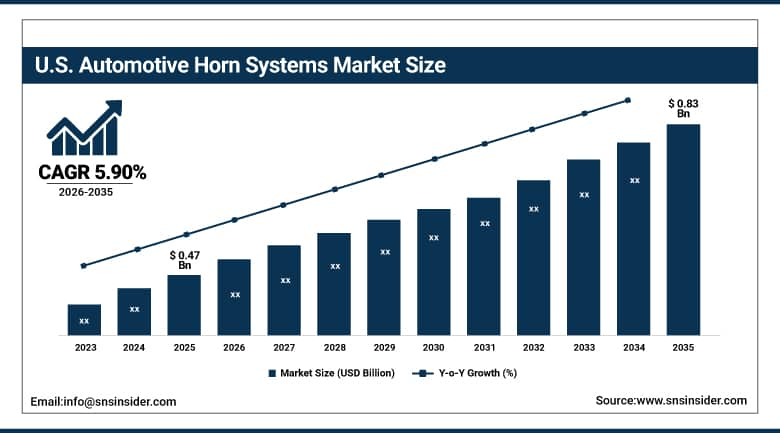
The U.S. Automotive Horn Systems Market was valued at USD 0.47 Billion in 2025 and is expected to reach USD 0.83 Billion by 2035, growing at a CAGR of 5.90% from 2026-2035.
The growth of the U.S. Automotive Horn Systems Market will continue to be driven by the consistent domestic automobile manufacturing industry, continued demand from the aftermarket sector for top-of-the-line and specialty horns, and ongoing focus on pedestrian safety through both passenger cars and commercial vehicles. The domestic market will also see demand generated from consumers’ desire to personalize their vehicles, leading to a consistent aftermarket for train horns, air horn kits, and specialty sound horns among truck and SUV drivers. The continued growth of the domestic market for electric cars will further drive demand for specialty horns that comply with federal regulations regarding pedestrian safety.
In February 2024, Wolo Manufacturing Corporation, a New York-based automotive horn and warning light manufacturer, closed an investment round of approximately EUR 1.5 million led by GVC Gaesco and other investors. The financing reflects continued investor confidence in established domestic horn and vehicle-signaling component manufacturers as demand for both OEM and aftermarket horn products remains steady across the U.S. market.
Automotive Horn Systems Market Segment Analysis:
-
By Product Type, the Electric Horn segment dominated the Automotive Horn Systems Market with approximately 65.00% share in 2025, and is also the fastest growing with a CAGR of approximately 7.20%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Horn Systems Market with approximately 52.50% share in 2025, while the Two-Wheelers segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Sound Intensity, the 100-120 dB segment dominated the Automotive Horn Systems Market with approximately 55.04% share in 2025, while the Above 120 dB segment is the fastest growing with a CAGR of approximately 7.90%.
-
By Sales Channel, the OEM segment dominated the Automotive Horn Systems Market with approximately 71.50% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.80%.
By Product Type, Electric Horn dominates and grows fastest
Electric horns continue to be the dominant and fastest-growing segment of the Automotive Horn Systems Market, owing to their small size, reduced manufacturing costs, and ease of integration into the current electrical systems of today’s automobiles. The segment will gain an advantage from the widespread use of electric horns among automotive manufacturers in nearly all vehicle segments – ranging from the basic passenger cars to more advanced commercial vehicles – due to their superior performance as compared to the competing air horns.
The segment will be guided by the development of innovations related to sound modulation techniques and smaller diaphragms, which can increase decibels despite the reduction of size and weight of vehicles. With the increasing manufacture of electric and hybrid vehicles, there is a need for special types of electric horns designed to fulfill pedestrian safety requirements of silent vehicles.
By Vehicle Type, Passenger Vehicles dominates and Two-Wheelers grows fastest
The Passenger Vehicles segment is expected to dominate the Automotive Horn Systems market owing to the huge volumes of passenger car production worldwide and the presence of horns as a compulsory safety feature in almost all types of vehicles sold around the world. The segment gains an advantage due to the uniformity of per vehicle horn content for sedans, SUVs and crossover cars, along with multiple horns installed in luxury vehicles.
The Two Wheelers segment is poised to grow rapidly, spurred by the increasing adoption of motorcycles and scooters as vehicles for urban commuting. The segment will emphasize efficient and cost-effective horn systems designed for compact two-wheelers, making it well-placed to increase its share in the total horns market.
By Sound Intensity, 100-120 dB dominates and Above 120 dB grows fastest
The Sound Intensity of 100-120 dB is the major segment of Automotive Horn Systems Market that has adequate loudness to warn the surrounding vehicles and people without violating noise regulations of various regions for standard passenger cars and commercial vehicles' horns. The popularity of this segment is due to the fact that it enjoys wide acceptance among various regions and thus becomes the default choice for automotive horn systems.
The Sound Intensity 'Above 120 dB' is the fastest-growing segment of Automotive Horn Systems Market driven by industrial and commercial vehicles that require highly decibels alarms for safe operation amid high noise conditions. This segment targets at designing horns for heavy vehicles which would be audible even amid industrial noises, hence making above 120 dB horns more attractive for commercial and industrial vehicles.
By Sales Channel, OEM dominates and Aftermarket grows fastest
OEM sales remain the dominant channel within the Automotive Horn Systems Market, reflecting horns' status as a mandatory factory-installed safety component across virtually all new vehicles produced globally. This segment benefits from long-term supply agreements between horn manufacturers and vehicle assemblers, sustaining stable, high-volume demand tied directly to global vehicle production levels.
The Aftermarket segment is emerging as the fastest-growing sales channel, driven by rising consumer interest in vehicle personalization and demand for higher-decibel, distinctive-sound horn upgrades among truck, SUV, and specialty vehicle owners. This segment focuses on premium trumpet and multi-tone horn products marketed directly to consumers seeking to differentiate their vehicles, supporting above-market growth as aftermarket customization trends continue to expand.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
India |
54.80% |
|
North America |
United States |
79.50% |
|
Europe |
Germany |
26.40% |
|
Latin America |
Brazil |
47.60% |
|
Middle East & Africa |
United Arab Emirates |
28.90% |
Asia Pacific Automotive Horn Systems Market Insights
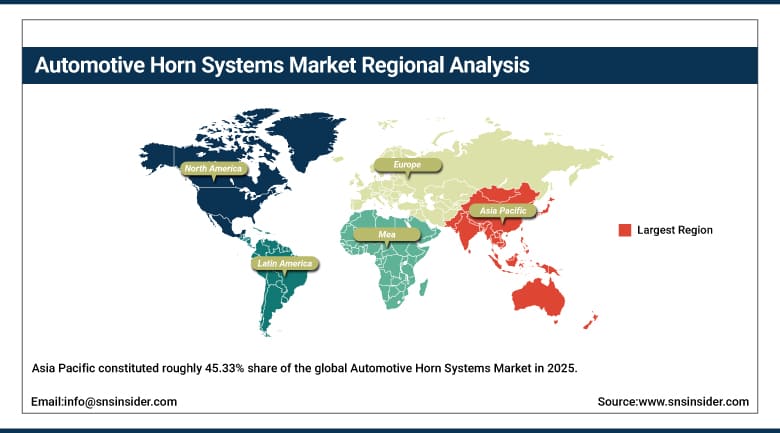
Asia Pacific constituted roughly 45.33% share of the global Automotive Horn Systems Market in 2025 and is also expected to grow at the highest rate during the forecast period of 2026-2035 owing to its huge manufacturing capacity of vehicles, high prevalence of two-wheelers, and active research & development activities in the region. India is one of the most significant contributors in the region, which is due to the country's huge manufacturing capacity of two-wheelers and passenger vehicles.
China makes additional contribution to regional volume owing to its huge vehicle assembling capacity and presence of automotive components suppliers in the region. The automotive electronics manufacturing expertise of Japan and South Korea adds value to the depth of component supply chain in the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Horn Systems Market Insights
North America represents a significant regional market for automotive horn systems, anchored by the United States' substantial vehicle production base and its well-established aftermarket customization culture. The United States accounts for the substantial majority of regional demand, reflecting both its vehicle production scale and its position as the leading market for premium and specialty aftermarket horn products.
Canada and Mexico contribute additional regional volume through cross-border automotive supply chain integration linked to broader North American vehicle assembly. Continued growth in domestic light-truck and SUV production, segments that frequently feature premium horn upgrades, further supports steady regional demand growth over the forecast period.
Europe Automotive Horn Systems Market Insights
Europe emerges as a significant regional market for automotive horns on account of the dominance of Germany in terms of vehicle manufacturing and premium automotive manufacturers who incorporate advanced horns in their automobiles. The percentage share of Germany in the European market is based on the large share of vehicle production in the region and presence of suppliers of horn modules in the domestic market.
The regional demand from France and Italy is due to the presence of automotive manufacturing sector in the regions. Further, the demand in Europe is likely to remain steady owing to the vehicle safety standards of European Union and incorporation of advanced horns in premium automobiles.
MEA & Latin America Automotive Horn Systems Market Insights
Latin America's Automotive Horn Systems Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic vehicle assembly base and its role as a regional export hub for automakers operating in the region. Rising passenger car and light commercial vehicle sales across Brazil, Mexico, Colombia, and Argentina continue to support steady regional demand growth.
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where rising vehicle imports and growing automotive aftermarket activity are gradually increasing component demand. South Africa continues to anchor horn-related demand on the African continent, supported by its comparatively more developed automotive assembly and export base.
Market Dynamics:
Growth Drivers: Rising Vehicle Production and Road Safety Regulation
Increasing global vehicle manufacture, especially within Asia Pacific region manufacturing locations, is increasing the potential customer base for horn requirement owing to the fact that each vehicle manufactured requires at least one horn to fulfill its safety needs. Stricter road safety legislations requiring audio alarms systems, especially in highly congested urban areas, are contributing towards increasing demand in all vehicle types.
Increasing popularity of two-wheelers as means of transport in emerging economies where populations are highly concentrated provides an additional major driver of demand due to high number of motorbikes and scooters produced in these economies. Increasing aftermarket customization demand in developed economies owing to consumer interest in personalizing their vehicles also contributes to market growth.
Restraints: Vehicle Electrification and Noise Regulation Complexity
The transition toward electric vehicles presents a nuanced restraint on the Automotive Horn Systems Market, as automakers must develop specialized, quieter-operating horn systems calibrated to comply with pedestrian-safety regulations designed for near-silent vehicles, adding engineering complexity and cost relative to conventional horn designs. This dynamic requires suppliers to validate new horn technology against evolving regulatory requirements that vary meaningfully across different national and regional jurisdictions.
Increasingly stringent noise pollution regulations in certain urban markets restrict maximum permissible horn decibel levels, limiting manufacturers' ability to differentiate products through higher sound output in these jurisdictions. Continued raw material and component cost volatility adds further uncertainty to long-term manufacturing cost planning across the broader horn supply chain.
Opportunities: Electric Vehicle-Specific Horn Technology and Aftermarket Expansion
Development and supply of specific horns compliant with regulations to fit electric/hybrid vehicles will create immense opportunities for the Automotive Horns Systems market as vehicle manufacturers increasingly seek to equip such vehicles with horn systems tailored for pedestrian safety in accordance with the safety needs associated with silent vehicles. Suppliers capable of supplying validated, yet cost-effective electric vehicle horns have an opportunity to gain market share as the manufacturing of electric vehicles picks pace globally.
Increasing consumer preference for aftermarket customization creates immense opportunity for suppliers to add to their portfolio of products high-end horns with distinct sound characteristics for marketing to consumers.
Recent Developments:
-
In June 2024, Uno Minda introduced its D-90 horn range in India, designed to meet growing demand for high-quality, OEM-spec horns in the aftermarket, with the range tailored specifically for Maruti Suzuki and Tata passenger vehicles as well as light commercial vehicles.
-
In January 2025, Hella announced a strategic partnership with Seewon Automotive to co-develop next-generation horn modules for electric vehicles, integrating smart control capabilities and digital sound profiling into the joint development program.
-
In April 2025, Fiamm introduced a modular high-decibel horn system designed specifically for electric vehicles, featuring a compact form factor and reduced current draw compared to the company's earlier horn product lines.
-
In June 2025, Denso announced a major contract win to supply horn actuators for a leading Southeast Asian automaker, reinforcing the company's position in onboard acoustic warning systems for new vehicle platforms.
Automotive Horn Systems Market Key Players:
-
Fiamm Energy Technology S.p.A.
-
Hella GmbH & Co. KGaA
-
Robert Bosch GmbH
-
Denso Corporation
-
Mitsuba Corporation
-
Uno Minda Limited
-
Sankei Giken Kogyo Co., Ltd.
-
Wolo Manufacturing Corporation
-
Kleinn Automotive Accessories, Inc.
-
Stebel S.r.l.
-
Marco Segnalamento S.r.l.
-
Grote Industries, LLC
-
Truck-Lite Co., LLC
-
Hadley Products Corporation
-
Federal Signal Corporation
-
HELLA India Lighting Ltd.
-
Continental AG
-
Valeo S.A.
-
ZF Friedrichshafen AG
-
Roots Industries India Limited
Automotive Horn Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.39 Billion |
| Market Size by 2035 | USD 4.24 Billion |
| CAGR | CAGR of 5.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Electric Horn and Air Horn) • by Vehicle Type (Passenger Vehicles, Two-Wheelers, and Commercial Vehicles) • by Sound Intensity (Below 100 dB, 100-120 dB, and Above 120 dB) • by Sales Channel (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Fiamm Energy Technology S.p.A., Hella GmbH & Co. KGaA, Robert Bosch GmbH, Denso Corporation, Mitsuba Corporation, Uno Minda Limited, Sankei Giken Kogyo Co., Ltd., Wolo Manufacturing Corporation, Kleinn Automotive Accessories, Inc., Stebel S.r.l., Marco Segnalamento S.r.l., Grote Industries, LLC, Truck-Lite Co., LLC, Hadley Products Corporation, Federal Signal Corporation, HELLA India Lighting Ltd., Continental AG, Valeo S.A., ZF Friedrichshafen AG, Roots Industries India Limited |
Frequently Asked Questions
Leading companies in the Automotive Horn Systems Market include Fiamm, Hella, Robert Bosch, Denso, and Uno Minda, among others.
Key opportunities include continued development of specialized, regulation-compliant horn systems for electric and hybrid vehicles, and rising aftermarket customization demand for premium, distinctive-sound horn products.
Rising global vehicle production combined with tightening road safety regulations mandating audible warning systems is the major factor driving market growth.
The Passenger Vehicles segment dominated the Automotive Horn Systems Market with approximately 52.50% share in 2025.
Asia Pacific dominated the Automotive Horn Systems Market in 2025 with approximately 45.33% share, driven by massive vehicle manufacturing scale and high prevalence of two-wheelers, led by India.
