
Automotive Parking Sensors Market Report Scope & Overview:
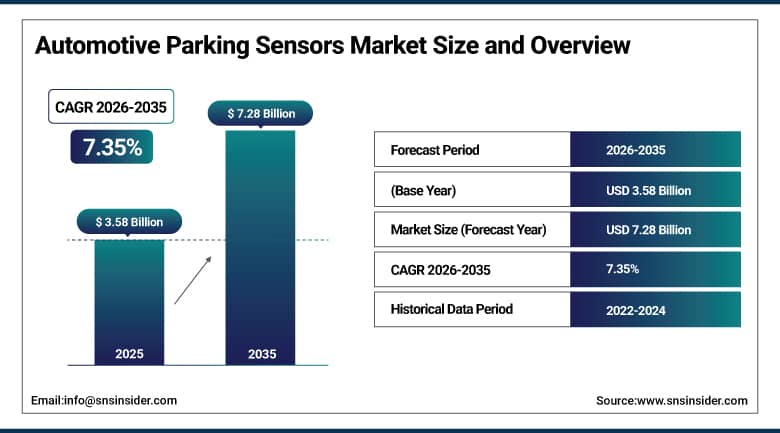
The Automotive Parking Sensors Market was valued at USD 3.58 Billion in 2025 and is expected to reach USD 7.28 Billion by 2035, growing at a CAGR of 7.35% from 2026-2035.
The automotive parking sensor market is growing as the demand for advanced driver assistance systems and smart parking increases. Parking sensors, which are key proximity devices that help detect obstacles while parking, are usually mounted on the front, rear, or both ends of the automobile. The increase in the occurrence of accidents in parking has made the use of parking sensors very important, and hence there is an increase in the use of these sensors in several brands and models of cars, and more than 55% of the new automobiles are fitted with these sensors. The average number of ultrasonic sensors per passenger car has risen from four in 2019 to over eight in 2025.
In 2025, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG have kept rolling out innovations in their parking assist sensor products, with surround view cameras and ultrasonic sensors among others. These are part of strategic partnerships and collaborations that keep defining the overall market dynamics in this space. Hyundai Motor Company teamed up with NVIDIA for its parking assist system technology development and deployment, a trend that shows how the automotive sector is gradually moving towards integrating the concept of AI computing capabilities with ultrasonic sensors to provide smarter camera-based parking assists.
To Get More Information On Automotive Parking Sensors Market - Request Free Sample Report
Automotive Parking Sensors Market Trends
- Rising integration of ultrasonic sensors with camera systems for enhanced parking accuracy and obstacle detection.
- Growing adoption of front sensor coverage as standard equipment alongside traditionally more common rear sensors.
- Expanding online retail distribution channel offering competitive pricing and broader reach for aftermarket buyers.
- Increasing government regulations mandating parking assistance systems in new vehicles across multiple regions.
- Rising consumer preference for vehicles equipped with smarter, technology-enabled safety features during purchase decisions.
U.S. Automotive Parking Sensors Market Outlook
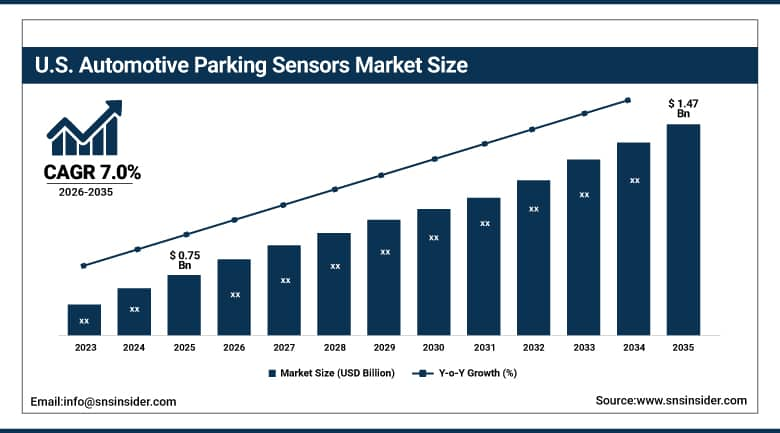
The U.S. Automotive Parking Sensors Market was valued at USD 0.75 Billion in 2025 and is expected to reach USD 1.47 Billion by 2035, growing at a CAGR of 7.0% from 2026-2035.
The U.S. Automotive Parking Sensors Market remains defined by high levels of vehicle ownership, a large aftermarket component, and regulatory advancements toward enhanced safety standards, which drive the use of sensors within new vehicle models and retrofitting of existing fleets. Connected cars and autonomous driving technologies remain core drivers of domestic market expansion, while original equipment manufacturers such as Ford, General Motors, and Tesla continue to develop advanced parking sensors into their vehicles as standard or optional components of ever more varied vehicle models and trim levels. The aftermarket segment continues to experience growth due to consumer demand for installed safety technology, driven by a well-developed distribution channel and innovative wireless sensor modules.
In February 2025, the U.S. Department of Transportation highlighted Seattle’s use of 274 sensors buried in parking lots to gather curb parking data, as cities increasingly make use of sensor technology to help manage parking data. This application helps support further initiatives relating to smart cities and connected mobility, as real-time parking availability becomes possible through such applications. Municipalities’ use of parking sensors adds to demand for vehicles fitted with parking sensors, especially as more cities invest in parking infrastructure, which also opens up new opportunities for sensor manufacturers and technology suppliers.
Automotive Parking Sensors Market Segment Analysis
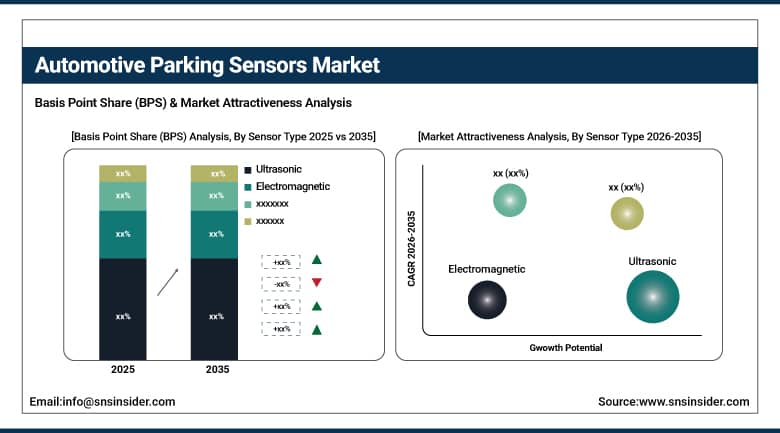
- By Sensor Type, the Ultrasonic segment dominated the Automotive Parking Sensors Market with approximately 68.60% share in 2025, while the Electromagnetic segment is the fastest growing with a CAGR of approximately 8.40%.
- By Vehicle Type, the Passenger Cars segment dominated the Automotive Parking Sensors Market with approximately 72.60% share in 2025, and is also the fastest growing with a CAGR of approximately 7.80%.
- By Sales Channel, the OEM segment dominated the Automotive Parking Sensors Market with approximately 62.60% share in 2025, while the Online Retail/Aftermarket segment is the fastest growing with a CAGR of approximately 10.20%.
- By Product Type, the Rear Parking Sensors segment dominated the Automotive Parking Sensors Market with approximately 54.60% share in 2025, while the Front Parking Sensors segment is the fastest growing with a CAGR of approximately 8.20%.
By Sensor Type, Ultrasonic Dominates the Automotive Parking Sensors Market and Electromagnetic Grows Fastest
Ultra-sonic parking sensors account for the bulk of the market share due to their position as the most widely used and least expensive type of parking sensors technology in all types of vehicles, from low end economy cars through high end luxury cars. The average number of ultra-sonic sensors fitted per passenger car has seen a significant rise during recent years, from about four sensors per vehicle in 2019 to more than eight sensors per vehicle in 2025, as automakers increasingly fit these sensors not only in the rear bumper, but in the front and side of the vehicle as well, contributing significantly to per car revenue generation of the sensor suppliers despite relatively small price per unit of sensor.
Electro magnetic sensors represent the fastest-growing sensor type, offering genuine installation advantages for certain vehicle applications where traditional ultrasonic sensor mounting proves more difficult or where a less visually intrusive sensor integration is desired, since electromagnetic sensing technology can in some configurations avoid the visible drilled mounting holes that ultrasonic sensor installation typically requires. As automakers and aftermarket suppliers continue seeking sensor technologies that balance detection accuracy with aesthetic and installation flexibility considerations, electromagnetic sensor adoption continues to expand across specific vehicle segments and applications where these particular advantages carry meaningful weight, positioning this sensor type for sustained above-market growth even as ultrasonic technology retains its position as the dominant overall sensor type.
By Vehicle Type, Passenger Cars Dominates the Automotive Parking Sensors Market and Also Grows Fastest
Passenger cars represent the largest vehicle type segment, reflecting both the sheer scale of global passenger vehicle production relative to commercial vehicles and the increasingly universal consumer expectation that parking sensors represent a standard, rather than premium, safety feature across virtually every new vehicle price tier. Consumer surveys indicate that over 73% of new passenger car buyers in developed markets rate parking assistance as a top-five desired safety feature, underscoring the genuine demand durability this segment continues to demonstrate even as broader automotive market conditions fluctuate across different economic cycles and regions.
Passenger cars are also the fastest-growing vehicle type, supported by continued original equipment manufacturer fitment rate expansion as automakers increasingly bundle parking sensors into base trim packages rather than reserving the technology exclusively for premium option packages. The rising sales of passenger cars, particularly in developing economies experiencing rapid middle-class expansion and growing first-time vehicle ownership, continues to reinforce sustained above-market growth for this vehicle type as an expanding global consumer base gains access to vehicles equipped with increasingly standard parking assistance technology.
By Sales Channel, OEM Dominates the Automotive Parking Sensors Market and Online Retail/Aftermarket Grows Fastest
OEM is the dominant sales channel in terms of market share owing to the strategic relationships and supply arrangements between the sensor makers and automotive OEMs, which help ensure a steady stream of predictable revenues for the sensor vendors and easy incorporation of the devices into the latest vehicles during the entire production planning process. As parking sensors have become part of more than 55% of the newly manufactured cars, the OEM sales channel remains the major source of volume for sensor companies due to their inclusion in the latest vehicles by automotive OEMs.
Online retail distribution within the broader aftermarket channel represents the fastest-growing sales channel, as consumers and independent repair shops increasingly purchase sensors and complete sensor kits through e-commerce platforms rather than traditional brick-and-mortar retail locations. Enhanced digital presence, increasingly competitive online pricing, and genuinely global reach continue to contribute to strong growth within this channel, with online distribution expected to achieve double-digit compound annual growth throughout the forecast period as digital commerce continues capturing an increasing share of automotive aftermarket parts purchasing across virtually every major global market.
By Product Type, Rear Parking Sensors Dominates the Automotive Parking Sensors Market and Front Parking Sensors Grows Fastest
Rear parking sensors hold the largest product type share, reflecting their status as the original and still most commonly deployed parking sensor configuration, given that reverse parking maneuvers have historically presented the greatest visibility challenge and corresponding accident risk for drivers across virtually every vehicle type. Rear sensor installation became standard or regulatory-mandated equipment across many major markets well before front sensor coverage achieved comparable adoption, giving this product type a substantial head start in cumulative installed base and continuing to sustain its position as the largest single product category within the broader parking sensor market.
Front parking sensors represent the fastest-growing product type, as front and side sensor coverage continues becoming increasingly standard equipment across new vehicle production, extending comprehensive obstacle detection coverage around the entire vehicle perimeter rather than the rear-only coverage that characterized earlier generations of parking assistance technology. As automakers continue recognizing that front-end parking accidents, while historically less common than rear-end incidents, still represent a meaningful source of low-speed collision damage and driver frustration, sustained investment in front sensor integration continues to drive this product type's above-market growth trajectory relative to the more established, rear-sensor-dominated overall market.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Automotive Parking Sensors Market Insights
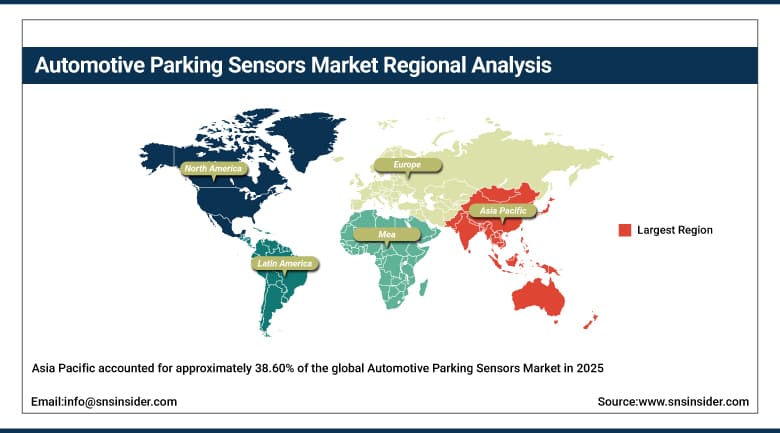
Asia Pacific accounted for approximately 38.60% of the global Automotive Parking Sensors Market in 2025, while the region is expected to register the fastest growth with a CAGR of approximately 9.87% from 2026 to 2035. This is fueled by urbanization, rising number of vehicles, and government initiatives that aim to encourage development of smart infrastructure in these countries’ large automotive manufacturing markets. Nations like China, Japan, South Korea, and India still maintain this growth pace owing to the advancements in technology as well as government policies encouraging the use of parking sensors in more affordable and higher-priced cars.
The region's automotive manufacturers, including Toyota, Hyundai, and Tata Motors, continue integrating parking sensors into a broad range of vehicles spanning economy to premium segments, aligning product development with regional safety standards and increasingly sophisticated consumer preferences. The proliferation of connected vehicle platforms and IoT-enabled infrastructure across Asia Pacific continues enhancing sensor deployment opportunities, as regional automakers increasingly view parking sensor integration as both a safety necessity and a competitive differentiator in an intensely competitive regional automotive market, reinforcing Asia Pacific's position as the largest and fastest-growing regional market through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Parking Sensors Market Insights
North America contributes to a considerable proportion of the global Automotive Parking Sensors Market on the basis of the fact that it is dominated by the United States, which enjoys very high vehicle penetration rates along with the presence of an extensive aftermarket segment and safety rules that continue to encourage the usage of parking sensors in cars, both new and existing. The automotive parking sensors market in North America is supported by increasing adoption of these parking sensors in new vehicle models by Original Equipment Manufacturers.
Canada and Mexico contribute additional regional demand as their own automotive manufacturing and consumer markets continue evolving alongside broader North American vehicle safety standards. Continued domestic investment in aftermarket distribution infrastructure and wireless sensor module innovation is expected to sustain steady regional growth through the forecast period, even as the region trails Asia Pacific in both absolute market size and percentage growth rate.
Europe Automotive Parking Sensors Market Insights
Europe represents a substantial share of the global Automotive Parking Sensors Market, with demand reinforced by stringent European Union regulations mandating parking assistance for all new vehicles across the region. This regulatory framework continues to guarantee sustained baseline demand for parking sensor technology across the entire European new vehicle market, regardless of broader economic conditions that might otherwise influence discretionary automotive safety feature adoption in less regulated markets.
The presence of an extensive automotive manufacturing industry in Germany is expected to provide a strong base for regional demand, along with contributions by other countries like France, Italy, and others where the automotive industry in Europe is prominent and are witnessing sustained growth in demand due to sensor installation in more models by these companies. There is increasing investment by regional vendors in sensor technology.
MEA & Latin America Automotive Parking Sensors Market Insights
The Middle East & Africa market is supported by growing vehicle ownership and rising automotive safety awareness across the United Arab Emirates and Saudi Arabia, where regional governments continue investing in broader automotive safety infrastructure and regulatory frameworks. Regional automotive markets continue gradually adopting parking sensor technology as consumer safety expectations continue rising alongside broader economic development.
Latin America's market is led by Brazil, where a substantial domestic automotive manufacturing and consumer sector sustains steady demand for parking sensor technology. Mexico is contributing growth as regional automotive manufacturing continues to expand, with adoption across the broader region concentrated among both OEM fitment and a growing aftermarket retrofit sector serving the region's substantial existing vehicle fleet.
Growth Drivers: ADAS Adoption and Parking Safety Regulation
Increasing demand for advanced driver-assistance systems represents the primary driver of Automotive Parking Sensors Market growth, as parking sensors, critical proximity devices, continue assisting drivers by detecting obstacles during parking, enhancing both safety and convenience across virtually every vehicle segment. The rising incidence of parking-related accidents has heightened the need for such technologies, fueling adoption across various car manufacturers and models as safety continues to rank among the most important purchase considerations for consumers worldwide.
Stringent government regulations mandating parking assistance systems in new vehicles across several regions represent a second major growth driver, as regulatory bodies increasingly recognize parking sensor technology as an effective, relatively low-cost intervention for reducing low-speed collision incidents and associated injuries. Technological advancements, including the integration of ultrasonic and radar sensors with improved accuracy and range, continue further fueling market growth as suppliers develop increasingly sophisticated sensor technology capable of detecting an expanding range of obstacle types and environmental conditions.
Restraints: Sensor Reliability Limitations and Aftermarket Installation Complexity
Sensor reliability limitations represent a meaningful restraint on market growth, as ultrasonic and other sensing technologies can occasionally struggle to reliably detect certain obstacle types, including thin poles, low curbs, or objects at unusual angles, creating genuine performance gaps that continue to require ongoing technology refinement and, in some cases, combination with complementary sensing technologies including cameras to achieve fully reliable obstacle detection.
Aftermarket installation complexity represents a further restraint, as retrofit sensor installation, while increasingly simplified through wireless sensor module innovation, still typically requires some combination of professional installation expertise or consumer technical comfort that can limit aftermarket adoption among less technically confident vehicle owners, particularly for more sophisticated sensor kits requiring integration with existing vehicle electrical systems.
Opportunities: Front Sensor Standardization and Sensor Fusion Integration
Continued standardization of front sensor coverage represents a substantial opportunity, as manufacturers that can deliver cost-effective front sensor integration alongside already-standard rear coverage are positioned to capture demand from automakers seeking to extend comprehensive perimeter obstacle detection across an expanding range of vehicle price points and segments.
The continued integration of parking sensor data with broader ADAS and eventual autonomous vehicle sensor fusion architectures offers a further substantial avenue for growth, as parking sensors increasingly serve not merely as standalone safety devices but as one component within a broader suite of sensors, cameras, and radar systems that collectively enable increasingly sophisticated driver assistance and eventual autonomous parking capability. Suppliers that can successfully position their sensor technology within these broader integrated systems are well positioned to capture demand from automakers pursuing increasingly comprehensive ADAS and autonomous vehicle development programs.
Recent Developments
- 2026: Valeo secured a contract with a North American EV manufacturer for its next-generation corner-radar suite, supporting both driving and parking applications and OTA feature upgrades.
- 2026: Aptiv presented its PULSE sensor at CES, combining surround-view cameras with ultra-short-range radar to improve 360-degree perception for parking and dense urban driving scenarios.
- 2026: Magna continued advancing ADAS and automated-driving technologies, including perception systems combining cameras, radar, and other sensing technologies for parking and low-speed maneuvering.
Automotive Parking Sensors Companies are:
- Robert Bosch GmbH
- Aptiv PLC
- Denso Corporation
- NXP Semiconductors N.V.
- Valeo SE
- Autoliv Inc.
- Continental AG
- Aisin Seiki Co., Ltd.
- Magna International Inc.
- ZF Friedrichshafen AG
- Hyundai Mobis Co., Ltd.
- Texas Instruments Incorporated
- Murata Manufacturing Co., Ltd.
- Infineon Technologies AG
- STMicroelectronics N.V.
- Rostra Precision Controls, Inc.
- Voxx International Corporation
- EchoMaster (Voxx)
- Ficosa International S.A.
- Pyle Audio Inc.
Automotive Parking Sensors Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.58 Billion |
| Market Size by 2035 | USD 7.28 Billion |
| CAGR | CAGR of 7.35% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Sensor Type (Ultrasonic, Electromagnetic, Infrared, Others) • By Vehicle Type (Passenger Cars, Commercial Vehicles) • By Sales Channel (OEM, Aftermarket) • By Product Type (Front Parking Sensors, Rear Parking Sensors, Front and Rear Parking Sensors, Integrated Surround Parking Sensor Systems) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Aptiv PLC, Denso Corporation, NXP Semiconductors N.V., Valeo SE, Autoliv Inc., Continental AG, Aisin Seiki Co., Ltd., Magna International Inc., ZF Friedrichshafen AG, Hyundai Mobis Co., Ltd., Texas Instruments Incorporated, Murata Manufacturing Co., Ltd., Infineon Technologies AG, STMicroelectronics N.V., Rostra Precision Controls, Inc., Voxx International Corporation, EchoMaster (Voxx), Ficosa International S.A., Pyle Audio Inc. |
Frequently Asked Questions
Key players include Robert Bosch GmbH, Aptiv PLC, Denso Corporation, NXP Semiconductors N.V., Valeo SE, Continental AG, and ZF Friedrichshafen AG, among other automotive sensor suppliers.
Continued standardization of front sensor coverage and continued integration of parking sensor data with broader ADAS sensor fusion architectures represent the primary opportunities.
Growth is primarily driven by increasing demand for advanced driver-assistance systems combined with stringent government regulations mandating parking assistance in new vehicles.
By Sensor Type, Ultrasonic dominated the market with approximately 68.60% share in 2025, reflecting its established manufacturing base and favorable cost structure across vehicle segments.
Asia Pacific dominated the market with approximately 38.60% share in 2025, driven by rapid urbanization and expanding vehicle ownership across the region.
