
Automotive Insurance Market Report Scope & Overview:
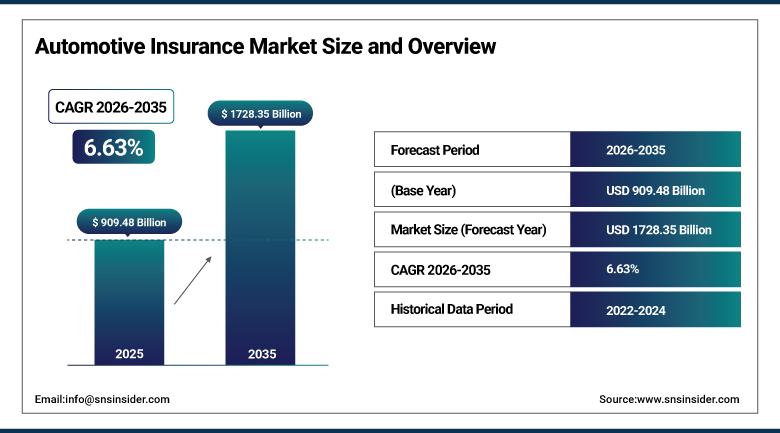
The Automotive Insurance Market was valued at USD 909.48 Billion in 2025 and is expected to reach USD 1,728.35 Billion by 2035, growing at a CAGR of 6.63% from 2026-2035.
Automotive insurance provides financial protection against the costs of vehicle damage, liability for injury or property damage caused to others, and medical expenses arising from accidents, purchased by essentially every vehicle owner in markets where coverage is legally mandated and by a substantial share of owners even where it is not. The category spans everything from basic third-party liability coverage required simply to operate a vehicle legally through comprehensive policies covering theft, weather damage, and collision regardless of fault. Growth is supported by increasing vehicle sales worldwide, enhanced customer awareness regarding insurance products and coverage options, and continued technological transformation as insurers increasingly rely on telematics, artificial intelligence, and big data analytics to price risk with a precision that traditional demographic-based underwriting could never achieve.
In 2026, Progressive Corporation continued expanding its use of generative artificial intelligence to refine auto insurance policy pricing and identify new growth opportunities, building on its Snapshot telematics program, which the company has operated for nearly two decades and which, combined with a strategic partnership with AI platform vendor H2O.ai, now delivers what the company describes as approximately 9 percent more accurate risk pricing than conventional demographic-based underwriting models.
To Get more information Automotive Insurance Market - Request Free Sample Report
Automotive Insurance Market Trends
- Rising adoption of usage-based and telematics-driven insurance pricing tied directly to individual driving behaviour.
- Growing use of generative AI within underwriting, claims processing, and customer service functions.
- Expanding state-level legislation governing telematics data privacy and permissible use in premium pricing.
- Increasing average claims severity driven by rising vehicle repair costs and advanced driver assistance system components.
- Rising adoption of pay-per-mile insurance products appealing to lower-mileage and occasional drivers.
- Growing competition from digital-first, direct-to-consumer insurtech platforms challenging traditional agency distribution.
U.S. Automotive Insurance Market Overview
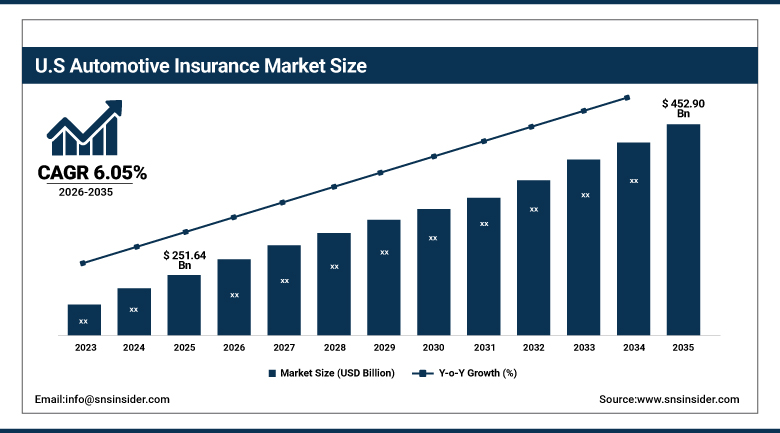
The U.S. Automotive Insurance Market was valued at USD 251.64 Billion in 2025 and is expected to reach USD 452.90 Billion by 2035, growing at a CAGR of 6.05% from 2026-2035.
The U.S. Automotive Insurance Market benefits from substantial vehicle parc, mandatory liability insurance coverage in nearly all states, and top insurance companies with headquarters located in the country that fiercely compete through telematics technology and AI-based price-setting. Increasing costs associated with vehicle ownership, changes in vehicle ownership trends, and the expansion of direct-to-consumer sales platforms keep changing the way consumers purchase auto insurance, whereas insurers use more and more often artificial intelligence-based chatbots and virtual assistants to enhance claims handling efficiency. Top insurance companies keep enrolling new policyholders into their telematics program in exchange for discounts on premiums and driving behavior data collection, despite growing attention paid to data privacy concerns by consumers and regulators alike.
In 2026, State Farm implemented significant changes across its U.S. auto-insurance business after reporting positive 2025 underwriting results. The company announced approximately USD 4.6 billion in annual premium savings from auto-rate reductions across 40 states, averaging roughly 10% over the preceding year. State Farm also declared a one-time USD 5 billion cash-back dividend for qualifying auto customers, covering more than 49 million insured vehicles. The development demonstrates a major U.S.-specific adjustment to customer pricing and returns within State Farm’s automobile insurance operations.
Automotive Insurance Market Segment Analysis
- By Coverage Type, the Third-Party Liability segment dominated the market with a 62.75% share in 2025, while the Comprehensive Insurance segment is the fastest growing with a CAGR of 6.35% during 2026-2035.
- By Vehicle Type, the Passenger Cars segment dominated the market with a 71.40% share in 2025, while the Two-Wheelers segment is the fastest growing with a CAGR of 7.85% during 2026-2035.
- By Policy Type, the Personal Auto Insurance segment dominated the market with a 78.60% share in 2025, while the Commercial Auto Insurance segment is the fastest growing with a CAGR of 8.75% during 2026-2035.
- By Distribution Channel, the Agency and Broker segment dominated the market with a 41.85% share in 2025, while the Digital and Insurtech Platforms segment is the fastest growing with a CAGR of 12.60% during 2026-2035.
- By Vehicle Age, the New Vehicles segment dominated the market with a 54.35% share in 2025, while the Used Vehicles segment is the fastest growing with a CAGR of 7.15% during 2026-2035.
By Coverage Type, Third-Party Liability Dominates the Market and Comprehensive Insurance Grows Fastest
Third-party liability dominated the market in 2025. This coverage type remains legally mandated across the overwhelming majority of jurisdictions worldwide, requiring essentially every vehicle owner to carry at least a minimum level of protection against liability for injury or property damage caused to others, and this near-universal legal requirement continues to anchor third-party liability as the clear largest coverage type category across the broader automotive insurance market.
Comprehensive insurance is projected to be the fastest-growing coverage type over the forecast period, as rising vehicle values and growing consumer awareness of the financial exposure theft, weather damage, and other non-collision events represent continues to drive demand for fuller protection beyond the legal minimum. Continued growth in vehicle ownership costs continues to make comprehensive coverage an increasingly common choice among owners of newer, higher-value vehicles.
By Vehicle Type, Passenger Cars Dominates the Market and Two-Wheelers Grows Fastest
Passenger cars dominated the market in 2025. The sheer global scale of passenger vehicle ownership continues to anchor this vehicle type as the overwhelming source of automotive insurance premium volume, reinforced by the near-universal requirement for liability coverage across passenger vehicles in most legal jurisdictions worldwide.
Two-wheelers are projected to be the fastest-growing vehicle type over the forecast period, as rising motorcycle and scooter ownership across rapidly urbanising emerging markets, particularly in Asia, continues to expand the insured two-wheeler population. Growing regulatory enforcement of mandatory coverage requirements for two-wheelers across several developing markets continues to drive above-market growth for this vehicle type relative to the broader passenger-car-dominated vehicle mix.
By Policy Type, Personal Auto Insurance Dominates the Market and Commercial Auto Insurance Grows Fastest
Personal auto insurance dominated the market in 2025. Individual vehicle owners purchasing coverage for personal use continue to represent the overwhelming majority of overall automotive insurance policy volume worldwide, reflecting the sheer scale of personal vehicle ownership relative to commercial fleet operations.
Commercial auto insurance is projected to be the fastest-growing policy type over the forecast period, as rising e-commerce-driven delivery fleet expansion and growing ride-hailing and logistics activity continue to expand the population of commercially insured vehicles. Continued growth in gig economy delivery and transportation services continues to drive above-market growth for this policy type relative to the broader personal-insurance-dominated policy mix.
By Distribution Channel, Agency and Broker Dominates the Market and Digital and Insurtech Platforms Grows Fastest
Agency and broker distribution dominated the market in 2025. Traditional agent-mediated sales continue to represent the largest single distribution channel, particularly for complex commercial and higher-value personal policies where customers value personalised guidance through coverage options and claims support that a purely digital channel does not always provide.
Digital and insurtech platforms are projected to be the fastest-growing distribution channel over the forecast period, as growing consumer comfort with purchasing insurance entirely online continues to favour direct-to-consumer digital platforms offering instant quotes and streamlined policy management. Rising insurtech competition, built around app-based telematics and simplified digital claims processes, continues to drive above-market growth for this channel relative to the broader agency-dominated distribution mix.
By Vehicle Age, New Vehicles Dominates the Market and Used Vehicles Grows Fastest
New vehicles dominated the market in 2025. Newer vehicles typically carry comprehensive coverage requirements tied to auto loan and lease financing agreements, and the higher replacement value these vehicles represent continues to command higher premium amounts per policy, sustaining new vehicles' position as the largest vehicle age category across the broader automotive insurance market.
Used vehicles are projected to be the fastest-growing vehicle age category over the forecast period, as rising used vehicle sales, driven by elevated new vehicle prices in many major markets, continue to expand the population of insured used vehicles. Continued growth in the used vehicle market worldwide continues to drive above-market growth for this vehicle age category relative to the broader new-vehicle-dominated age mix.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
79.85% |
|
Europe |
Germany |
23.45% |
|
Asia Pacific |
China |
34.20% |
|
Latin America |
Brazil |
22.75% |
|
Middle East & Africa |
United Arab Emirates |
20.15% |
North America Automotive Insurance Market Insights
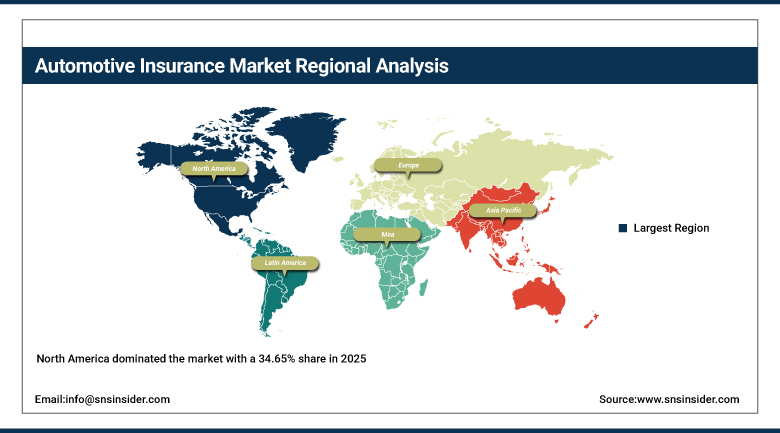
North America dominated the market with a 34.65% share in 2025. Near-universal legal mandates for liability coverage, a large vehicle parc, and the concentration of leading insurance carriers headquartered within the region continue to anchor this leadership position across every major coverage type and distribution channel category.
Canada contributes meaningful incremental regional demand through its own vehicle parc and comparable regulatory environment governing mandatory coverage. Continued telematics and AI-driven pricing innovation among leading carriers is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets developing across Asia Pacific.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Insurance Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 8.95%. Rising disposable incomes and expanding vehicle ownership across major regional economies, particularly China and India, continue to accelerate regional adoption of automotive insurance coverage as vehicle penetration continues to widen across previously underserved population segments.
The region’s demand is influenced by China’s role as the largest vehicle market in the world and a growing insurance industry in the country. The contribution made by India is mainly due to the increasing number of vehicles and increasing enforcement of compulsory insurance. The contribution from Japan and South Korea comes from advanced demand in automotive insurance.
Europe Automotive Insurance Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial automotive market and the region's mature, well-regulated insurance industry. The region's comprehensive mandatory coverage requirements and dense vehicle ownership continue to sustain steady demand across every major automotive insurance category.
The United Kingdom, France, and Italy add consistent regional demand as national insurance markets continue extending telematics and usage-based pricing innovation. Continued European regulatory attention to data privacy in insurance pricing is expected to shape how aggressively telematics-based products expand across the broader regional market through the forecast period.
MEA and Latin America Automotive Insurance Market Insights
The Middle East and Africa region is supported by growing vehicle ownership and expanding mandatory coverage enforcement across the United Arab Emirates and Saudi Arabia, where regional governments continue strengthening automotive insurance regulation as part of broader road safety and consumer protection initiatives.
Latin America is anchored by Brazil, where a substantial domestic vehicle parc sustains steady automotive insurance demand. Mexico contributes further incremental growth as regional vehicle ownership and mandatory coverage enforcement continue to expand across the broader region.
Growth Drivers: Rising Vehicle Sales and Technology-Driven Pricing Precision
Growth in sales of vehicles in all parts of the world can be cited as the key growth factor, in that ongoing growth in global production and ownership of vehicles is bound to increase the number of vehicles that need to be insured for both compulsory liability and voluntary coverages. The increasing cost of vehicles due to technological advances also serves to fuel this phenomenon.
Enhanced customer awareness regarding insurance products represents a second major driver, as growing consumer understanding of coverage options continues to drive uptake of comprehensive and add-on protection beyond basic legal minimums. Continued technological transformation, including telematics, artificial intelligence, and big data analytics, further reinforces sustained market growth by allowing insurers to price risk more precisely and profitably across an expanding range of customer segments.
Restraints: Rising Claims Costs and Data Privacy Concerns
Rising vehicle repair costs remain a genuine restraint on insurer profitability, as increasingly complex vehicle electronics and advanced driver assistance system components continue to push average claims severity higher, requiring insurers to raise premiums in ways that can strain affordability for price-sensitive policyholders and invite regulatory scrutiny.
Growing data privacy concerns present a further restraint, as telematics programs that track detailed driving behaviour continue to raise genuine consumer concern about how insurers collect, use, and potentially share this information, prompting several jurisdictions to introduce legislation restricting permissible telematics data use in ways that can complicate insurer pricing model design.
Opportunities: Usage-Based Insurance Expansion and Digital Distribution Growth
Continued expansion of usage-based and telematics-driven insurance products represents a substantial opportunity, as insurers that can deliver genuinely more precise, individually tailored pricing stand to capture demand from safe drivers seeking premium savings unavailable through traditional demographic-based underwriting alone.
Continued growth of digital and insurtech distribution channels offers a further avenue for growth, as insurers that can deliver genuinely seamless, fully digital policy purchase and claims experiences are positioned to capture demand from increasingly digital-native consumers who prefer managing insurance entirely through mobile apps and online portals rather than traditional agent-mediated channels.
Recent Developments
- 2026: Allstate advanced technology-enabled claims and auto-insurance operations, focusing on pricing, customer experience, and digital capabilities across its U.S. personal-property and casualty insurance businesses.
- 2026: USAA expanded its technology and customer-service initiatives across its insurance operations, with auto insurance remaining a core offering for military members, veterans, and eligible family members.
- 2026: Liberty Mutual advanced digital insurance capabilities and analytics across personal lines, supporting pricing, claims, and customer experiences within its U.S. auto-insurance operations.
Automotive Insurance Companies are:
- State Farm Mutual Automobile Insurance Company
- Berkshire Hathaway Inc. (GEICO)
- Progressive Corporation
- Allstate Insurance Company
- USAA
- Liberty Mutual Insurance Company
- Allianz SE
- AXA S.A.
- Zurich Insurance Group Ltd.
- China Pacific Insurance (Group) Co., Ltd.
- PICC Property and Casualty Company Limited
- Ping An Insurance (Group) Company of China, Ltd.
- Admiral Group plc
- Direct Line Insurance Group plc
- Tokio Marine Holdings, Inc.
- Sompo Holdings, Inc.
- MAPFRE S.A.
- Generali Group
- Nationwide Mutual Insurance Company
- Farmers Insurance Group
Automotive Insurance Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 909.48 Billion |
| Market Size by 2035 | USD 1,728.35 Billion |
| CAGR | CAGR of 6.63% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Coverage Type (Third-Party Liability, Collision Insurance, Comprehensive Insurance, Personal Injury Protection, Others) • By Vehicle Type (Passenger Cars, Commercial Vehicles, Two-Wheelers) • By Policy Type (Personal Auto Insurance, Commercial Auto Insurance) • By Distribution Channel (Agency and Broker, Direct, Digital and Insurtech Platforms) • By Vehicle Age (New Vehicles, Used Vehicles) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | State Farm Mutual Automobile Insurance Company, Berkshire Hathaway Inc. (GEICO), Progressive Corporation, Allstate Insurance Company, USAA, Liberty Mutual Insurance Company, Allianz SE, AXA S.A., Zurich Insurance Group Ltd., China Pacific Insurance (Group) Co., Ltd., PICC Property and Casualty Company Limited, Ping An Insurance (Group) Company of China, Ltd., Admiral Group plc, Direct Line Insurance Group plc, Tokio Marine Holdings, Inc., Sompo Holdings, Inc., MAPFRE S.A., Generali Group, Nationwide Mutual Insurance Company, Farmers Insurance Group |
Frequently Asked Questions
Key players include State Farm Mutual Automobile Insurance Company, Berkshire Hathaway Inc., Progressive Corporation, Allstate Insurance Company, and USAA, among other global insurance carriers.
Continued expansion of usage-based and telematics-driven insurance products and continued growth of digital and insurtech distribution channels represent the primary opportunities.
Growth is primarily driven by increasing vehicle sales worldwide, combined with enhanced customer awareness regarding insurance products and coverage options.
By Coverage Type, Third-Party Liability dominated the market with a 62.75% share in 2025, reflecting near-universal legal mandates across most global jurisdictions.
North America dominated the market with a 34.65% share in 2025, supported by near-universal legal mandates for liability coverage and a large vehicle parc.
