
Automotive Pressure Plates Market Report Scope & Overview:
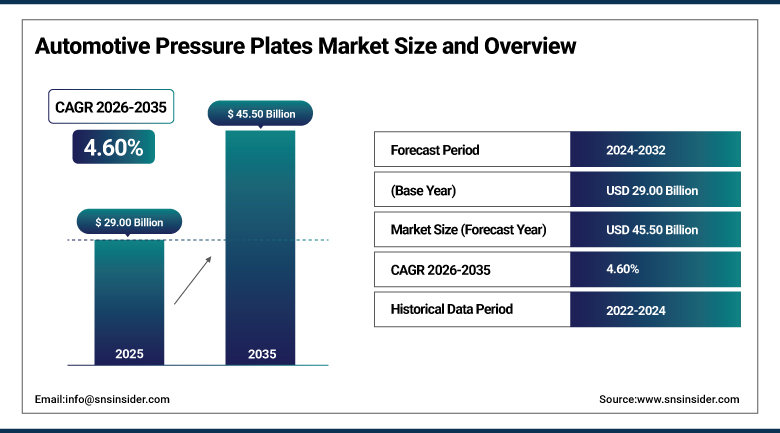
The Automotive Pressure Plates Market was valued at USD 29.00 Billion in 2025 and is expected to reach USD 45.50 Billion by 2035, growing at a CAGR of 4.60% from 2026–2035.
A pressure plate is the spring-loaded component in a friction clutch system that clamps the clutch disc against the engine's flywheel, transmitting engine power to the drivetrain whenever a driver releases the clutch pedal in a manual transmission vehicle. Pressure plates are used only with friction clutches, which may be single-plate, multi-plate, or cone designs, and are usually manufactured from either cast iron or stainless steel depending on the torque and durability requirements of the application. With the growth of the automotive industry across the globe, particularly sustained global vehicle production and the continued dominance of manual and automated manual transmissions in emerging automotive markets, demand for automotive pressure plates continues expanding steadily.
The aftermarket segment is becoming increasingly vital for the global automotive pressure plates market, since manual transmission clutch components wear through normal use and require periodic replacement over a vehicle's lifespan. As vehicles age, the demand for replacement parts, including pressure plates, rises substantially, and this aftermarket dynamic is proving particularly durable even as automakers in developed markets continue shifting new vehicle production toward automatic and dual-clutch transmissions that don't rely on traditional friction pressure plates.
To Get more information Automotive Pressure Plates Market - Request Free Sample Report
Automotive Pressure Plates Market Trends
-
Rising demand for lightweight and robust pressure plate materials as manufacturers balance durability against fuel-efficiency requirements
-
Growing development of innovative clutch systems, including Dual Clutch Transmissions, fueled by consumer demand for fuel-efficient vehicles
-
Increasing sustained replacement demand for clutch components in manual and automated manual transmission vehicles across emerging markets
-
Rising adoption of supportive industrial policies promoting localized automotive manufacturing, strengthening domestic OEM production capacity
-
Growing preference for multi-plate and cone clutch designs in high-torque commercial vehicle and performance vehicle applications
-
Expanding aftermarket distribution through e-commerce platforms, simplifying clutch component sourcing for independent repair shops
U.S. Automotive Pressure Plates Market Outlook
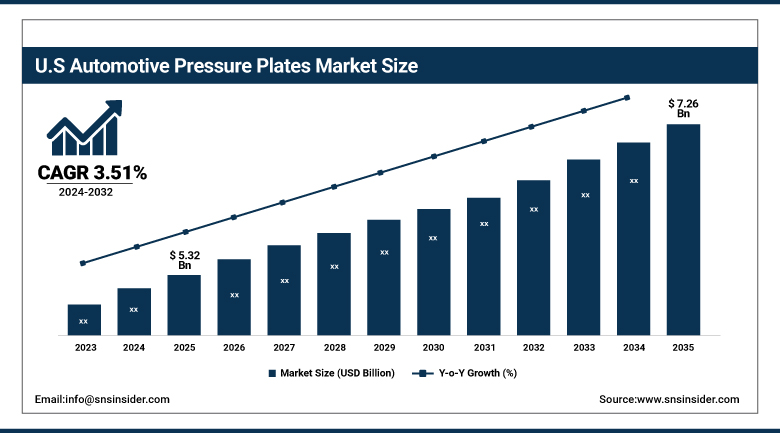
The U.S. Automotive Pressure Plates Market was valued at approximately USD 5.32 Billion in 2025 and is expected to reach approximately USD 7.26 Billion by 2035, growing at a CAGR of approximately 3.51%.
The United States’ market is advantaged by the strength of the commercial vehicle industry and consistent need for replacements within an older vehicle fleet, despite the ongoing preference of automatic transmission over manual clutches within the domestic production of new passenger vehicles. The increasing registration of vehicles and expansion of capacity to manufacture results in the need for clutch kits for passenger vehicles, commercial vehicles, and special vehicles using manual or automated manual transmissions. Increased demand for more durable and reliable trucks in commercial trucking activities is resulting in the emphasis of robust pressure plates among domestic producers.
According to industry analysis, the top five companies in the global automotive pressure plates market, including Eaton Corporation and Schaeffler AG's LuK brand, together hold roughly 40% of overall market share, with more than 20 companies actively engaged in production worldwide. That concentration among a handful of established suppliers reflects how much specialized engineering expertise and manufacturing precision a pressure plate genuinely requires: unlike many commodity automotive components, getting spring tension and clamping force exactly right across thousands of engagement cycles is a harder problem than it looks from the outside.
Automotive Pressure Plates Market Segment Analysis
-
By Product Type, the Diaphragm Pressure Plates segment dominated the Automotive Pressure Plates Market with approximately 55.00% share in 2025, while the Coil Spring/Others segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Clutch Type, the Single Plate Clutch segment dominated the Automotive Pressure Plates Market with approximately 50.00% share in 2025, while the Multi-Plate Clutch segment is the fastest growing with a CAGR of approximately 6.40%.
-
By Material, the Cast Iron segment dominated the Automotive Pressure Plates Market with approximately 58.60% share in 2025, while the Stainless Steel segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Pressure Plates Market with approximately 62.40% share in 2025, while the Heavy Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.90%.
-
By Distribution Channel, the OEM segment dominated the Automotive Pressure Plates Market with approximately 64.20% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.20%.
By Product Type, Diaphragm dominates, Coil Spring/Others grows fastest
Diaphragm pressure plates held the largest share of the product-type segment in 2025, supported by compact packaging, smoother release behavior, lower pedal effort, and broad fitment across passenger cars and light commercial vehicles. That combination of driver comfort and manufacturing compatibility keeps diaphragm designs the dominant product category across the broader automotive pressure plates market, particularly for the high-volume passenger vehicle segment.
Coil spring and other specialized pressure plate designs are growing fastest as heavy-duty commercial and performance applications continue requiring the higher, more linear clamping force these designs can deliver under sustained high-torque conditions. Growing demand for enhanced durability and reliability in commercial operations continues reinforcing this above-average growth trajectory relative to the broader, diaphragm-dominated product mix.
By Clutch Type, Single Plate dominates, Multi-Plate grows fastest
Single plate clutch systems held the largest share of the clutch-type segment in 2025, remaining the standard configuration across the overwhelming majority of passenger vehicles and light commercial vehicles produced worldwide, where a single friction disc provides sufficient torque capacity for typical driving conditions. That broad applicability keeps single plate clutches the dominant clutch-type category across the broader pressure plates market.
Multi-plate clutch systems are growing fastest as high-torque commercial vehicle and performance vehicle applications increasingly require the additional friction surface area multiple clutch plates provide to transmit greater engine power without excessive wear. Growing commercial vehicle demand and rising performance vehicle production continue reinforcing this above-average growth trajectory relative to the broader, single-plate-dominated clutch-type mix.
By Material, Cast Iron dominates, Stainless Steel grows fastest
Cast iron accounted for the highest revenue share in the material segment in 2025 owing to its high cost efficiency, heat resistance, and proven durability based on years of experience in clutch systems production. This combination of cost efficiency and good performance attributes sustains the position of cast iron as the material of choice within the wider automotive pressure plates industry especially in normal car models.
Stainless steel will continue to record the highest growth rate due to the advantages that it holds over cast iron such as good corrosion resistance and low weight, especially in the premium class of cars. The increasing demand by consumers for comfort and performance will keep sustaining this higher than average growth rate compared to the overall material mix.
By Vehicle Type, Passenger Vehicles dominates, Heavy Commercial Vehicles grows fastest
Passenger vehicles accounted for the largest share of the vehicle-type segment in 2025, driven by the high volumes of production and sales within this category, since every manual transmission passenger car requires a pressure plate as an essential clutch system component. That production and sales scale keeps passenger vehicles the dominant vehicle-type category across the broader automotive pressure plates market.
Heavy commercial vehicles are growing fastest, fueled by the rise in freight and logistics activities globally and the demand for enhanced durability and reliability in commercial operations. Manufacturers continue focusing on robust pressure plate solutions that can withstand intensive usage conditions, reinforcing this above-average growth trajectory relative to the broader, passenger-vehicle-dominated vehicle-type mix.
By Distribution Channel, OEM dominates, Aftermarket grows fastest
OEM sales held the largest share of the distribution-channel segment in 2025, remaining significant given direct supply relationships during vehicle assembly, with OEMs continuing to hold significant share and anticipated to grow at a healthy pace as global vehicle production continues expanding. That deep integration between pressure plate specification and overall vehicle powertrain engineering keeps OEM channels the dominant distribution pathway.
The aftermarket is growing fastest, becoming increasingly vital for the global automotive pressure plates market as vehicles age and the demand for replacement parts rises substantially across the existing global vehicle parc. Booming aftermarket demand, combined with growing e-commerce distribution channels, continues reinforcing this above-average growth trajectory relative to the broader, OEM-dominated distribution-channel mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.60% |
|
North America |
United States |
79.80% |
|
Europe |
Germany |
25.40% |
|
Latin America |
Brazil |
34.60% |
|
Middle East & Africa |
UAE |
29.40% |
Asia Pacific Automotive Pressure Plates Market Insights
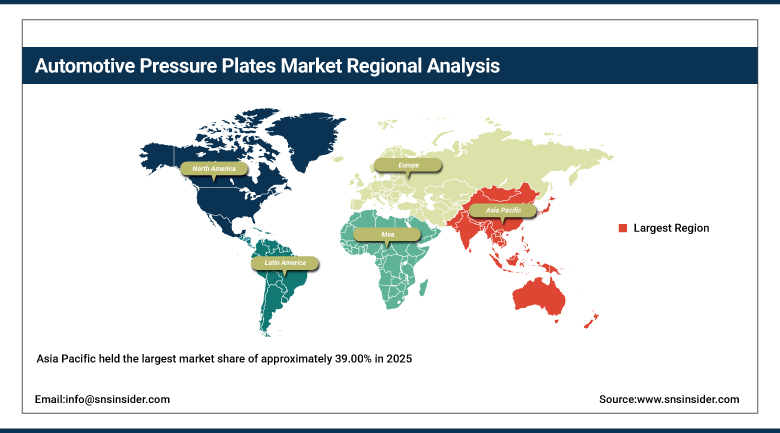
Asia Pacific held the largest market share of approximately 39.00% in 2025, driven by its extensive automotive manufacturing base in countries such as China, India, Japan, and South Korea, and is also expected to register the fastest regional growth through 2035. Growing automotive production across the region, combined with strong aftermarket sales tied to a large and aging vehicle parc, continues reinforcing this leading and accelerating position.
China's massive vehicle production base gives the region substantial baseline demand, while India's rapidly expanding automotive manufacturing sector is drawing significant new investment in clutch component production capacity. Japan and South Korea represent more mature, technology-forward markets with established manufacturing standards, while Southeast Asian markets continue following a similar vehicle-production-driven growth trajectory as regional manufacturing infrastructure expands.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Pressure Plates Market Insights
The North America region is a significant market for automotive pressure plates, owing to robust commercial vehicles demand and high replacement rates on account of a mature domestic vehicle base. The US holds a significant share of the market in the region, with high vehicle registration numbers and increasing manufacturing capabilities in the domestic automobile industry.
In addition, the Canadian and Mexican markets are expected to register significant growth on account of the commercial vehicles market in Canada and increasing investments in automotive manufacturing due to nearshoring. Supply chains involving all three countries bind much of the demand from the region.
Europe Automotive Pressure Plates Market Insights
Europe is characterized by a technically developed pressure plates market for automobiles due to stringent emission norms that consistently push the automobile manufacturers towards advanced clutches and transmissions that save fuel. Germany is a key regional driver as it is a country where there is significant automobile manufacturing along with some advanced providers of clutch components.
There are contributions from France and Italy also in terms of volumes since they have significant automotive manufacturing segments that have adapted themselves to EU emission and fuel economy requirements. The use of lightweight components and Dual Clutch Transmission systems is becoming increasingly important in Europe.
MEA & Latin America Automotive Pressure Plates Market Insights
The Middle East and Africa represent a smaller but strategically developing automotive pressure plates market, with the UAE driving demand through growing vehicle sales and automotive retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader automotive manufacturing and vehicle ownership infrastructure development.
Latin America is a growing market led by Brazil, where expanding vehicle production and continued reliance on manual transmission vehicles continue driving demand for automotive pressure plates. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing automotive manufacturing sectors.
Market Dynamics
Growth Drivers: Rising vehicle production and sustained replacement demand fueling adoption
Growing adoption of advanced automotive technologies due to increasing vehicle production is a major market driver, as rising global vehicle output continues expanding demand for clutch systems across OEM and aftermarket channels alike. Higher vehicle registrations and expanding manufacturing capacities continue driving procurement of clutch assemblies for passenger cars, commercial vehicles, and two-wheelers across nearly every major automotive market.
Sustained replacement demand for clutch components adds a second major driver, as the continued dominance of manual and automated manual transmissions in emerging automotive markets keeps generating consistent aftermarket procurement needs. Supportive industrial policies promoting localized automotive manufacturing continue strengthening both OEM production and long-term aftermarket replacement demand across developing economies specifically.
Restraints: Transmission electrification shift and raw material cost volatility limiting long-term demand
The gradual shift toward automatic, dual-clutch, and electric vehicle drivetrains remains a genuine long-term restraint, since these architectures either eliminate the traditional friction pressure plate entirely or replace it with fundamentally different clutch engagement technology. That structural shift is particularly pronounced in developed markets where automatic transmission penetration continues rising steadily across new vehicle production.
Raw material price volatility adds a further restraint, since pressure plate manufacturers depend on cast iron and stainless steel inputs that remain exposed to broader commodity market swings affecting production costs across the industry. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-component demand remains steady.
Opportunities: Emerging market manual transmission demand and complete clutch kit expansion opening new growth avenues
The consistent use of manual and semi-automatic transmissions in new car markets provides automakers a true opportunity of acquiring lasting business as the developing countries keep preferring cars equipped with manual transmissions because of their relatively low price and less complicated maintenance in comparison with automatic transmissions. Automakers capable of establishing their presence in these regions through effective manufacturing and distribution will benefit greatly.
Complete clutch kit expansion represents a second significant opportunity, as bundling pressure plates with clutch discs, release bearings, and related components into a single service package expands service value for aftermarket customers and repair shops. Manufacturers that build genuine complete-kit capability are positioned to capture premium pricing from customers seeking simplified, one-stop clutch system replacement.
Recent Developments:
-
In 2025, Eaton Corporation continued expanding its clutch and pressure plate product portfolio to serve growing commercial vehicle demand across emerging markets.
-
In 2025, Schaeffler AG's LuK brand continued advancing lightweight pressure plate technology, targeting improved fuel efficiency for manual transmission vehicles.
-
In 2025, Valeo Service continued expanding its aftermarket clutch component distribution network, focusing on complete clutch kit offerings for independent repair shops.
-
In 2025, multiple regional manufacturers across India and China continued expanding production capacity to serve growing domestic commercial vehicle and two-wheeler clutch component demand.
Automotive Pressure Plates Market Key Players
-
MACAS Automotive
-
Hebei Tengda Auto Parts
-
K26 S.K. Auto Industries
-
Setco Automotive Ltd.
-
ANAND Group
-
Raicam Clutch
-
Makino Auto Industries
-
SASSONE
-
GOLDEN Precision Prod.
-
Eaton Corporation plc
-
F.C.C. Co., Ltd.
-
Tieliu Co., Ltd. (Westlake)
-
Schaeffler AG (LuK)
-
Valeo Service SAS (Valeo)
-
Exedy Corporation
-
Sachs (ZF Aftermarket)
-
Aisin Corporation
-
Kennedy Engineered Products
-
Centerforce Clutches, Inc.
-
South Bend Clutch, Inc.
Automotive Pressure Plates Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 29.00 Billion |
| Market Size by 2035 | USD 45.50 Billion |
| CAGR | CAGR of 4.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Diaphragm Pressure Plates, Coil Spring Pressure Plates, Others) • by Clutch Type (Single Plate Clutch, Multi-Plate Clutch, Cone Clutch) • by Material (Cast Iron, Stainless Steel, Others) • by Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles) • by Distribution Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | MACAS Automotive, Hebei Tengda Auto Parts, K26 S.K. Auto Industries, Setco Automotive Ltd., ANAND Group, Raicam Clutch, Makino Auto Industries, SASSONE, GOLDEN Precision Prod., Eaton Corporation plc, F.C.C. Co., Ltd., Tieliu Co., Ltd. (Westlake), Schaeffler AG (LuK), Valeo Service SAS (Valeo), Exedy Corporation, Sachs (ZF Aftermarket), Aisin Corporation, Kennedy Engineered Products, Centerforce Clutches, Inc., South Bend Clutch, Inc. |
Frequently Asked Questions
Leading companies include Eaton Corporation plc, Schaeffler AG (LuK), Valeo Service SAS, F.C.C. Co., Ltd., and ANAND Group, among other major clutch component manufacturers.
Opportunities include sustained manual and automated manual transmission demand across emerging automotive markets and complete clutch kit expansion for aftermarket and repair shop customers.
Growth is driven by growing adoption of advanced automotive technologies due to increasing vehicle production and sustained replacement demand for clutch components across emerging markets.
Diaphragm Pressure Plates dominates by product type with approximately 55.00% share, Single Plate Clutch dominates by clutch type with roughly 50.00% share, Cast Iron dominates by material with about 58.60% share, and Passenger Vehicles dominates by vehicle type with approximately 62.40% share; Coil Spring/Others, Multi-Plate Clutch, Stainless Steel, and Heavy Commercial Vehicles are the fastest-growing segments within their respective categories.
Asia Pacific is the largest regional market with approximately 39.00% share, led by China, and is also the fastest-growing region through 2035.
