
Automotive Wheel Rims Market Report Scope & Overview:
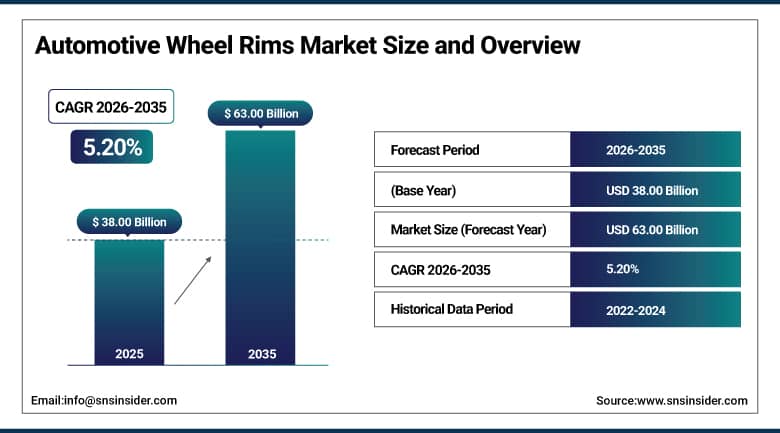
The Automotive Wheel Rims Market was valued at USD 38.00 Billion in 2025 and is expected to reach USD 63.00 Billion by 2035, growing at a CAGR of 5.20% from 2026–2035.
Wheel rims are the essential structural components that keep a tire aligned and its air pressure constant while balancing the vehicle's weight against every force applied to it during operation, meaning they have to be strong enough to withstand these forces without adding unnecessary mass. The growing demand for lightweight materials as a result of increased fuel efficiency continues driving the market, since aluminum and alloy wheels reduce unsprung mass and improve fuel economy relative to traditional steel construction. Growing preference of vehicle owners for personalized vehicle appearance and performance, combined with rising automotive production and increasing disposable income in developing countries, continues expanding demand across nearly every vehicle segment.
Maxion Wheels, the world's largest wheel manufacturer, announced at SOLUTRANS 2025 that serial production of its new forged aluminum truck wheels will begin in January 2026 at a newly built plant in Manisa, Türkiye, a joint investment exceeding $150 million with local partner İnci Holding. The facility starts with capacity for roughly 350,000 forged aluminum wheels annually, with room to double that in the years ahead, and it rounds out what the company calls the industry's most comprehensive commercial vehicle wheel portfolio, spanning both steel and forged aluminum from a single supplier rather than forcing fleet operators to source different wheel types from different manufacturers.
To Get More Information On Automotive Wheel Rims Market - Request Free Sample Report
Automotive Wheel Rims Market Trends:
-
Accelerating shift from steel to aluminum alloy rims as automakers prioritize weight reduction to offset heavy EV battery packs and extend driving range
-
Growing consumer preference for larger rim sizes, particularly 19 inch and above, reflecting rising SUV and premium vehicle popularity
-
Rising adoption of carbon fiber wheels in sports cars and high-performance vehicles, valued for exceptional lightweight and strength properties
-
Expanding forged aluminum wheel production for commercial vehicles, offering fleet operators improved payload capacity and fuel efficiency
-
Increasing e-commerce penetration in aftermarket wheel sales, simplifying rim selection and purchase for end users through tire-and-wheel packages
-
Growing customization demand in the alloy wheel segment as consumers seek distinctive designs and finishes for personal vehicle expression
U.S. Automotive Wheel Rims Market Outlook:
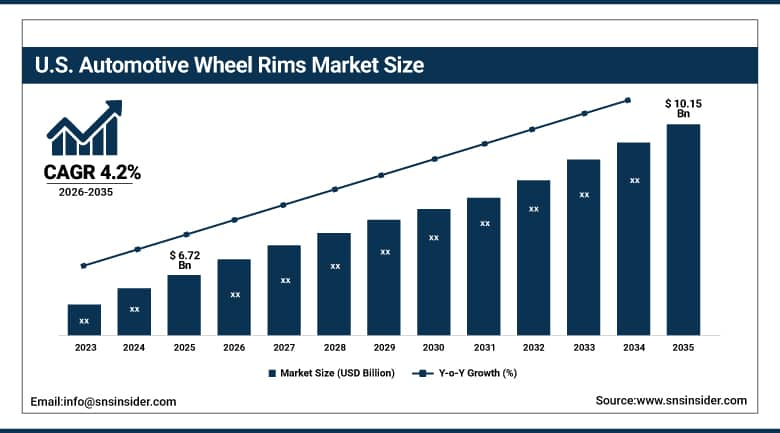
The U.S. Automotive Wheel Rims Market was valued at approximately USD 6.72 Billion in 2025 and is expected to reach approximately USD 10.15 Billion by 2035, growing at a CAGR of approximately 4.2%.
The U.S. market benefits from a surge in demand for sports cars and increasing customer preference for aftermarket styling, alongside a well-established domestic automobile industry seeing renewed energy through penetration of innovative materials like carbon fiber and aluminum alloys. Increased car ownership levels and EV sales growth continue driving rim demand, particularly as automakers increasingly rely on aluminum wheels to counterbalance battery mass, extend range, and optimize aerodynamic performance across expanding electric passenger and light truck platforms. The workshop and aftermarket segment continues growing steadily, driven by a mature vehicle fleet and consumer trends toward personalization.
Superior Industries International, headquartered in Southfield, Michigan, remains one of the world's leading aluminum wheel suppliers to North American and European automakers, supplying OEM factory-installed wheels for new light vehicles as well as European aftermarket brands including ATS, RIAL, ALUTEC, and ANZIO. The broader North American aluminum wheel market was valued at $9.6 billion in 2025 and is projected to reach $17 billion by 2035, growth fueled specifically by accelerating electric vehicle adoption, since automakers increasingly rely on lightweight aluminum wheels to counterbalance heavy battery packs and extend driving range.
Automotive Wheel Rims Market Segment Analysis:
-
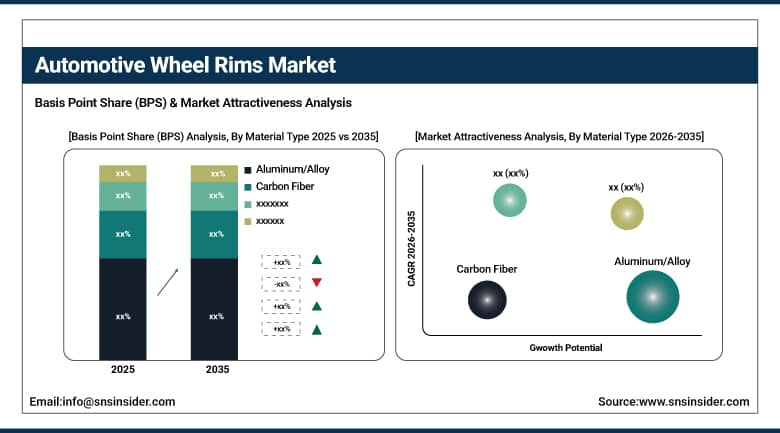
By Material Type, the Aluminum/Alloy segment dominated the Automotive Wheel Rims Market with approximately 48.10% share in 2025, while the Carbon Fiber segment is the fastest growing with a CAGR of approximately 9.80%.
-
By Manufacturing Process, the Casting segment dominated the Automotive Wheel Rims Market with approximately 67.40% share in 2025, while the Forging segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Rim Size, the 16–18 inch segment dominated the Automotive Wheel Rims Market with approximately 39.60% share in 2025, while the 19 inch and Above segment is the fastest growing with a CAGR of approximately 7.90%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Wheel Rims Market with approximately 69.70% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Sales Channel, the OEM segment dominated the Automotive Wheel Rims Market with approximately 69.90% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 7.40%.
By Material Type, Aluminum/Alloy dominates, Carbon Fiber grows fastest
Aluminum and alloy wheels dominated the material type segment in 2025 as the wheels had the benefit of being lightweight as compared to their conventional counterparts made from steel owing to the high strength-to-weight ratio and attractive features of the material. They were light in weight and facilitated ease of handling thus suited the small cars as well as sedans and the lighter weight reduced the unsprung weight leading to efficient fuel consumption and cost savings, keeping aluminum dominant in material category.
The fastest growth was expected in case of carbon fiber due to increasing use of lightweight materials possessing favorable properties for manufacturing rims for sports and performance cars. Heavy weight of conventional wheel material led to greater fuel consumption thus impeding the growth of the market and the superiority in weight continued to contribute to the above average growth trend.
By Manufacturing Process, Casting dominates, Forging grows fastest
Casting held the largest share of the manufacturing-process segment in 2025, enabling scalable manufacturing at lower production costs that make this process well-suited for high-volume passenger vehicles and light-duty platforms across nearly every automotive market. That cost efficiency and production scalability keep casting the dominant manufacturing process across the broader automotive wheel rims market.
Forging is growing fastest as this process delivers a perfectly concentric, true-running wheel that minimizes vibration and maximizes ride quality, properties increasingly valued in premium and performance vehicle segments and commercial truck applications alike. Forged aluminum wheels are significantly lighter than steel wheels due to the material's low density, and growing commercial vehicle demand for lightweight, durable wheel solutions continues reinforcing this above-average growth trajectory.
By Rim Size, 16–18 inch dominates, 19 inch and Above grows fastest
Rims in the 16 to 18 inch range captured the largest share of the rim-size segment in 2025, matching the standard wheel diameter most commonly specified across mainstream sedans, crossovers, and compact vehicles produced worldwide. That broad compatibility with the most common vehicle platforms currently in production keeps this rim-size range the default specification most manufacturers produce at the highest volume.
Rims measuring 19 inches and above are growing fastest, indicating a strong preference for larger rims as SUVs, crossovers, and premium vehicles continue gaining market share relative to traditional sedans. Growing electric vehicle production, which often specifies larger rim diameters to manage the added weight and torque characteristics of battery-powered platforms, continues reinforcing this above-average growth trajectory relative to the broader, mid-size-rim-dominated market.
By Vehicle Type, Passenger Vehicles dominates, Commercial Vehicles grows fastest
Passenger vehicles had the largest share in the vehicle type category in 2025 due to the fact that the volume of manufacture and sales of passenger vehicles is much greater than the volume of manufacture of commercial vehicles in any particular year. This allows passenger vehicles to remain the major vehicle type category in the total wheel rim market.
Commercial vehicles are experiencing the highest growth rates in terms of the increasing investments in forging aluminum and light steel wheel rims that provide enhanced load-carrying capacity and fuel efficiency. The increasing volume of freight transportations and development of the international logistics networks are further contributing to this growth trend in comparison with other vehicle types.
By Sales Channel, OEM dominates, Aftermarket grows fastest
OEM sales commanded the majority share of the sales-channel segment in 2025, reflecting how wheel rims are overwhelmingly factory-installed components specified during vehicle design and assembly rather than purchased separately by the typical new vehicle buyer. That deep integration between rim design and overall vehicle engineering keeps OEM channels the dominant distribution pathway across nearly every wheel rim category.
The aftermarket is growing fastest as the workshop segment continues growing, especially in Europe and North America, driven by a mature vehicle fleet and consumer trends toward personalization. Increased penetration of e-commerce platforms and the convenience provided by tire-and-wheel packages have made rim selection and purchase easier for end users, further facilitating this above-average growth trajectory relative to the broader, OEM-dominated sales-channel mix.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.60% |
|
North America |
United States |
80.40% |
|
Europe |
Germany |
26.20% |
|
Latin America |
Brazil |
34.80% |
|
Middle East & Africa |
UAE |
29.20% |
Asia Pacific Automotive Wheel Rims Market Insights
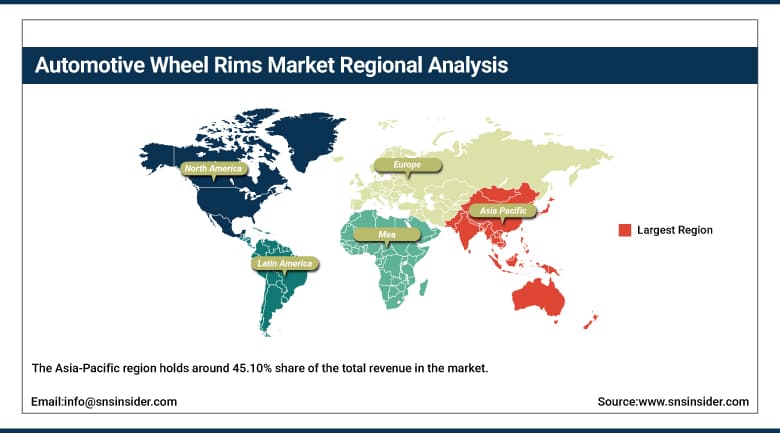
The Asia-Pacific region holds around 45.10% share of the total revenue in the market due to the contribution made by China and India through manufacturing tens of millions of passenger cars each year, and it is also the fastest growing region because of the increased disposable income in Southeast Asia and India that is fast moving towards alloy wheels from steel wheels. With the increasing requirement for cars with high power and high efficiency, there is also an increase in the use of lightweight automotive wheel rims in this region.
A large vehicle manufacturing capacity in China provides this region with a lot of basic demand for wheel rims along with domestic companies such as CITIC Dicastal that have unique advantages in terms of global scale and integration within Chinese and international OEMs. The growing automotive manufacturing in India is attracting major investments in wheel rims manufacturing capacity.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Automotive Wheel Rims Market Insights
Europe holds the second-largest position with roughly a 28% share, supported by premium OEM specification trends in Germany and Italy that continue favoring alloy and forged wheel construction across the region's luxury and performance vehicle segments. Germany anchors regional demand, home to a large automotive manufacturing base and several major wheel manufacturers with deep engineering expertise.
Italy and France contribute meaningful volume as well, each with substantial premium and performance vehicle manufacturing sectors that continue driving demand for advanced alloy and carbon fiber wheel technology. Growing regional emphasis on lightweight materials to improve fuel efficiency and reduce vehicular emissions continues shaping product development across the region more directly than in most other global markets.
North America Automotive Wheel Rims Market Insights
North America is the third-largest region accounting for approximately 22%, but it has the greatest aftermarket spending on wheels per vehicle due to high consumer demand for styling and performance enhancements in wheels. The bulk of North American demand comes from the United States as a result of increased demand for sports cars and aftermarket styling preferences.
Canada brings extra demand to the equation due to its own automobile production and use of steel wheels in cold climates. Additionally, Mexico's market size is constantly increasing due to the increase in automotive production investments in Mexico. Geographical proximity is responsible for the ties of the wheel market within the region as leading wheel manufacturers usually serve all three countries.
MEA & Latin America Automotive Wheel Rims Market Insights
The Middle East and Africa represent a smaller but strategically developing automotive wheel rims market, with the UAE driving demand through growing vehicle sales and premium automotive retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader automotive manufacturing and vehicle ownership infrastructure development.
Latin America is a growing market led by Brazil, where expanding vehicle production and rising consumer preference for enhanced vehicle appearance and performance continue driving wheel rim adoption. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing automotive manufacturing sectors.
Market Dynamics:
Growth Drivers: Lightweighting demand and rising vehicle production fueling adoption
Increasing demand for lightweight automotive parts is one of the clearest forces behind rising automotive wheel rims demand, as the growing demand for lightweight vehicles as a result of increased fuel efficiency continues driving the market across nearly every vehicle segment worldwide. That structural shift toward lighter, more fuel-efficient vehicle components gives the market a demand base tied directly to broader automotive engineering priorities.
Rising production of vehicles adds a second major driver, alongside rising preferences of luxury car owners for rims with various designs and increasing disposable income that continues expanding the addressable market for premium and customized wheel options. Increased R&D activities by OEMs, combined with growing preference of vehicle owners for more silent and environmentally friendly vehicles, continue reinforcing this demand base.
Restraints: Raw material price volatility and manufacturing complexity limiting margin stability
Raw material price volatility remains a genuine restraint, since wheel rim manufacturers depend on aluminum, steel, and increasingly carbon fiber inputs that remain exposed to broader commodity market swings affecting production costs across the industry. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-rim demand remains steady.
Manufacturing complexity for forged and carbon fiber wheels adds a further restraint, since these premium manufacturing processes require substantially higher capital investment and quality control than conventional casting, limiting how quickly smaller manufacturers can scale premium wheel production. That technical and capital barrier continues favoring established, well-capitalized manufacturers in the premium wheel segment specifically.
Opportunities: EV-driven lightweighting and premium customization opening new growth avenues
Lightweighting through EV technology presents a true opportunity for manufacturers to gain the premium business of automotive firms that are looking for aluminum and carbon fiber wheels that offset battery weights and add range for electric vehicle production platforms that are growing increasingly popular. For firms that create true wheel engineering expertise for their electric vehicles, there is a great potential for disproportionate gains from the acceleration of electric vehicle production in the global market.
Premium after-market customizations constitute another important opportunity due to the penetration of ecommerce channels by customers who are becoming more interested in customized wheels beyond the standard products offered by OEMs. Firms that create true ecommerce customization capabilities will have access to premium pricing from consumers who want to customize their vehicles.
Recent Developments:
-
In November 2025, Maxion Wheels announced at SOLUTRANS 2025 that preparations were complete for serial production of forged aluminum truck wheels at its new Manisa, Türkiye facility.
-
In 2025, Maxion Wheels continued developing a new patented surface treatment solution for forged aluminum truck wheels, targeting enhanced durability, corrosion protection, and easier maintenance.
-
In 2025, Maxion Wheels expanded its forged aluminum truck wheel portfolio into South America, extending its commercial vehicle wheel solutions beyond its original European and Turkish manufacturing base.
-
In 2025, CITIC Dicastal continued leveraging its global scale and deep integration with Chinese and international OEMs, maintaining market leadership with more than 11.5% global share through advanced casting and forging capabilities.
Automotive Wheel Rims Market Key Players:
-
Maxion Wheels
-
Superior Industries International, Inc.
-
Enkei Corporation
-
Ronal Group
-
Borbet GmbH
-
CITIC Dicastal Co., Ltd.
-
BBS Kraftfahrzeugtechnik AG
-
Topy Industries, Ltd.
-
Momo Srl
-
Steel Strips Wheels Ltd.
-
SMW Engineering Sdn. Bhd.
-
ROH Wheels
-
YHI International Ltd.
-
Mangels Industrial S.A.
-
Kosei Aluminum Co., Ltd.
-
Zhejiang Wanfeng Auto Wheel Co., Ltd.
-
Accuride Corporation
-
Alcoa Wheel Products (Alcoa Corporation)
-
HRE Performance Wheels
-
Vossen Wheels
Automotive Wheel Rims Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 38.00 Billion |
| Market Size by 2035 | USD 63.00 Billion |
| CAGR | CAGR of 5.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Aluminum/Alloy, Steel, Carbon Fiber) • by Manufacturing Process (Casting, Forging, Others) • by Rim Size (Below 16 inch, 16–18 inch, 19 inch and Above) • by Vehicle Type (Passenger Vehicles, Commercial Vehicles) • by Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Maxion Wheels, Superior Industries International, Inc., Enkei Corporation, Ronal Group, Borbet GmbH, CITIC Dicastal Co., Ltd., BBS Kraftfahrzeugtechnik AG, Topy Industries, Ltd., Momo Srl, Steel Strips Wheels Ltd., SMW Engineering Sdn. Bhd., ROH Wheels, YHI International Ltd., Mangels Industrial S.A., Kosei Aluminum Co., Ltd., Zhejiang Wanfeng Auto Wheel Co., Ltd., Accuride Corporation, Alcoa Wheel Products (Alcoa Corporation), HRE Performance Wheels, Vossen Wheels |
Frequently Asked Questions
Leading companies include Maxion Wheels, Superior Industries International, Inc., Enkei Corporation, Ronal Group, and Borbet GmbH, among other major wheel manufacturing and forging companies.
Opportunities include EV-driven lightweighting counterbalancing heavy battery packs and extending driving range, and premium aftermarket customization through expanding e-commerce distribution channels.
Growth is driven by increasing demand for lightweight automotive parts, rising production of vehicles, and growing preferences of luxury car owners for rims with various designs.
Aluminum/Alloy dominates by material type with approximately 48.10% share, Casting dominates by manufacturing process with roughly 67.40% share, 16–18 inch dominates by rim size with about 39.60% share, and Passenger Vehicles dominates by vehicle type with approximately 69.70% share; Carbon Fiber, Forging, 19 inch and Above, and Commercial Vehicles are the fastest-growing segments within their respective categories.
Asia Pacific is the largest regional market with approximately 45.10% share, led by China, and is also the fastest-growing region through 2035.
