
Autonomous AI and Autonomous Agents Market Report Scope & Overview:
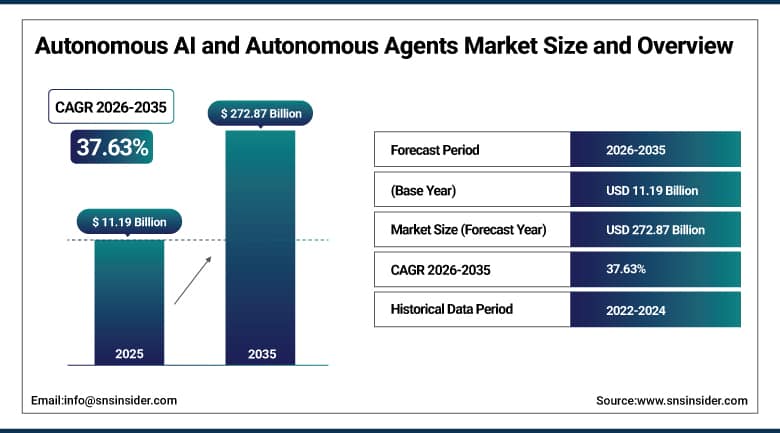
The Autonomous AI and Autonomous Agents Market was valued at USD 11.19 Billion in 2025 and is expected to reach USD 272.87 Billion by 2035, growing at a CAGR of 37.63% from 2026-2035.
The Autonomous AI and Autonomous Agents Market is expanding at a pace that few enterprise software categories have matched, as organizations move from conversational assistants toward systems that plan, call tools and complete multi-step work with limited supervision. Demand is concentrated in customer service, IT operations, software engineering, finance and supply chain. Vendors are investing in orchestration layers, memory, identity controls and open protocols so that agents from different providers can work together. Growth is reinforced by falling inference costs, broader model capability and the arrival of governance frameworks that give risk teams a defined path to approval. North America leads current spending, while Asia Pacific is advancing fastest on the strength of public-sector programs and large developer communities.
⮞In December 2025, the Linux Foundation reported that more than 10,000 MCP servers had been published when it formed the Agentic AI Foundation. The ecosystem milestone shows how quickly shared connection standards are expanding the toolset available to autonomous agents.
To Get More Information On Autonomous AI and Autonomous Agents Market - Request Free Sample Report
Autonomous AI and Autonomous Agents Market Trends
-
Multi-agent architectures are replacing single assistants for end-to-end business workflows.
-
Open protocols for tool access and agent-to-agent communication are lowering integration cost.
-
Agent identity, permissioning and audit logging are becoming standard enterprise requirements.
-
Vertical agents for banking, healthcare, legal and software engineering are gaining enterprise budgets.
-
Governments are publishing agent-specific standards and national adoption targets.
U.S. Autonomous AI and Autonomous Agents Market Outlook
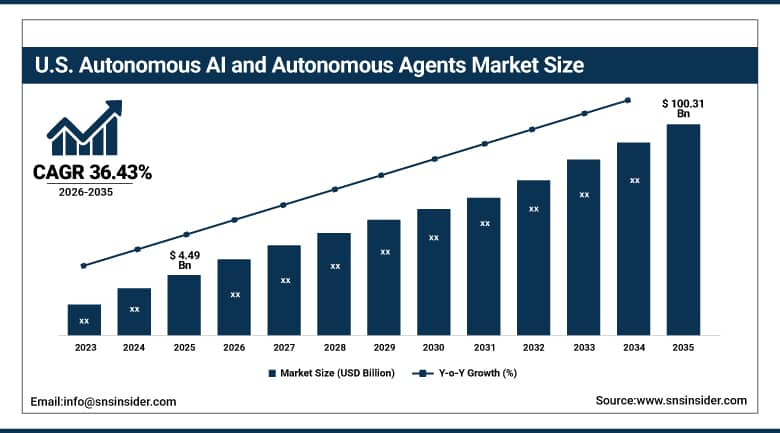
The U.S. Autonomous AI and Autonomous Agents Market was valued at USD 4.49 Billion in 2025 and is expected to reach USD 100.31 Billion by 2035, growing at a CAGR of 36.43% from 2026-2035.
The U.S. Autonomous AI and Autonomous Agents Market benefits from the presence of the leading model developers, hyperscale cloud providers and enterprise software vendors, which allows new agent products to reach large customer bases within months of release. Financial institutions, technology firms, healthcare systems and retailers are funding pilots that have moved into production for service desks, coding and claims handling. Federal and state agencies are evaluating agents for benefits processing and citizen services, while procurement teams demand audit trails and security attestations. Venture funding continues to support specialized startups that sell agents by function or by industry. U.S. enterprises also lead in appointing executives responsible for agent governance, which shortens approval cycles for new deployments.
⮞In February 2026, the National Institute of Standards and Technology launched the AI Agent Standards Initiative with three pillars covering industry-led standards, community-led protocols, and research on agent security and identity. The initiative gives U.S. buyers a reference point for evaluating agent safety.
Autonomous AI and Autonomous Agents Market Segment Analysis
-
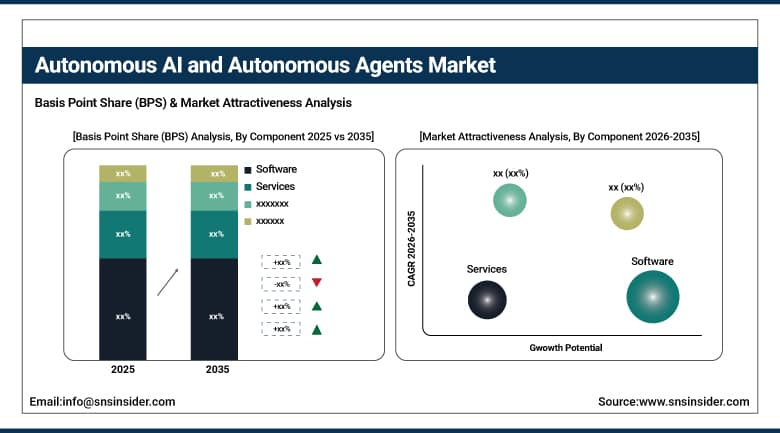
By Component, the Software segment dominated the Autonomous AI and Autonomous Agents Market with approximately 65.63% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 39.85%.
-
By Technology, the Machine Learning segment dominated the Autonomous AI and Autonomous Agents Market with approximately 37.75% share in 2025, while the Natural Language Processing segment is the fastest growing with a CAGR of approximately 40.12%.
-
By Deployment Model, the Cloud segment dominated the Autonomous AI and Autonomous Agents Market with approximately 75.05% share in 2025, and is also the fastest growing with a CAGR of approximately 38.96%.
-
By Industry Vertical, the IT and Telecom segment dominated the Autonomous AI and Autonomous Agents Market with approximately 20.43% share in 2025, while the Manufacturing segment is the fastest growing with a CAGR of approximately 38.97%.
By Component, Software Dominates the Autonomous AI and Autonomous Agents Market and Services Grows Fastest
Software remains the center of spending because the value of an autonomous agent resides in its planning logic, orchestration runtime, memory layer and the connectors that let it act inside business systems. Vendors package these elements as platforms with prebuilt agents for service, sales, finance and IT operations, which shortens deployment for buyers that lack in-house machine learning teams. Subscription pricing based on seats, tasks or outcomes also gives vendors recurring income and encourages continuous product investment. Governance modules covering permissions, monitoring and evaluation have become purchase criteria in regulated sectors, and they enlarge the software scope that each customer licenses.
Services are rising at a faster pace as enterprises discover that agent programs depend on process redesign, data preparation, integration and change management that vendors cannot supply alone. Consulting firms and platform providers are building forward-deployed teams that embed with clients to design workflows, test agent behavior and operate the result. Managed services are growing where companies prefer to outsource monitoring and incident response for agents with access to sensitive systems. Vendors increasingly sell these services as outcome-based contracts, which ties fees to measured performance.
⮞For instance, in December 2025, ServiceNow completed its acquisition of Moveworks, whose assistant serves 5.5 million employee users, and reported that nearly 90% of Moveworks customers had deployed it to all of their employees. The integration adds a large user base to ServiceNow's agent platform.
By Technology, Machine Learning Dominates the Autonomous AI and Autonomous Agents Market and Natural Language Processing Grows Fastest
Machine learning underpins nearly every autonomous capability, from the foundation models that interpret goals to the reinforcement and ranking methods that select actions. Enterprises value its flexibility across structured and unstructured tasks, and the mature tooling for training, fine-tuning and evaluation allows quick adaptation to company data. Cloud providers bundle managed model services, vector search and monitoring, so teams can place machine learning components inside agent workflows without building infrastructure. Advances in reasoning models and tool-use training have improved reliability on long tasks, which has widened the range of processes that organizations are willing to automate.
Natural language processing is advancing quickly because language has become the main interface through which people instruct, supervise and audit agents. Better long-context handling, multilingual coverage and structured output allow agents to read contracts, tickets, emails and logs and to produce actions that downstream systems accept. Voice-driven agents for contact centers are widening the addressable base further. Computer vision and context awareness play a supporting role by letting agents interpret screens, documents, images and environmental signals, which is particularly valuable in manufacturing, logistics and mobility.
⮞In December 2025, the OWASP GenAI Security Project published the OWASP Top 10 for Agentic Applications for 2026, a list of ten risks developed with more than 100 industry experts. The guidance gives developers a common vocabulary for testing language-driven agents.
By Deployment Model, Cloud Dominates the Autonomous AI and Autonomous Agents Market and Also Grows Fastest
Cloud deployment prevails because autonomous agents depend on elastic access to large models, vector databases, tool gateways and observability services that hyperscale providers already operate. Buyers can start with a hosted agent service, connect it to software-as-a-service applications through standard interfaces and scale usage as results are confirmed. Cloud vendors also supply identity, logging and policy features that help security teams approve agent access to enterprise data. Security reviews become simpler when a single provider supplies certified controls across the stack.
On-premises and sovereign deployments are growing in absolute terms as banks, governments and healthcare organizations seek to keep sensitive data and decision logs within controlled boundaries. Providers have responded with private model hosting, distributed cloud appliances and edge options that bring agent capability to local infrastructure. Hybrid arrangements are common, with orchestration in a public cloud and tool execution inside a protected network. Open-weight models make local operation more practical, while hardware suppliers offer reference designs for inference at the edge. Data residency rules in Europe and the Gulf continue to push public bodies toward these options.
⮞In August 2025, Google Cloud announced that Gemini models were available on-premises and at the edge through Google Distributed Cloud for customers with data-security and sovereignty requirements. The move extends agent capability to regulated environments.
By Industry Vertical, IT and Telecom Dominates the Autonomous AI and Autonomous Agents Market and Manufacturing Grows Fastest
IT and telecom organizations lead adoption because their work is already digital, their data is accessible through interfaces and their engineers are comfortable supervising automated systems. Agents resolve incidents, triage network faults, generate and review code and answer subscriber requests, which lowers operating cost and shortens response time. Technology firms are also the earliest producers and testers of agent products, so internal usage feeds directly into commercial offerings. Telecom operators handle very large volumes of customer interactions, which makes service automation attractive, and cloud-native network architectures give agents programmatic control over provisioning and monitoring tasks.
Manufacturing is advancing fastest as plants combine sensor data, digital twins and industrial software that agents can read and act upon. Use cases include predictive maintenance scheduling, quality inspection, production planning and supplier communication. Banking and insurance follow closely, with agents assisting with payments, onboarding and claims. Healthcare, retail, automotive, energy and government agencies are building their own agent portfolios, often starting with back-office processes before moving to customer-facing work. Regulators in finance and healthcare require explainability and human oversight, which influences design choices and favors vendors with sector-specific compliance features.
⮞For example, in March 2026, Santander completed an agentic commerce pilot across five Latin American countries in which AI agents made purchases within consent parameters set by customers. The pilot shows how banks are testing autonomous transactions.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
38.62% |
|
North America |
United States |
87.64% |
|
Europe |
Germany |
24.38% |
|
Latin America |
Brazil |
44.15% |
|
Middle East and Africa |
United Arab Emirates |
31.76% |
North America Autonomous AI and Autonomous Agents Market Insights
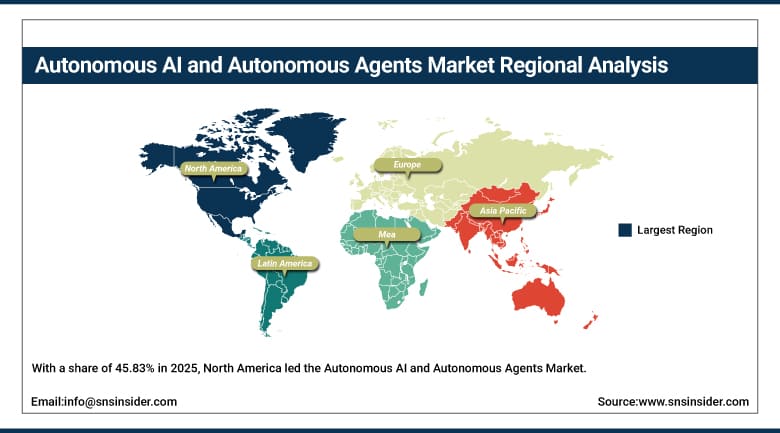
With a share of 45.83% in 2025, North America led the Autonomous AI and Autonomous Agents Market, supported by the concentration of frontier model developers, hyperscale cloud operators and enterprise application vendors. The United States supplies most regional demand, while Canada contributes through public research funding and financial services pilots. Corporate buyers have moved quickly from experimentation to budgeted programs, and boards are asking management for measurable returns from automation. The deep pool of engineering talent and venture capital allows specialized agent startups to reach scale before competitors elsewhere can respond.
Platform vendors compete by embedding agents inside the software that enterprises already use for customer relationships, workflow management and productivity. Security and governance have become central purchase criteria, and chief information security officers increasingly require identity management for software agents in the same way they do for employees. Federal agencies are drafting guidance on safe use, which influences private sector practice. Large employers are also publishing internal policies on agent oversight. Overall, the region remains the main source of product innovation and early revenue.
⮞In May 2026, Microsoft made Agent 365, its control plane for managing and governing enterprise agents, generally available. The release reflects enterprise demand for central oversight of agent identity and access.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Autonomous AI and Autonomous Agents Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 41.14% from 2026-2035, driven by national AI strategies, large developer populations and rapid digitization of services. China pursues national model and agent platforms backed by industrial policy, while India combines a large engineering workforce with government-funded compute capacity and a thriving services sector. Japan and South Korea focus on robotics and manufacturing automation, and Australia is applying agents to financial services and mining. Mobile-first consumer ecosystems offer large distribution channels for assistants that complete tasks across payments, shopping and communication.
Governments across the region are shaping the market through guidance and procurement. Singapore has set out practical controls for agent deployment, and several countries are funding sovereign language models to improve performance in local languages. Technology services companies in India are retraining large workforces to build and operate agents for global clients, which could change the economics of outsourcing. Challenges include fragmented regulation, uneven data quality and concern about dependence on foreign cloud infrastructure. Even so, the scale of the user base and the speed of public investment point to the strongest long-term expansion worldwide.
⮞In January 2026, Singapore's Infocomm Media Development Authority launched the Model AI Governance Framework for Agentic AI, described as the first governance framework designed specifically for autonomous agents. The framework sets four dimensions of control for organizations deploying agents.
Europe Autonomous AI and Autonomous Agents Market Insights
Europe represents a substantial market in which adoption is shaped by regulation, data protection and strong industrial and financial sectors. Germany, the United Kingdom and France lead spending, with the Nordic countries and the Netherlands showing high rates of enterprise digital maturity. Companies emphasize explainability, auditability and data residency, which supports European and open-source providers alongside global platforms. Manufacturing groups apply agents to supply chain planning and engineering documentation, while banks and insurers use them for compliance review and customer servicing under close supervisory attention.
The EU AI Act sets the legal framework, and its phased obligations give developers a defined schedule for preparing conformity processes, documentation and risk management systems. Public-sector adoption is advancing as ministries test assistants for service delivery, and sovereign cloud initiatives aim to keep sensitive workloads within the region. Industry associations in Germany and France are issuing guidance on testing and documentation, which smaller companies use as practical templates. Europe is expected to remain a major market with an emphasis on trustworthy deployment.
⮞In December 2025, Eurostat reported that 19.95% of enterprises in the European Union with ten or more employees used artificial intelligence technologies in 2025, up from about 13.5% a year earlier. The increase shows the pace at which European firms are building the base for agent adoption.
MEA and Latin America Autonomous AI and Autonomous Agents Market Insights
The Middle East and Africa is led by the Gulf states, where governments treat artificial intelligence as a pillar of economic diversification. The United Arab Emirates and Saudi Arabia are funding data centers, national models and public-service automation, and have set aggressive targets for government use of agents. South Africa, Kenya, Nigeria and Egypt are developing local ecosystems, although limited compute capacity, uneven connectivity and a shortage of specialist talent restrict wider adoption. International cloud providers are opening regional infrastructure that improves latency and data residency options for regulated customers.
⮞In April 2026, the UAE government announced a target for 50% of government sectors, services and processes to operate on agentic AI within two years. The goal makes public administration one of the region's largest prospective buyers.
Latin America is headed by Brazil, with countries such as Mexico, Colombia, Chile and Argentina gaining the increasing attention of banks, payment processing agencies and retailers. Mexico is one of the regions covered. Banks have taken the lead in piloting agents who take care of the payment and consumer requests on behalf of consumers, while software development outsourcing firms have also been using coding agents. Volatility of currency as well as lack of clouds locally may delay some big implementations, but the region has a youthful digital community with good mobile banking penetration.
⮞In April 2026, Visa launched Visa Agentic Ready in Latin America and the Caribbean, with 20 issuers already testing and 6 more preparing to join. The program builds the payment infrastructure for agent-initiated commerce across the region.
Growth Drivers: Public Sector Adoption and Shared Standards Drive Growth in the Autonomous AI and Autonomous Agents Market
Governments are becoming direct buyers and sponsors of autonomous systems, which supplies the market with large and visible reference deployments. Ministries test assistants for employment services, benefits processing and citizen inquiries, and national strategies set adoption targets that guide spending across agencies and contractors. Public procurement also pushes vendors to document safety, security and accessibility features, and those improvements carry over to commercial products. Sovereign compute programs add capacity that local developers can use to build agents suited to national languages and regulations.
Shared technical standards are lowering the cost of building and connecting agents. Open protocols for tool access, project instruction files and agent-to-agent messaging allow a single integration to work across many platforms, reducing lock-in concerns that previously made buyers hesitate. Foundations that hold these specifications in neutral governance attract contributions from competing vendors and open-source communities. As the available connectors multiply, each new agent becomes more useful on release, and enterprises can reuse integrations across projects. This compounding effect is expected to keep adoption rising throughout the forecast period.
⮞In January 2026, the United Kingdom's Department for Science, Innovation and Technology said it would pilot an AI assistant on GOV.UK services, starting with employment support, alongside a USD 1 million fellowship program with the Alan Turing Institute. The commitment shows government sponsorship of agent deployment.
Restraints: Security Exposure and Regulatory Uncertainty Restrain Growth in the Autonomous AI and Autonomous Agents Market
Those who can consume information, invoke applications, and expense cash become another attack vector through prompt injection, over-privilege, malicious use of tools, and data leakage. Those responsible for security are prudent in allowing general access since they must be able to regulate the behavior, and some have limited pilots to only read actions. Inconsistencies in reliability of long-running tasks, such as hallucinations and output, need human review, which diminishes the efficiency assumed in the business case. It is unclear in most jurisdictions whose fault any mistakes are when an agent acts for an individual or organization.
Regulatory timelines add planning uncertainty for global vendors. Guidelines for high-risk applications are becoming more detailed and sometimes delayed, hence requiring compliance teams to prepare for a number of different deadlines and guidelines simultaneously. Regional differences in guidelines make the process of product development in more than one market expensive. Small firms experience challenges with product certification and documentation processes. The potential for job loss could also lead to labor regulations and union involvement in certain industries. However, such considerations do not limit adoption but slow down the process of adoption.
⮞In May 2026, the European Parliament and the Council reached a provisional agreement to delay the application of high-risk obligations under the EU AI Act to December 2027 for stand-alone systems and August 2028 for embedded systems. The change extends the period of compliance uncertainty for vendors.
Opportunities: Emerging Economies and Low-Cost Agent Platforms Create Opportunities in the Autonomous AI and Autonomous Agents Market
Emerging economies offer large unserved populations and a need for services that agents can deliver at low cost, including tutoring, health information, agricultural advice and government paperwork assistance in local languages. Mobile-first users can reach these agents through messaging applications and voice, bypassing the need for personal computers. Vendors that adapt models to regional languages and low-bandwidth conditions can capture a first-mover position. Development agencies and national programs are beginning to fund such projects, and local developer communities are expanding quickly.
Lower-cost platforms are also widening opportunities within advanced economies. Smaller models running on modest hardware, open-weight releases and usage-based pricing allow midsize companies and public bodies to deploy agents without large capital commitments. System integrators can build practices around agent design, evaluation and operation, while independent software vendors can sell vertical agents for law, accounting, logistics and healthcare. Education and workforce programs that teach supervision of automated systems represent another growth area. The African continent alone currently holds a very small share of global compute, which indicates the scale of investment still ahead.
⮞In May 2025, the African Union reported that Africa holds about 1% of global AI compute capacity and about 3% of the global AI talent pool. The figures show the size of the infrastructure and skills gap that new investment can address.
Recent Developments:
-
In May 2026, Anthropic announced the acquisition of Stainless, a company that builds software development kits and servers for connecting applications to AI models through the Model Context Protocol. The acquisition strengthens Anthropic's position in tool connectivity, which it describes as a limiting factor for how useful agents can become.
-
In September 2026, Cognition expanded its Devin autonomous software engineering agent into Brazil, with Itau and Nubank named as early customers. The expansion extends enterprise coding agents into the largest Latin American financial market and indicates growing demand for autonomous engineering in banking.
-
In December 2025, Salesforce reported that its Agentforce platform had more than 9,500 paid deals in the third quarter of fiscal 2026, up 50% from the prior quarter, with more than 18,500 deals closed since launch. The growth signals that customer service and sales agents are moving from pilots to paid production use.
Autonomous AI and Autonomous Agents Market Key Players
-
Microsoft
-
Alphabet
-
Amazon Web Services
-
OpenAI
-
Anthropic
-
Salesforce
-
ServiceNow
-
UiPath
-
SAP
-
Oracle
-
Palantir Technologies
-
NVIDIA
-
Cognition AI
-
Sierra
-
Kore.ai
-
CrewAI
-
LangChain
-
Pegasystems
Autonomous AI and Autonomous Agents Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.19 Billion |
| Market Size by 2035 | USD 272.87 Billion |
| CAGR | CAGR of 37.63% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services, and Hardware) • By Technology (Machine Learning, Natural Language Processing, Computer Vision, and Context Awareness) • By Deployment Model (Cloud and On-Premises) • By Industry Vertical (IT and Telecom, BFSI, Retail and E-Commerce, Healthcare and Life Sciences, Manufacturing, Government and Defense, Automotive, Energy and Power, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Microsoft, Alphabet, Amazon Web Services, OpenAI, Anthropic, Salesforce, ServiceNow, IBM, UiPath, SAP, Oracle, Palantir Technologies, NVIDIA, Cognition AI, Sierra, Automation Anywhere, Kore.ai, CrewAI, LangChain, Pegasystems |

Frequently Asked Questions
Key opportunities include vertical agents for banking, healthcare and software engineering, low-cost platforms for small and medium enterprises, and mobile-first agents in emerging economies. Services linked to agent design, evaluation and governance also offer rising revenue for integrators and consulting firms.
The major growth factor is the shift from conversational assistants to systems that plan and complete multi-step tasks, supported by falling inference costs, open connection standards and public-sector adoption programs. These developments make large-scale automation of service, IT and finance work practical.
The Software segment dominated the Autonomous AI and Autonomous Agents Market in 2025 with approximately 65.63% share. Its lead reflects the value held in planning logic, orchestration runtimes, memory layers and connectors packaged as subscription platforms.
North America dominated the Autonomous AI and Autonomous Agents Market in 2025 with approximately 45.83% share. The region hosts the leading model developers, hyperscale cloud providers and enterprise software vendors, along with deep venture funding.
