
Aviation Asset Management Market Report Scope & Overview:
The Aviation Asset Management Market was valued at USD 206.60 Billion in 2025 and is expected to reach USD 336.60 Billion by 2035, growing at a CAGR of 5.00% from 2026 to 2035.
The aviation asset management market is expanding steadily due to the increased complexity associated with aircraft ownership, need for asset optimization during the entire lifecycle, and increased growth in the number of global aircraft fleets. Asset management of aviation includes planning, buying, leasing, maintenance, and even the disposition of aircraft, engines, and spare parts over their entire operational lifecycle in order to optimize their usage and ensure compliance with the regulations in addition to maximizing their residual value. In addition to that, market growth is being supported by aircraft modernization and replacement needs, emphasis on asset value maximization using leasing and remarketing, and use of digital aviation asset management tools.
A large majority of airlines use leased aircraft, which is more than 65%. Hence, asset management becomes vital for the purpose of ensuring profitability and efficiency, as the lessee and the airline concentrate on maintenance, financing, and the resell value of the asset throughout its life cycle.
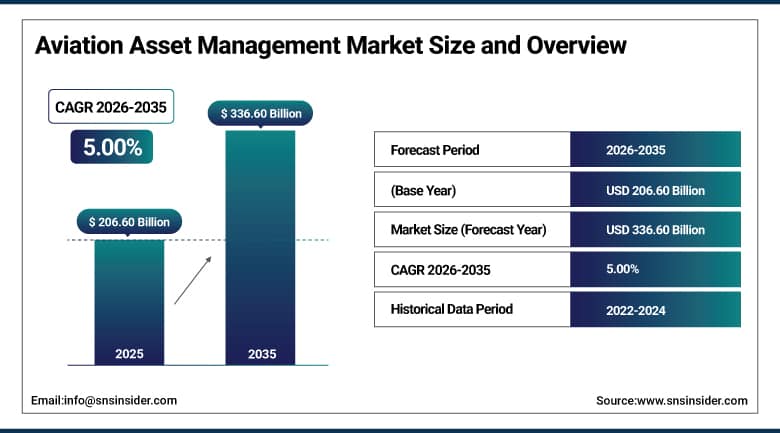
To Get More Information On Aviation Asset Management Market - Request Free Sample Report
Aviation Asset Management Market Trends
- Rising sale-and-leaseback activity is improving aircraft liquidity as airlines preserve capital for core operations.
- Growing adoption of digital asset tools is enhancing fleet planning, predictive maintenance, and lifecycle optimization.
- Increasing airline preference for asset-light models is strengthening reliance on leasing companies and third-party asset managers.
- Expanding institutional investor interest is driving demand for professional aviation asset and portfolio management services.
- Strategic partnerships are improving end-of-life remarketing, asset recovery, and residual value optimization capabilities.
The U.S. Aviation Asset Management Market Outlook
The U.S. aviation asset management market was valued at USD 42.20 Billion in 2025 and is projected to reach USD 68.70 Billion by 2035, growing at a CAGR of 5.00% during 2026–2035.
With increasing complexities in aircraft ownership and need for upgrading of aircraft fleets, the leading air carriers and lessors of the country are continuing to make investments in aviation asset management services. Increased interest of institutional investors in investing in aviation asset management funds, along with increasing use of digital fleet planning tools, are ensuring continued demand from domestic players for complex asset management services including leasing, technical, and financial services in aviation asset management.
It is still very evident that North America is investing heavily in sustainable asset management in aviation through structured leasing and digital asset management systems. This is because of the increasing importance of such practices among the leading carriers in the region.
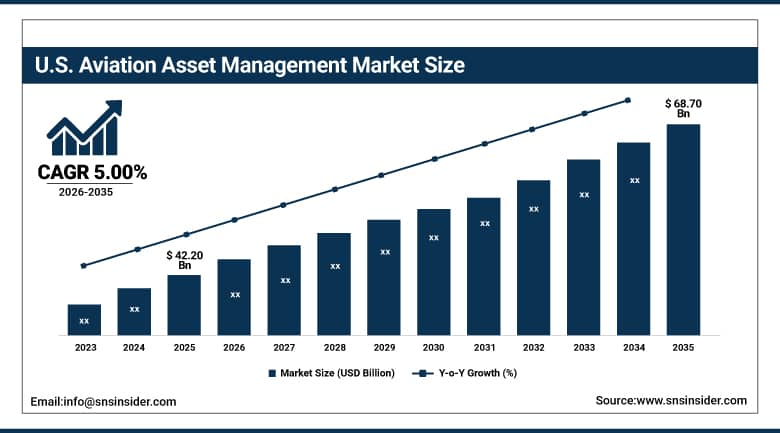
Aviation Asset Management Market Segment Analysis
- By Asset Type, aircraft dominated the aviation asset management market with a 72.30% share in 2025, while engines is the fastest-growing asset type segment with a CAGR of 7.40% from 2026–2035.
- By Mode of Purchase, operating lease dominated the aviation asset management market with a 49.60% share in 2025, while sale & leaseback is the fastest-growing mode of purchase segment with a CAGR of 8.60% from 2026–2035.
- By Service Type, leasing services dominated the aviation asset management market with a 44.60% share in 2025, while financial & portfolio management is the fastest-growing service type segment with a CAGR of 6.75% from 2026–2035.
- By End-User, airlines dominated the aviation asset management market with a 46.80% share in 2025, while leasing companies is the fastest-growing end-user segment with a CAGR of 7.90% from 2026–2035.
By Asset Type, aircraft dominated the aviation asset management market, while engines is the fastest-growing segment.
The aircraft segment captured the major chunk of the aviation asset management market, accounting for 72.30% of revenue generation in 2025. Aircraft are the primary category of asset types due to the fact that they constitute the largest capital expenditure in any airline or leasing company’s portfolio, forming the asset class which forms the base of all asset management operations in the aviation industry.
The engines segment is anticipated to register the fastest CAGR of 7.40% during the forecast period 2026-2035. Growing complexity of engine leasing and maintenance-by-the-hour financial arrangements, combined with rising engine overhaul and shop visit costs, is driving strong demand for specialized engine asset management services capable of optimizing utilization and residual value across increasingly sophisticated engine leasing portfolios.
By Mode of Purchase, operating lease dominated the aviation asset management market, while sale & leaseback is the fastest-growing segment.
The Operating Lease segment held the largest share of 49.60% of the revenue generated in the aviation asset management market in 2025. The operating lease continues to be the preferred method of purchasing due to its flexible nature as well as the benefits it gives from the point of view of the balance sheet, where airlines can acquire new aircraft without the hefty investment involved with outright ownership.
The sale & leaseback segment is expected to witness the fastest CAGR of 8.60% during the forecast period 2026-2035. Sale-and-leaseback transactions now eclipse traditional secured debt as airlines increasingly route scarce capital toward core operations, allowing carriers to unlock aircraft asset liquidity while retaining operational control, an advantage that proved particularly critical during periods of financial stress and continues driving structural adoption.
By Service Type, leasing services dominated the aviation asset management market, while financial & portfolio management is the fastest-growing segment.
The leasing services division accounted for the major market share in terms of revenue of 44.60% in 2025. The leasing services division continues to be the leader among the service types as well due to the dependence of the global aviation industry on leased planes, which serves as the basic transaction level for lessors and airlines.
The financial and portfolio management category is expected to grow at a CAGR of 6.75% during the forecast period up to 2035 as institutional investors will look for professional management of their aviation assets. The rising inclination among institutional investors for allocating their resources into aviation asset management funds has led to increased demand for financial and portfolio management services.
By End-User, airlines dominated the aviation asset management market, while leasing companies is the fastest-growing segment.
The airlines segment dominated the aviation asset management market with a revenue share of 46.80% in 2025. Airlines remain the largest end-user category owing to their direct responsibility for fleet composition, utilization, and maintenance decisions, representing the primary decision-making body driving overall aviation asset management service demand across the global commercial aviation ecosystem.
The leasing companies segment is expected to register the fastest CAGR of 7.90% during the forecast period 2026-2035. The increasing shift toward asset-light business models among airlines is encouraging greater reliance on leasing companies and third-party asset managers, driving rapid growth in leasing company asset management activity as more of the global commercial fleet transitions toward lessor ownership structures.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
France |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
27.90% |
|
Latin America |
Brazil |
37.70% |
Asia Pacific Aviation Asset Management Market Insights
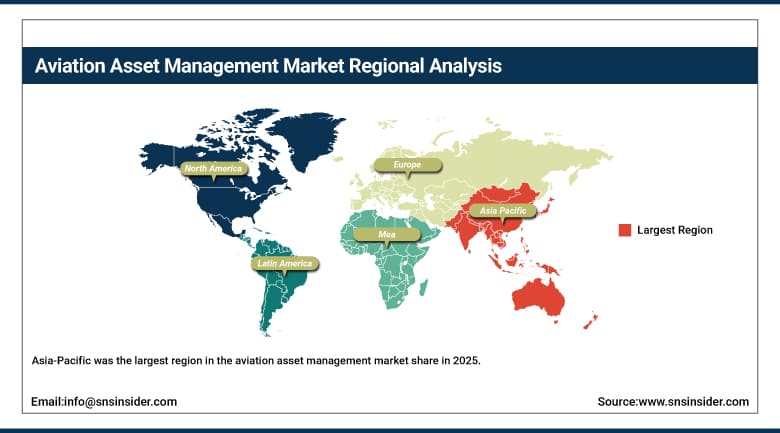
Asia-Pacific was the largest region in the aviation asset management market share in 2025. The market growth is driven by rapidly expanding commercial aviation fleets, rising air passenger traffic, and growing aircraft leasing activity across the region's major and emerging economies pursuing fleet modernization.
The fast-growing commercial aviation industry in China is one of the main drivers of the aviation asset management market in the Asia Pacific region, since there is an increase in the number of airlines in the country. Other countries contributing to the growth include India, Japan, and the Southeast Asian countries due to an increase in low-cost carrier fleets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Aviation Asset Management Market Insights
The North America aviation asset management market is expected to register the fastest regional CAGR during the forecast period. This is attributed to a strong focus on sustainability influencing investment strategies across the aviation sector, technological integration reshaping asset management practices, and substantial institutional investor participation in aviation asset management vehicles.
The United States held a prominent position in the North American aviation asset management market during 2025 due to widespread domestic airline and leasing business operations and the high degree of technology integration that improved the efficiency of decision-making in fleet management activities. Canada is playing its part in fueling the regional market with its increasing airline fleet modernization.
Europe Aviation Asset Management Market Insights
The Europe aviation asset management market was a major contributor in 2025. This is attributed to the region's substantial commercial aviation industry, strong presence of leading aircraft leasing companies, and comprehensive regulatory frameworks governing aircraft ownership and maintenance compliance.
France is one of the major markets in Europe owing to its strong aerospace manufacturing base and presence of leading aviation asset management service providers. Other countries such as Ireland, a global center for aircraft leasing, and the United Kingdom are also contributing to market growth through extensive lessor headquarters presence and fleet financing activity.
Middle East & Africa and Latin America Aviation Asset Management Market Insights
Middle East & Africa and Latin American regions are gradually expanding aviation asset management adoption as commercial aviation investment grows across both regions, supported by increasing regional airline fleet expansion and leasing company presence.
Brazil is set to be a prominent Latin American market fueled by growing domestic commercial aviation activity and rising airline fleet modernization investment. The Middle East & Africa region has UAE and Saudi Arabia investing in expanding national carrier fleets and aviation leasing infrastructure supporting the region's growing role as an international aviation hub.
Market Dynamics
Growth Drivers: Rising fleet expansion and lifecycle optimization needs driving market growth
Complexity in ownership of aircraft, need for optimized use of assets throughout its lifecycle, and increased aviation fleet growth are some of the key factors that influence the growth of the Aviation Asset Management Market. The advent of low cost airlines and increased traffic will continue to be the key growth drivers for this market since aviation organizations will need effective management of aircrafts and engines among others.
Increasing aircraft replacement and modernization needs, rising emphasis on maximizing asset value, and growing reliance on digital aviation asset tools are further driving market expansion. Expansion of leasing and MRO structured models, increasing aviation cost efficiency initiatives, and strengthening focus on operational cost control are supporting demand across the forecast period, as airlines and lessors continue prioritizing structured asset management programs over ad hoc fleet decisions.
Restraints: OEM production bottlenecks and capital intensity limiting market expansion
One of the key constraints on the market is consistent delays in OEM supply chain delivery of new-build aircraft, which limits the renewal plans for the airline and lessor fleets in spite of the strong demand for replacement.
Additionally, the substantial capital intensity associated with aircraft and engine ownership continues to require sophisticated financial structuring, exposing lessors and airlines to interest rate and residual value risk across multi-decade asset lifecycles. The technical complexity of coordinating maintenance, regulatory compliance, and remarketing activities across geographically dispersed fleets further requires specialized expertise that can constrain smaller operators' ability to optimize asset value independently.
Opportunities: Expansion of digital asset tools and institutional investment creating new growth avenues
Rising investments in advanced analytics, fleet planning software, and end-of-life asset remarketing solutions are further driving the evolution of aviation asset management services globally, creating substantial opportunities for technology providers and asset managers capable of delivering more sophisticated, data-driven lifecycle optimization capabilities.
There is a considerable growth opportunity in the continued expansion of institutional capital allocation toward aviation asset management vehicles, as investors increasingly seek professional oversight of aircraft and engine portfolios. The expansion of commercial aviation fleets and leasing activity in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: AerCap Holdings completed a major aircraft lease portfolio transaction, expanding its owned and managed fleet to strengthen its position as the world's largest aircraft leasing company.
- 2025: Avolon Aerospace Leasing placed a significant order for new narrow-body aircraft, expanding its leasing portfolio to meet growing airline customer demand for fuel-efficient fleet renewal.
- 2026: SMBC Aviation Capital expanded its sale-and-leaseback transaction volume, providing additional airlines with liquidity-generating fleet financing alternatives amid tightening capital market conditions.
- 2026: Air Lease Corporation launched an expanded digital fleet management platform, offering airline and lessor customers enhanced predictive maintenance analytics and asset utilization tracking capabilities.
Aviation Asset Management Market key players are:
- AerCap Holdings N.V.
- Avolon Aerospace Leasing Limited
- Air Lease Corporation
- BOC Aviation Limited
- GE Capital Aviation Services (GECAS)
- SMBC Aviation Capital
- Boeing Global Services
- Airbus Group SE
- Aircastle Limited
- Nordic Aviation Capital
- Willis Lease Finance Corporation
- Jackson Square Aviation
- Dubai Aerospace Enterprise (DAE Capital)
- ICBC Leasing
- CDB Aviation Lease Finance
- Macquarie AirFinance
- Carlyle Aviation Partners
- Fortress Investment Group LLC
- Castlelake, L.P.
- Apollo Aviation Group
Aviation Asset Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 206.60 Billion |
| Market Size by 2035 | USD 336.60 Billion |
| CAGR | CAGR of 5.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Asset Type (Aircraft, Engines, Components/Parts) • By Mode of Purchase (Operating Lease, Finance Lease, Direct Purchase, Sale & Leaseback) • By Service Type (Leasing Services, Technical Services, Financial & Portfolio Management, Regulatory Certifications) • By End-User (Airlines, Leasing Companies, MRO Providers, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | AerCap Holdings N.V., Avolon Aerospace Leasing Limited, Air Lease Corporation, BOC Aviation Limited, GE Capital Aviation Services (GECAS), SMBC Aviation Capital, Boeing Global Services, Airbus Group SE, Aircastle Limited, Nordic Aviation Capital, Willis Lease Finance Corporation, Jackson Square Aviation, Dubai Aerospace Enterprise (DAE Capital), ICBC Leasing, CDB Aviation Lease Finance, Macquarie AirFinance, Carlyle Aviation Partners, Fortress Investment Group LLC, Castlelake, L.P., Apollo Aviation Group. |
Frequently Asked Questions
The Aviation Asset Management Market is expected to grow at a CAGR of 5.00% from 2026 to 2035.
The Aviation Asset Management Market was valued at USD 206.60 Billion in 2025.
The market is driven by rising aircraft ownership complexity, increasing need for lifecycle asset optimization, and growing aviation fleet expansion.
The Aircraft segment dominated the Aviation Asset Management Market in 2025, accounting for approximately 72.30% market share.
The Asia Pacific region dominated the Aviation Asset Management Market in 2025.
