
Bio-LNG Market Report Scope & Overview:
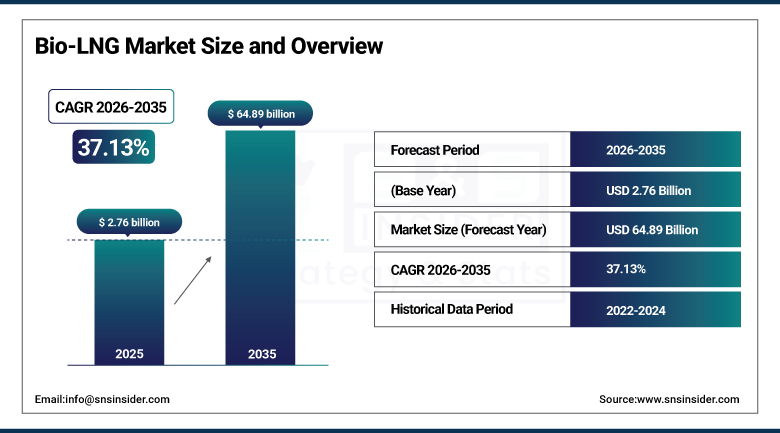
The Bio-LNG Market was valued at USD 2.76 Billion in 2025 and is expected to reach USD 64.89 Billion by 2035, growing at a CAGR of 37.13% from 2026 to 2035.
Bio-LNG, which refers to liquefied biomethane, is gradually gaining prominence as a source of renewable energy that is produced from biological substances such as agricultural waste, food waste, manure, and sewage. In its capacity as a direct and low carbon replacement for fossil-based LNG, bio-LNG can act as an energy source to power trucks, buses, ships, among other modes of transport.
Vireo selected Nordsol in 2026 as technology vendor for biogas upgrading and liquefaction at its new Lista Biogass plant in southern Norway, with construction beginning in the first quarter of 2026 and first production targeted for 2028, supplying bio-LNG to Nordic energy company Gasum under a long-term offtake agreement, reflecting the accelerating pace of decentralized bio-LNG plant development across Europe's rapidly maturing biomethane liquefaction industry.
Market Size and Forecast
-
Market Size in 2026E: USD 3.78 Billion
-
Market Size by 2035: USD 64.89 Billion
-
CAGR: 37.13% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: Europe
To Get more information Bio-LNG Market - Request Free Sample Report
Bio-LNG Market Trends
-
Growing LNG bunkering and refueling infrastructure, now available in nearly 200 ports worldwide, continues to remove logistical barriers to bio-LNG adoption.
-
Rising strategic offtake alliances between logistics fleets and producers are mitigating commercial risks and accelerating market maturation.
-
Expanding decentralized, small-scale bio-LNG plant deployment is allowing biogas producers to convert local organic waste streams into transportable fuel.
-
Increasing blend potential with conventional LNG could enable bio-LNG to meet a substantial share of global shipping fuel demand by 2050.
-
Growing biogenic CO2 liquefaction integration is offering additional green value and economic value alongside primary bio-LNG production.
U.S. Bio-LNG Market Outlook
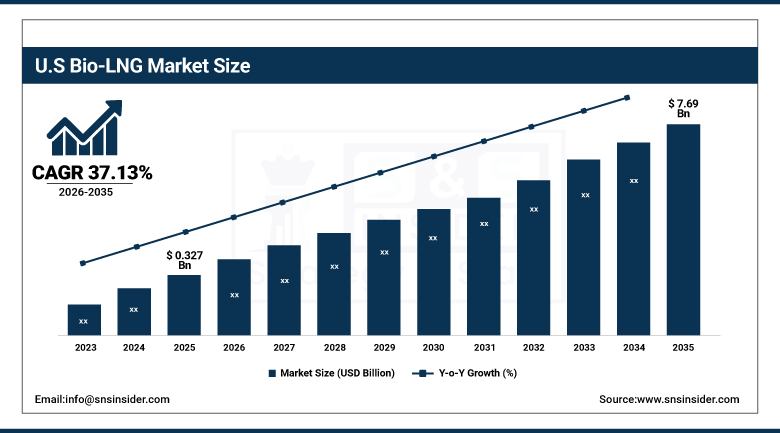
The U.S. Bio-LNG Market was valued at USD 0.327 Billion in 2025 and is projected to reach USD 7.69 Billion by 2035, growing at a CAGR of 37.13% during 2026-2035.
Growing worldwide push for net-zero emission goals, combined with increasing volatility of crude oil prices, continues to fuel domestic demand for alternative sustainable fuels including bio-LNG across heavy-duty transportation and industrial applications. Leading producers continue to expand anaerobic digestion capacity addressing rising organic waste feedstock availability across agricultural and municipal waste streams. Growing corporate offtake agreements between logistics fleets and bio-LNG producers continue to reinforce sustained domestic market development nationwide.
Biogas Västra Skaraborg selected Nordsol technology, alongside EnviTec Biogas's EnviThan upgrading system, in 2025 for a new Swedish bio-LNG plant expected to produce up to 70 GWh annually upon 2026 commissioning, reflecting the broader industry trend toward integrated technology partnerships that leading U.S. and international bio-LNG developers continue to replicate as they scale production capacity across diverse feedstock sources.
Bio-LNG Market Segment Analysis
-
By Source, Organic Household Waste led the Bio-LNG Market with a 40.40% share in 2025, while Municipal Waste is the fastest-growing source segment with a CAGR of 39.60% from 2026-2035.
-
By Application, Transportation Fuel led the Bio-LNG Market with a 56.00% share in 2025, while Marine Fuel is the fastest-growing application segment with a CAGR of 40.20% from 2026-2035.
-
By Production Process, Anaerobic Digestion led the Bio-LNG Market with a 78.60% share in 2025, while Thermal Gasification is the fastest-growing production process segment with a CAGR of 38.60% from 2026-2035.
By Source, Organic Household Waste Dominated the Market While Municipal Waste Is the Fastest-Growing Segment
The Organic Household Waste Segment was leading the Bio-LNG Market in terms of revenue share at 40.40% in 2025 due to the abundant availability of organic waste from households that serves as a reliable and geographically diverse source for the input into anaerobic digestion facilities. Organic household waste is expected to be a reliable year-round feedstock for bio-LNG plants and thus maintain its leadership among other sources in the overall bio-LNG market.
The Municipal Waste Segment is estimated to demonstrate the highest CAGR of 39.60% over the forecast period of 2026-2035 due to an increase in municipal solid waste diversion programs and investments in the infrastructure related to waste to energy in order to minimize the amount of landfills. With the expansion of organic waste streams, municipal waste will continue supporting the above-average growth rates of this segment compared to other sources.
By Application, Transportation Fuel Dominated the Market While Marine Fuel Is the Fastest-Growing Segment
Transportation Fuels held a leading position in the Bio-LNG market and accounted for 56.00% of the revenue share in 2025, owing to the increasing use of bio-LNG in buses, trucks, and other transport due to its higher energy density and lower emissions than conventional diesel. Bio-LNG can help cut down the emissions of CO2e by around 86% against diesel, helping the segment maintain its leading position among all bio-LNG applications as transportation fuels.
Marine Fuel is anticipated to witness the fastest CAGR of 40.20% between 2026 and 2035, on account of stringent regulations on maritime emissions across the globe and rising construction of LNG bunkering infrastructure that is now found in about 200 ports across the world. It is estimated that if bio-LNG is used as a blend with 20% LNG, it could supply up to 16% of the marine fuel demand in 2030.
By Production Process, Anaerobic Digestion Dominated the Market While Thermal Gasification Is the Fastest-Growing Segment
The Anaerobic Digestion segment dominated the Bio-LNG Market, accounting for 78.60% revenue share in 2025, due to its commercial maturity and the proven potential of the process to produce biomethane from various streams of organic wastes suitable for liquefaction. The Anaerobic Digestion segment still accounts for the most widely adopted production technology in terms of agriculture and municipal wastes; hence, maintaining its dominant standing in the wider bio-LNG market.
The Thermal Gasification segment is projected to experience the highest CAGR of 38.60% during the forecast period 2026-2035 owing to increasing demand for conversion of difficult streams such as forestry residues and organic wastes not amenable to digestion processes into biomethane suitable for liquefaction. Technology investments targeting feedstock flexibility continue to support the growth trend of this segment against the traditional Anaerobic Digestion process.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
Germany |
28.60% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
32.60% |
|
Middle East & Africa |
UAE |
22.60% |
|
Latin America |
Brazil |
26.40% |
North America Bio-LNG Market Insights
North America was an important part of the Bio-LNG Market share globally in 2025 due to the increasing demand for net-zero emissions on a global scale, as well as increasing volatility of crude oil prices. The growing investments in waste-to-energy infrastructure in the region are playing an important role in continuous market development in terms of agricultural and municipal waste feedstock.
The US comprised approximately 84.60% of the market share in North America in 2025 owing to the growing investment in anaerobic digestion capacity and availability of feedstock such as agricultural and municipal wastes in the country. In addition, Canada is playing an important role in regional growth owing to its increasing support for renewable fuels policies and production of bio-LNG facilities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Bio-LNG Market Insights
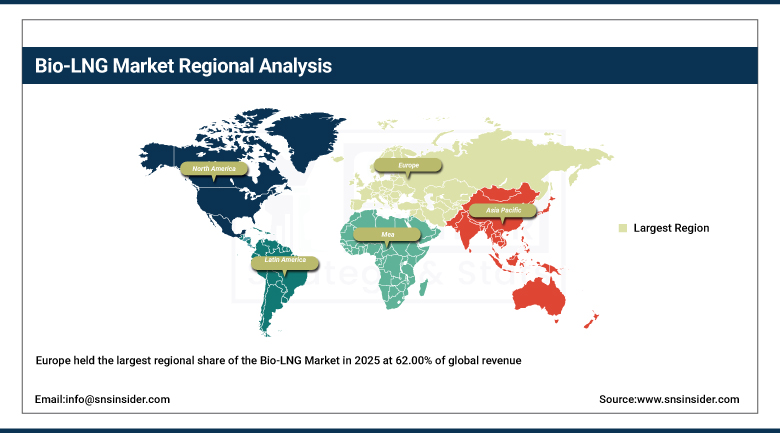
Europe held the largest regional share of the Bio-LNG Market in 2025 at 62.00% of global revenue, supported by supportive legislative and regulatory environments promoting renewable energy sources and lower greenhouse gas emissions across major member states. High goals for cutting carbon emissions and raising the proportion of renewable energy in the region's energy mix continue to reinforce Europe's leadership position across the broader bio-LNG landscape.
Germany led the European market with a 28.60% regional share in 2025, supported by its huge production units and supportive government policies favoring biomethane and renewable fuel development. Sweden, Norway, and the Netherlands are also contributing meaningfully to regional growth, supported by expanding decentralized bio-LNG plant deployment across Nordsol-built facilities and other leading technology providers.
Asia Pacific Bio-LNG Market Insights
Asia Pacific is emerging as the fastest-growing regional market for the Bio-LNG Market, fueled by rapid industrialization and rising energy requirements alongside growing environmental awareness across China and other major regional economies. Expanding domestic biomethane production infrastructure continues to reinforce the region's above-average growth trajectory relative to more mature Western markets.
China had a share of about 32.60% of the Asia Pacific market in 2025 owing to the huge potential of agriculture waste feedstocks and increased domestic production of biomethane. Japan, India, and South Korea have also made significant contributions towards the growth in the region due to the increased investments from governments in the waste-to-energy facilities.
Middle East & Africa and Latin America Bio-LNG Market Insights
The Middle East & Africa segment is witnessing sustained growth owing to rising efforts of renewable energy diversification within the Gulf nations, backed by increasing government focus on alternative sustainable fuels. Similarly, the Latin American segment is witnessing growth with increasing availability of agricultural waste feedstock and investments in biomethane production infrastructure.
In the year 2025, the UAE held the highest regional share of 22.60% in the Middle East & Africa segment, on account of increasing investments in renewable energy diversification and alternative fuel infrastructure. In the year 2025, Brazil held the largest regional share of 26.40% in the Latin American segment, due to the presence of a large agricultural waste feedstock base.
Market Dynamics
Growth Drivers: Decarbonization Mandates and Waste-to-Energy Innovation Driving Market Growth
The Bio-LNG Market is mainly being influenced by the rising need for sustainable energy sources, global efforts towards net-zero emission targets, and the high volatility in crude oil prices. The ability of bio-LNG to reduce the level of carbon emissions compared to normal diesel and fossil-based LNG continues to make it very relevant to current global decarbonization efforts for heavy duty transportation, marine shipping, and industrial heating.
The development of LNG bunkering infrastructure, which has been set up in almost 200 port facilities around the world, is eliminating all logistical challenges associated with the adoption of bio-LNG. Strategic partnerships between logistics fleets and producers of bio-LNG are reducing risks and accelerating the maturity of the market. Decentralized and smaller scale installations of bio-LNG production facilities continue to allow biogas producers to produce transportable and stored clean fuel from organic waste.
Restraints: High Production Costs and Feedstock Supply Constraints Limiting Market Expansion
Though the market is driven by positive underlying demand, it is subject to significant restraints owing to the high cost of manufacturing liquefied biomethane relative to the traditional fossil-fuel natural gas. This remains a key issue hampering the competitiveness of bio-LNG on the pricing front without policy intervention and subsidies. Availability restraints on feedstocks, especially high-grade organic waste, remain a constraint on manufacturing.
Capital intensiveness linked to biogas upgrading and liquefaction equipment remains a key factor that calls for large investments, especially in small-scale facilities. Regulatory and licensing complications also remain an impediment to project timelines in various jurisdictions.
Opportunities: Marine Bunkering Expansion and Technology Cost Reduction Creating New Growth Avenues
Substantial opportunity exists in continued expansion of marine bunkering infrastructure and bio-LNG blending with conventional LNG, potentially enabling bio-LNG to meet a substantial share of global shipping fuel demand by 2050. Companies that successfully scale production capacity while reducing per-unit costs stand to capture significant share of category growth as the maritime sector accelerates its decarbonization commitments.
Growing technology innovation reducing energy consumption and improving liquefaction efficiency presents a further significant growth avenue, as producers seek to narrow the cost gap with conventional fossil-based LNG. Expanding decentralized bio-LNG plant deployment across emerging markets in Asia Pacific and Latin America also represents meaningful untapped opportunity for technology providers and biogas producers.
Recent Developments:
-
2026: Vireo selected Nordsol as technology vendor for biogas upgrading and liquefaction at its new Lista Biogass plant in Norway, supplying bio-LNG to Gasum under a long-term offtake agreement.
-
2025: Biogas Västra Skaraborg selected Nordsol technology, alongside EnviTec Biogas's EnviThan upgrading system, for a new Swedish bio-LNG plant producing up to 70 GWh annually.
-
2025: St1 Biokraft inaugurated its new Mönsterås production plant in Sweden, reaching an annual production capacity of approximately 138 GWh of liquefied biomethane.
-
2025: Titan and Mitsui O.S.K. Lines advanced bio-LNG bunkering collaboration, reflecting growing maritime sector demand for verified low-carbon marine fuel alternatives.
Bio-LNG Market key players are:
-
TotalEnergies SE
-
Shell plc
-
Engie SA
-
Snam S.p.A.
-
Gasum Oy
-
Nordsol B.V.
-
Titan LNG
-
Air Liquide S.A.
-
Waga Energy SAS
-
CNG Fuels Ltd.
-
St1 Biokraft AS
-
Bio2Val
-
Iogen Corporation
-
Cryopur SAS
-
Renewable Energy Group, Inc.
-
DMT Environmental Technology
-
Vanguard Renewables
-
Nordion Energi
-
EnviTec Biogas AG
-
Vireo
Bio-LNG Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.76 Billion |
| Market Size by 2035 | USD 64.89 Billion |
| CAGR | CAGR of 37.13% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source (Organic Household Waste, Municipal Waste, Agricultural Waste, Industrial Waste) • By Application (Transportation Fuel, Marine Fuel, Power Generation, Industrial Heating) • By Production Process (Anaerobic Digestion, Thermal Gasification) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TotalEnergies SE, Shell plc, Engie SA, Snam S.p.A., Gasum Oy, Nordsol B.V., Titan LNG, Air Liquide S.A., Waga Energy SAS, CNG Fuels Ltd., St1 Biokraft AS, Bio2Val, Iogen Corporation, Cryopur SAS, Renewable Energy Group, Inc., DMT Environmental Technology, Vanguard Renewables, Nordion Energi, EnviTec Biogas AG, Vireo |
Frequently Asked Questions
The Bio-LNG Market is expected to grow at a CAGR of 37.13% from 2026 to 2035.
The Bio-LNG Market was valued at USD 2.76 Billion in 2025.
The market is driven by the growing need for clean, sustainable energy sources, worldwide push for net-zero emission goals, and increasing crude oil price volatility.
The Transportation Fuel segment dominated the Bio-LNG Market in 2025, accounting for approximately 56.00% market share.
The Europe region dominated the Bio-LNG Market in 2025, accounting for approximately 62.00% market share.
