
Solar Panels Market Report Scope & Overview:
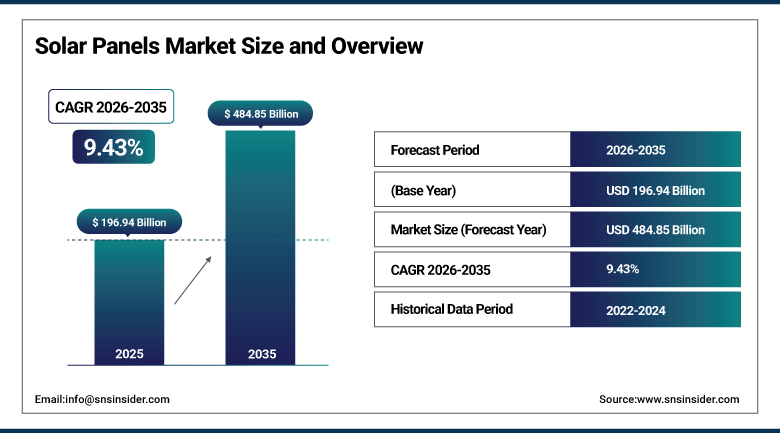
The Solar Panels Market was valued at USD 196.94 Billion in 2025 and is expected to reach USD 484.85 Billion by 2035, growing at a CAGR of 9.43% from 2026 to 2035.
The Solar Panels Market has reached a genuinely unusual inflection point, module prices have fallen so far and so consistently over the past decade that the conversation has shifted from whether solar is cost-competitive with fossil generation to how quickly manufacturers can scale efficiency gains further. Chinese manufacturers dominate global shipments by a wide margin, with the top four companies alone accounting for roughly 58% of total industry volume, and competition among them increasingly centers on cell efficiency records rather than pure price. Utility-scale deployment remains the market's largest application, though residential rooftop installations are growing meaningfully faster as homeowners increasingly pair panels with battery storage and smart energy management to reduce electricity costs and improve grid independence.
The new 475W dual-glass rooftop solar module with an efficiency of 23.77% was introduced by JinkoSolar Holding Co., Ltd. in August 2025 within its Tiger Neo range of modules having 20 busbars, which reduced micro-cracks by 30%.
To Get more information Solar Panels Market - Request Free Sample Report
Solar Panels Market Trends
-
Back contact and TOPCon cell technologies are pushing module efficiency records higher as manufacturers compete on performance rather than price alone.
-
Residential solar adoption is accelerating as homeowners increasingly integrate rooftop panels with battery storage and smart energy management systems.
-
Off-grid solar deployment is expanding in regions where traditional grid infrastructure remains limited or unreliable.
-
Manufacturer consolidation continues as leading Chinese producers capture a growing share of global module shipments.
-
Floating solar installations are gaining attention as a land-efficient deployment option in space-constrained and water-rich regions.
U.S. Solar Panels Market Outlook
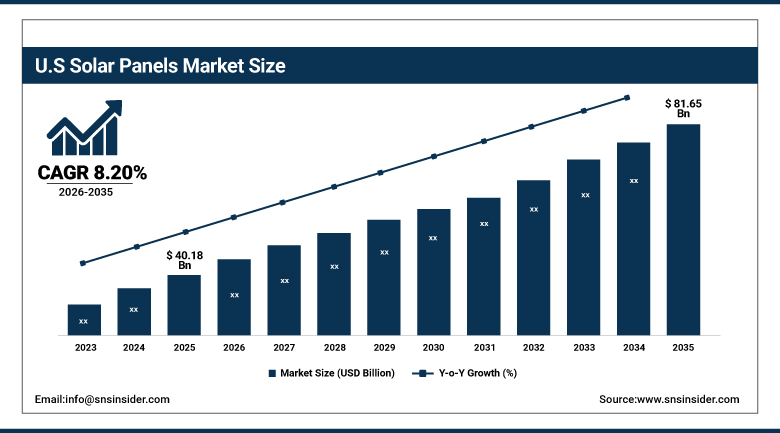
The U.S. Solar Panels Market was valued at USD 40.18 Billion in 2025 and is projected to reach USD 81.65 Billion by 2035, growing at a CAGR of 8.20% during 2026-2035.
Substantial government incentives and investment continue anchoring domestic demand, supporting both utility-scale deployment and the residential rooftop market that benefits from net metering schemes and energy storage incentive programs across many states. Rising retail electricity prices, combined with declining panel costs and growing consumer awareness of both financial and environmental benefits, continue expanding the addressable residential market beyond its traditional early-adopter base. The leading Chinese producers have developed a significant presence in domestic manufacturing in order to reach the local market through direct means; in fact, quite a number of producers currently have U.S.-based production plants included in their global shipment numbers. The integration of rooftop solar systems with storage batteries and building integrated photovoltaics is continuously becoming the driving force behind the residential use of solar power, as the installation of these systems is being seen as one element within a broader home energy management approach.
The global patent dispute between LONGi Green Energy Technology Co., Ltd. and JinkoSolar Holding Co., Ltd. was resolved in 2025 through a cross-licensing agreement involving some of the core patents.
Solar Panels Market Segment Analysis
-
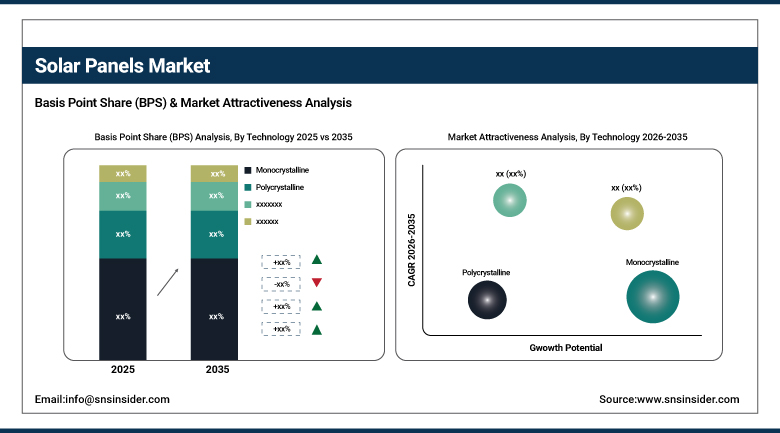
By Technology, monocrystalline dominates the Solar Panels Market while polycrystalline grows fastest, with monocrystalline holding 39.80% share in 2025 and polycrystalline registering a CAGR of 11.60% from 2026 to 2035.
-
By Application, utility dominates the Solar Panels Market while residential grows fastest, with utility holding 42% share in 2025 and residential registering a CAGR of 12.40% from 2026 to 2035.
-
By Installation Type, ground-mounted dominates the Solar Panels Market while rooftop grows fastest, with ground-mounted holding 56% share in 2025 and rooftop registering a CAGR of 11.20% from 2026 to 2035.
-
By Grid Type, on-grid dominates the Solar Panels Market while off-grid grows fastest, with on-grid holding 78% share in 2025 and off-grid registering a CAGR of 11.80% from 2026 to 2035.
By Technology, Monocrystalline Dominates the Solar Panels Market While Polycrystalline Grows Fastest
The Monocrystalline segment accounts for 39.80% share of the Solar Panels Market, which is the largest market segment, as the segment is gaining prominence owing to its high efficiency levels and longevity as compared to other forms of panels, which is extremely important in case of utility-scale projects seeking to utilize the land in the best manner possible, and also when homeowners need a more efficient solar system on a limited rooftop.
On the other hand, the Polycrystalline segment is growing at a 11.60% CAGR, which is the fastest amongst the various segments of the industry, owing to its cost-effectiveness as compared to the monocrystalline counterparts, which makes it very favorable for use in utility-scale applications where cost per watt is much more important than efficiency levels.
By Application, Utility Dominates the Solar Panels Market While Residential Grows Fastest
Utility holds 42% of the market by application, the largest single category, as power plants form the main application base while utilities continue expanding solar capacity to meet renewable energy targets and replace or supplement fossil fuel generation at scale. Lower module costs are making solar power increasingly viable for the large installations that utility-scale projects require.
Residential is the fastest-growing application, expanding at a 12.40% CAGR, driven by net metering schemes, energy storage incentive programs, rising retail electricity prices, declining panel costs, and growing consumer awareness of both financial and environmental benefits. The integration of rooftop solar panels with battery storage systems, smart energy management, and building-integrated photovoltaics continues accelerating residential adoption beyond what pure cost savings alone would drive.
By Installation Type, Ground-Mounted Dominates the Solar Panels Market While Rooftop Grows Fastest
Ground-Mounted installation type accounts for 56.00% of the market share, which is the highest among all the installation types and acts as the traditional form of installation for utility-scale solar plants, where the availability of land areas that are obstruction free and provide proper positioning of panels makes ground-mounted installations more convenient as compared to roof top installations. Increasing targets set for renewable energy production for utility-scale plants keep reinforcing the dominance of ground-mounted installations.
Rooftop installation type is witnessing the highest CAGR of 11.20%. With increasing awareness among household and commercial building owners regarding the dual benefit of not requiring additional space to generate electricity in addition to the reduction in electricity consumed by the buildings themselves, rooftop installations have seen a high level of adoption.
By Grid Type, On-Grid Dominates the Solar Panels Market While Off-Grid Grows Fastest
On-Grid holds 78% of the market by grid type, the largest single category, reflecting how most solar installations, whether utility-scale or residential, connect directly to existing electrical grid infrastructure to enable net metering, power export, and reliable backup supply when solar generation alone cannot meet demand. Established grid interconnection standards and utility relationships keep on-grid installations the default choice across most developed solar markets.
Off-Grid has the highest CAGR rate, standing at 11.80%, as more solar panels are being installed in areas which lack the conventional electrical grid and hence making it possible for standalone solar PV systems combined with battery energy storage to act as a primary source of energy. Rural electrification programs in developing countries are also contributing to its above average growth.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.00% |
|
Asia Pacific |
China |
38.00% |
|
Europe |
Germany |
25.40% |
|
Middle East & Africa |
UAE |
17.60% |
|
Latin America |
Brazil |
26.70% |
North America Solar Panels Market Insights
North America's solar panels market is mature and steady, supported by substantial investments and government incentives that have sustained both utility-scale and residential solar deployment for years. Growth here comes mostly from residential adoption acceleration and manufacturing reshoring rather than first-time technology introduction, since solar has been a mainstream generation source across the region for over a decade.
The United States accounts for approximately 85.00% of the North American market, reflecting its large utility-scale project pipeline and growing domestic manufacturing capacity. Canada contributes a smaller but steady share, tied to its own renewable energy targets and comparable incentive programs.
Europe Solar Panels Market Insights
Europe's solar panels market is mature and shaped heavily by ambitious renewable energy targets and comprehensive regulatory support for clean energy transition across the region. Rising retail electricity prices and growing energy security concerns following recent geopolitical disruptions continue reinforcing steady demand for both utility-scale and residential solar deployment.
Germany leads the European market with a 25.40% share, supported by its long-established solar manufacturing and installation base and strong government support for renewable energy adoption. France and the United Kingdom follow, with demand in both countries tied to expanding renewable energy targets and growing residential rooftop adoption.
Asia Pacific Solar Panels Market Insights
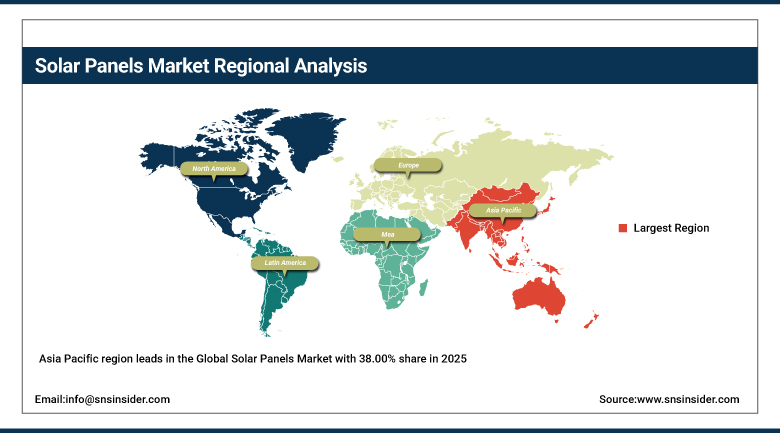
The Asia Pacific region leads in the Global Solar Panels Market with 38.00% share in 2025 due to increased energy requirements and the move of the region towards renewables as the most populous manufacturing and consumption center in the world. The leading global position of China in manufacturing as well as installation of the panels is one of the main factors behind the region's dominance, as China possesses the major number of the top module manufacturers in the world.
The market share of China in the region is about 38.00%, owing to large manufacturing facilities as well as annual solar installation capacity. The Indian and Southeast Asia markets are developing rapidly due to increasing domestic solar objectives, whereas Japan and South Korea are contributing due to existing solar manufacturing and installation industries.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa and Latin America Solar Panels Market Insights
Middle East & Africa represents the fastest-growing market segment in terms of growth in this market thanks to a number of large utility scale solar projects being developed in Gulf states and off-grid systems catering to poor grid infrastructure in parts of Africa. The Latin American market's growth is equally high and is due to a rising number of solar installations in Brazil and investment in renewable power in the region.
In terms of market shares, the UAE holds the largest share in the Middle East & Africa region with 17.60%, thanks to its status as a regional center for large solar projects. In terms of market shares in the Latin American market, Brazil contributes 26.70% due to its large investments in renewable energy, along with Mexico.
Market Dynamics
Growth Drivers: Falling Costs and Renewable Energy Targets Fueling Market Growth
The constant reduction in the costs of solar energy production, coupled with technological development that aims at increasing the efficiency of energy production, is the primary factor pushing this industry forward, since now solar energy is competing with fossil fuel energy in terms of sheer cost effectiveness without any need for subsidies. The emergence of increased environmental concerns and the adoption of government policies supporting the use of renewable energy sources is adding fuel to demand in both established and developing solar industries.
Increased concerns over energy security and the impact of recent geopolitical events on fossil fuel energy supplies are creating another line of demand.
Restraints: Polysilicon Price Volatility and Trade Policy Uncertainty Limiting Market Expansion
Polysilicon supply and pricing volatility, tied to broader raw material commodity markets, creates genuine margin pressure across the manufacturing value chain, with elevated inventory levels periodically pressuring module prices below sustainable levels for producers. Trade policy uncertainty, including tariffs and import restrictions targeting solar manufacturing in certain markets, can complicate supply chain planning for both manufacturers and project developers operating across multiple regions.
Grid interconnection queues and transmission infrastructure constraints in several major markets can delay utility-scale project timelines, creating a genuine bottleneck between manufactured module capacity and actual installed generation capacity.
Opportunities: Solar-Plus-Storage Integration and Emerging Market Expansion Creating New Growth Avenues
The development of integrated solar and storage technologies is one avenue for growth, since consumers prefer the grid independence and reliability offered by energy storage, in addition to solar panels alone. Companies that can deliver truly integrated systems will benefit greatly as consumers continue to favor such an approach.
Market expansion into new markets, combined with innovative finance approaches to serve these markets, is a second opportunity. This is especially true with off-grid applications where new markets may emerge.
Recent Developments:
-
2025: LONGi Green Energy Technology Co., Ltd. introduced its Hi-MO 9 back contact module, built on proprietary HPBC 2.0 technology, achieving 27.6% cell efficiency and 25.2% module efficiency, and earning three TÜV Rheinland awards at the All Quality Matters Congress 2025.
-
2025: Global solar module shipments reached approximately 536 GW, with JinkoSolar Holding Co., Ltd. and LONGi Green Energy Technology Co., Ltd. sharing the top position at 80 to 90 GW each, together with Trina Solar Co., Ltd. and JA Solar Technology Co., Ltd. accounting for roughly 58% of total industry shipments.
-
December 2025: LONGi Green Energy Technology Co., Ltd. secured a contract to exclusively supply Hi-MO 9 back contact modules for a 450 MW solar project in Hungary's Heves region.
-
2025: JA Solar Technology Co., Ltd. established a dedicated energy storage business division, targeting overseas commercial, industrial, and residential energy storage markets alongside its core photovoltaic business.
Solar Panels Market key players are:
-
LONGi Green Energy Technology Co., Ltd.
-
JA Solar Technology Co., Ltd.
-
JinkoSolar Holding Co., Ltd.
-
Trina Solar Co., Ltd.
-
Canadian Solar Inc.
-
First Solar, Inc.
-
SunPower Corporation
-
Hanwha Q CELLS Co., Ltd.
-
REC Group
-
Risen Energy Co., Ltd.
-
Suntech Power Holdings Co., Ltd.
-
Yingli Green Energy Holding Company Limited
-
Tongwei Co., Ltd.
-
GCL System Integration Technology Co., Ltd.
-
Sharp Corporation
-
Panasonic Holdings Corporation
-
Meyer Burger Technology AG
-
Waaree Energies Ltd.
-
Adani Green Energy Limited
-
Talesun Solar Co., Ltd.
Solar Panels Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 196.94 Billion |
| Market Size by 2035 | USD 484.85 Billion |
| CAGR | CAGR of 9.43% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Monocrystalline, Polycrystalline, Thin Film) • By Application (Utility, Residential, Commercial & Industrial) • By Installation Type (Ground-Mounted, Rooftop, Floating Solar) • By Grid Type (On-Grid, Off-Grid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | LONGi Green Energy Technology Co., Ltd., JA Solar Technology Co., Ltd., JinkoSolar Holding Co., Ltd., Trina Solar Co., Ltd., Canadian Solar Inc., First Solar, Inc., SunPower Corporation, Hanwha Q CELLS Co., Ltd., REC Group, Risen Energy Co., Ltd., Suntech Power Holdings Co., Ltd., Yingli Green Energy Holding Company Limited, Tongwei Co., Ltd., GCL System Integration Technology Co., Ltd., Sharp Corporation, Panasonic Holdings Corporation, Meyer Burger Technology AG, Waaree Energies Ltd., Adani Green Energy Limited, Talesun Solar Co., Ltd. |
Frequently Asked Questions
Key players include LONGi Green Energy Technology Co., Ltd., JA Solar Technology Co., Ltd., JinkoSolar Holding Co., Ltd., Trina Solar Co., Ltd., Canadian Solar Inc., First Solar, Inc., SunPower Corporation, and Hanwha Q CELLS Co., Ltd., alongside other established solar panel manufacturers.
Key opportunities include integrated solar-plus-storage systems for residential and commercial customers, expansion into emerging markets with tailored financing solutions, and growing off-grid and rural electrification applications.
The market is driven by the continuous decrease in the cost of solar power, technological advancements improving energy generation efficiency, and rising environmental concerns supported by favorable government policies.
The Monocrystalline segment dominated the Solar Panels Market in 2025.
The Asia Pacific region dominated the Solar Panels Market in 2025, accounting for approximately 38.00% of global market share.
