
Box And Carton Overwrap Film Market Report Scope & Overview:
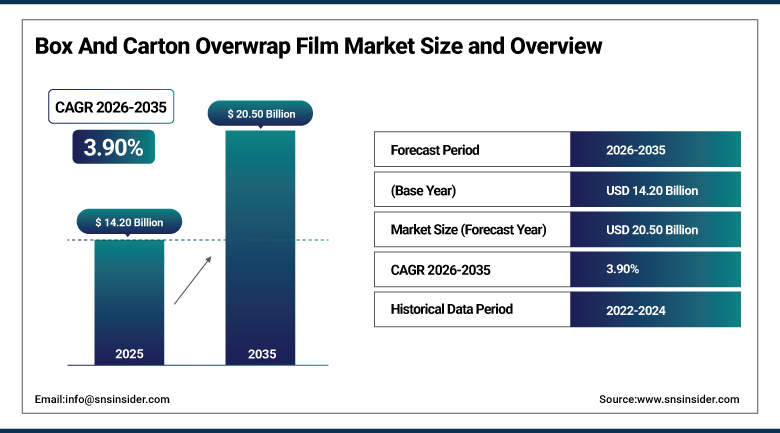
The Box and Carton Overwrap Film Market was valued at USD 14.20 Billion in 2025 and is expected to reach USD 20.50 Billion by 2035, growing at a CAGR of 3.90% from 2026–2035.
Overwrap film is the thin, clear plastic sleeve shrink-wrapped or stretched tightly around a finished box or carton, the layer that keeps a cigarette pack, a chocolate box, or a cosmetics case sealed, tamper-evident, and glossy on a retail shelf. It's a secondary packaging layer most shoppers never consciously register, right up until they're tugging at the little tear-strip to get into a new phone box. Food, pharmaceuticals, cosmetics, and tobacco remain the category's heaviest users, since all four depend on that combination of freshness protection, contamination visibility, and shelf appeal that overwrap film delivers cheaply and at enormous production scale.
Japanese overwrap film manufacturers significantly increased investment in biodegradable and compostable materials for food cartons in January 2026, responding to tightening environmental regulation and retailer commitments to phase out non-recyclable multi-layer laminates by 2030. The shift matters because most conventional overwrap films combine several plastic layers, sometimes with a metallized coating, precisely to get the clarity and barrier performance a box needs, and that layered construction is exactly what makes standard films so difficult to recycle through ordinary collection streams.
To Get more information Box And Carton Overwrap Film Market - Request Free Sample Report
Box And Carton Overwrap Film Market Trends
-
Recyclable mono-material film structures continue displacing traditional multi-layer laminates, as extended producer responsibility legislation across multiple countries makes standard collection-stream recyclability a hard compliance requirement rather than a marketing preference.
-
High-barrier, moisture-resistant film formulations continue expanding beyond pharmaceuticals into premium food gifting and confectionery applications, where humidity control directly affects product quality and shelf presentation.
-
Biodegradable and compostable overwrap materials continue advancing from pilot programs into genuine commercial production, particularly across markets with aggressive multi-layer laminate phase-out timelines.
-
E-commerce growth continues reinforcing demand for tamper-evident, high-clarity overwrap film that reassures buyers a product hasn't been opened or altered during shipping and warehouse handling.
-
Manufacturers continue investing in improved puncture resistance and printability, letting overwrap film double as both a protective barrier and a branding surface without compromising either function.
U.S. Box And Carton Overwrap Film Market Outlook
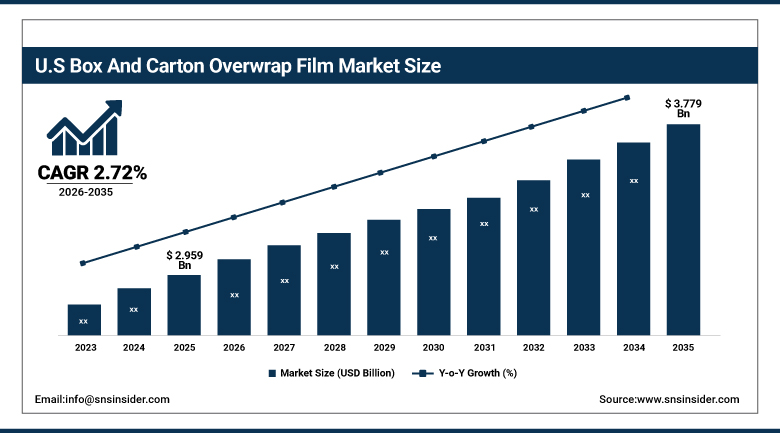
The U.S. Box And Carton Overwrap Film Market was valued at approximately USD 2.959 Billion in 2025 and is expected to reach approximately USD 3.779 Billion by 2035, growing at a CAGR of approximately 2.72%.
Demand in the United States is anchored by large food and beverage, pharmaceutical, and consumer goods industries that rely heavily on overwrap film for both product protection and retail shelf presentation. A rapidly expanding patchwork of state-level extended producer responsibility legislation continues reshaping material specification requirements, pushing domestic brand owners and converters toward mono-material film structures that can actually be recycled through standard collection systems. International film manufacturers with significant Indian and European production bases now compete directly with domestic producers to supply these compliant recyclable film alternatives.
Extended producer responsibility legislation in California, Colorado, Oregon, and other U.S. states began compelling film producers and brand owners to transition toward recyclable mono-material film structures through 2025 and 2026. Jindal Poly Films, Taghleef Industries, Cosmo Films, and UFlex, all major overwrap film suppliers with significant Indian or European manufacturing bases, now compete directly with domestic American producers to supply the recyclable mono-material BOPP and PE alternatives that food brands need to meet these state-level mandates.
Box And Carton Overwrap Film Market Segment Analysis
-
By Material Type, the Polypropylene segment dominated the Box And Carton Overwrap Film Market with approximately 38.60% share in 2025, while the Bioplastics/Others segment is the fastest growing with a CAGR of approximately 7.40%.
-
By Film Type, the Shrink Film segment dominated the Box And Carton Overwrap Film Market with approximately 57.80% share in 2025, while the Stretch Film segment is the fastest growing with a CAGR of approximately 5.60%.
-
By Film Thickness, the 20–40 Microns segment dominated the Box And Carton Overwrap Film Market with approximately 44.20% share in 2025, while the Above 40 Microns segment is the fastest growing with a CAGR of approximately 5.90%.
-
By Coating Type, the Uncoated Film segment dominated the Box And Carton Overwrap Film Market with approximately 61.40% share in 2025, while the Coated Film segment is the fastest growing with a CAGR of approximately 6.80%.
-
By End-User, the Food & Beverage segment dominated the Box And Carton Overwrap Film Market with approximately 41.60% share in 2025, while the Pharmaceuticals & Healthcare segment is the fastest growing with a CAGR of approximately 7.20%.
By Material Type, polypropylene dominates, bioplastics grows fastest
Polypropylene held the largest share of the material-type segment in 2025, valued for its optical clarity, cost efficiency, and compatibility with high-speed shrink and stretch wrapping equipment across nearly every overwrap application. Its balance of mechanical strength and transparency keeps polypropylene the default material choice for the majority of box and carton overwrap film production worldwide.
Bioplastics and other emerging materials are growing fastest as manufacturers respond to tightening environmental regulation and retailer commitments to phase out non-recyclable multi-layer laminates. Continued investment in biodegradable and compostable film formulations, particularly across markets with aggressive sustainability timelines, is pulling this material category's growth well ahead of the broader, conventional-plastic-dominated material mix.
By Film Type, shrink film dominates, stretch film grows fastest
Shrink film held the larger share of the film-type segment in 2025, favored for the tight, glossy, tamper-evident seal it creates once heat-shrunk around a finished box, a look retailers and brand owners have come to treat as a baseline shelf-presentation standard. Its compatibility with automated high-speed wrapping lines across food, cosmetics, and tobacco packaging keeps shrink film the dominant format across the category.
Stretch film is growing fastest as logistics and shipping applications increasingly favor its lower energy production process, since stretch wrapping doesn't require the heat-tunnel equipment shrink film needs to activate. Growing e-commerce and bulk shipping volumes are reinforcing this above-average growth trajectory as stretch film's cost and energy advantages become more compelling at scale.
By Film Thickness, 20–40 microns dominates, above 40 microns grows fastest
Films measuring 20 to 40 microns formed the biggest proportion of the thickness segment in 2025 due to the optimal compromise between sufficient strength for protection and material savings necessary for standard applications of film wrap on boxes and cartons. The mid-thickness segment is the best fit in food, cosmetic and consumer goods packaging applications which do not require extraordinary durability.
Films with a thickness greater than 40 microns are experiencing the highest growth rates due to increased applications in more heavy-duty segments such as industrial packaging and shipping and logistics where greater strength and puncture resistance are demanded from the films. Increased volumes of e-commerce shipments, which experience more stress than conventional retail shipments, contribute to this growth.
By Coating Type, uncoated dominates, coated grows fastest
Uncoated film held the majority share of the coating-type segment in 2025, remaining the lower-cost, simpler default for applications where basic protection and shelf presentation matter more than specialized barrier performance. Its straightforward production process and lower material cost keep uncoated film the practical choice across the majority of standard overwrap applications.
Coated film is growing fastest as barrier protection becomes an increasingly important specification for food, pharmaceutical, and premium cosmetics packaging that requires enhanced moisture, oxygen, or grease resistance beyond what uncoated film alone can offer. Growing demand for extended shelf life and premium product protection is reinforcing this above-average growth trajectory relative to the broader, uncoated-film-dominated market.
By End-User, food & beverage dominates, pharmaceuticals & healthcare grows fastest
Food and beverage accounted for the largest end-user share in 2025, driven by rising demand for packaged food and beverages that depend on overwrap film to extend freshness, deter contamination, and support retail shelf appeal simultaneously. That combination of functional and aesthetic requirements keeps food and beverage the anchor end-user industry across the entire overwrap film market.
Pharmaceuticals and healthcare is the fastest-growing end-user industry as overwrap film increasingly serves primary and secondary packaging for sensitive and non-sensitive injectable solutions, ensuring product protection throughout the supply chain from release to hospital use. Rising global pharmaceutical spending and expanding drug manufacturing capacity continue reinforcing this above-average growth trajectory relative to the broader, food-dominated end-user mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.40% |
|
North America |
United States |
80.15% |
|
Europe |
Germany |
24.90% |
|
Latin America |
Brazil |
35.60% |
|
Middle East & Africa |
UAE |
29.20% |
Asia Pacific Box And Carton Overwrap Film Market Insights
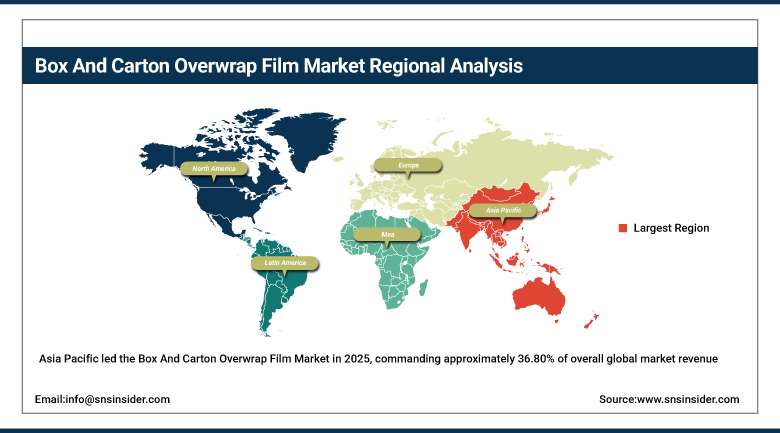
Asia Pacific led the Box And Carton Overwrap Film Market in 2025, commanding approximately 36.80% of overall global market revenue, and is also expected to register the fastest regional growth through 2035. The region's massive food processing, pharmaceutical, and consumer electronics manufacturing base, combined with rapidly expanding organized retail across China and India, continues reinforcing this leading and accelerating position. Government-supported manufacturing capacity expansion across multiple Asian economies keeps regional overwrap film production growing in step with rising domestic packaging demand.
China's large-scale food processing and consumer goods manufacturing sector gives the region substantial baseline demand, while India's expanding pharmaceutical and organized retail sectors are drawing significant new investment in overwrap film production. Japan and South Korea represent more mature, quality-focused markets with established high-barrier and biodegradable film adoption, while Southeast Asian markets continue following a similar consumption-driven growth trajectory as regional manufacturing infrastructure expands.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Box and Carton Overwrap Film Market Insights
North America represents a substantial box and carton overwrap film market, with the United States accounting for the large majority of regional demand through its large food and beverage, pharmaceutical, and consumer goods manufacturing base. Rapidly expanding state-level extended producer responsibility legislation continues reshaping material sourcing requirements across the region, pushing converters toward recyclable mono-material film structures.
Canada contributes additional demand through its own food processing and consumer goods manufacturing sectors, while Mexico's market continues expanding alongside growing nearshoring-driven manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production and distribution networks.
Europe Box and Carton Overwrap Film Market Insights
Europe represents a mature, sustainability-focused box and carton overwrap film market, shaped by comprehensive EU packaging waste regulation and strong consumer preference for recyclable, transparent packaging formats. Germany anchors regional demand, home to a large consumer goods and pharmaceutical manufacturing base and several major overwrap film producers investing in recycled and bio-based material development.
France, Italy, and the United Kingdom contribute meaningful volume as well, each with substantial food, cosmetics, and tobacco packaging sectors adapting to tightening EU sustainability requirements. Growing regional emphasis on mono-material and biodegradable film alternatives continues shaping product development across the region more directly than in most other markets.
MEA & Latin America Box and Carton Overwrap Film Market Insights
The Middle East and Africa represent a smaller but developing box and carton overwrap film market, with the UAE driving demand through growing food processing and consumer goods retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader consumer goods manufacturing and organized retail infrastructure development.
Latin America is a growing market led by Brazil, where expanding food processing and consumer goods manufacturing continue driving demand for protective and tamper-evident overwrap packaging. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing manufacturing sectors serving both domestic and export-oriented consumer goods markets.
Market Dynamics
Growth Drivers: Packaged goods demand and e-commerce growth fueling adoption
Rising demand for processed food and beverages is one of the clearest forces behind rising overwrap film demand, as growing consumption of packaged, shelf-stable products worldwide continues expanding the addressable market for freshness-protecting, tamper-evident secondary packaging. That consistent, high-frequency demand pattern gives the market a dependable revenue base tied directly to broader packaged goods consumption trends.
Continued e-commerce growth adds a second major driver, as expanding online retail and direct-to-consumer shipping volumes drive demand for tamper-evident overwrap film that reassures buyers a product hasn't been opened or altered during transit. Rising global online shopping penetration across both developed and emerging markets continues reinforcing this demand base independent of traditional retail distribution trends.
Restraints: Recycling infrastructure limitations and raw material cost volatility limiting broader adoption
Recycling infrastructure limitations remain a genuine restraint, since most conventional overwrap films combine several plastic layers, sometimes with a metallized coating, specifically to achieve the clarity and barrier performance a box needs, and that layered construction makes standard films difficult to recycle through ordinary collection streams. That infrastructure gap limits how quickly genuine circularity can scale even as manufacturers invest heavily in mono-material redesigns.
Fluctuating polypropylene and other plastic resin prices add a further restraint, since overwrap film manufacturers remain exposed to broader petrochemical commodity market swings that directly affect production costs and, ultimately, project budgets for brand owner customers. Manufacturers without long-term resin supply contracts are particularly exposed to these swings, which can compress margins even when finished-film demand remains steady.
Opportunities: Mono-material film innovation and biodegradable material development opening new growth avenues
Mono-material film innovation offers manufacturers a genuine path to capturing premium business from brand owners chasing credible recyclability commitments ahead of tightening extended producer responsibility regulation across multiple markets. Companies that successfully develop mono-material structures matching multi-layer film performance are positioned to capture significant new business as regulatory pressure continues expanding.
Biodegradable and compostable material development represents a second significant opportunity, as manufacturers respond to retailer commitments to phase out non-recyclable multi-layer laminates and tightening environmental regulation across multiple major markets. Companies that build strong biodegradable film capability are positioned to capture disproportionate growth as this transition accelerates from pilot programs into genuine commercial-scale production.
Recent Developments:
-
February 2026: Japanese folding-carton converters began integrating high-barrier, moisture-resistant overwrap films for seasonal food gifts and high-end chocolates, where humidity control and product protection are especially critical.
-
2025: Jindal Films continued expanding its global production capacity and distribution network, positioning the company for growth across food and pharmaceutical overwrap applications.
-
2025: Multiple major film manufacturers, including Cosmo Films and Taghleef Industries, continued developing recyclable mono-material BOPP and polyethylene film structures to meet expanding state and national extended producer responsibility mandates.
-
2025: Berry Global continued investing in sustainable overwrap film practices and adaptive technologies, supported by strategic acquisitions aimed at strengthening its position in the food packaging market.
Box And Carton Overwrap Film Market Key Players
-
Terichem AS
-
CCL Industries Inc.
-
Jindal Films (Jindal Poly Films Ltd.)
-
Taghleef Industries Group
-
Cosmo Films Limited
-
UFlex Limited
-
Berry Global Inc.
-
Futamura Group
-
Irplast S.p.A.
-
Transcendia, Inc.
-
SIBUR International GmbH
-
Garware Polyester Ltd. (Garware Hi-Tech Films)
-
Treofan Group
-
Innovia Films (Futamura)
-
Form Plastic Company Inc.
-
Sealed Air Corporation
-
Polyplex Corporation Limited
-
ProAmpac LLC
-
Constantia Flexibles Group GmbH
-
Klöckner Pentaplast Group
Box And Carton Overwrap Film Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 14.20 Billion |
| Market Size by 2035 | USD 20.50 Billion |
| CAGR | CAGR of 3.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Polypropylene (PP), Polyvinyl Chloride (PVC), Polyethylene (PE), Polyethylene Terephthalate (PET), Others) • by Film Type (Shrink Film, Stretch Film) • by Film Thickness (Up to 20 Microns, 20–40 Microns, Above 40 Microns) • by Coating Type (Coated Film, Uncoated Film) • by End-User (Food & Beverage, Pharmaceuticals & Healthcare, Personal Care & Cosmetics, Industrial Packaging, Shipping & Logistics, Electrical & Electronics, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Terichem AS, CCL Industries Inc., Jindal Films (Jindal Poly Films Ltd.), Taghleef Industries Group, Cosmo Films Limited, UFlex Limited, Berry Global Inc., Futamura Group, Irplast S.p.A., Transcendia, Inc., SIBUR International GmbH, Garware Polyester Ltd. (Garware Hi-Tech Films), Treofan Group, Innovia Films (Futamura), Form Plastic Company Inc., Sealed Air Corporation, Polyplex Corporation Limited, ProAmpac LLC, Constantia Flexibles Group GmbH, Klöckner Pentaplast Group |
Frequently Asked Questions
Ans: The Asia Pacific region has the world's largest market share and is expected to maintain its dominance in the coming forecast period for box and carton overwrap films.
Key opportunities in the Box And Carton Overwrap Film Market include mono-material film innovation for credible recyclability commitments and biodegradable, compostable material development to replace non-recyclable multi-layer laminates.
The market is driven by rising demand for processed food and beverages requiring freshness-protecting secondary packaging, combined with continued e-commerce growth requiring tamper-evident film.
The Polypropylene segment dominated the Box And Carton Overwrap Film Market, accounting for approximately 38.60% market share.
The market is driven by rising demand for processed food and beverages requiring freshness-protecting secondary packaging, combined with continued e-commerce growth requiring tamper-evident film.
