
Breast Implants Market Report Scope & Overview:
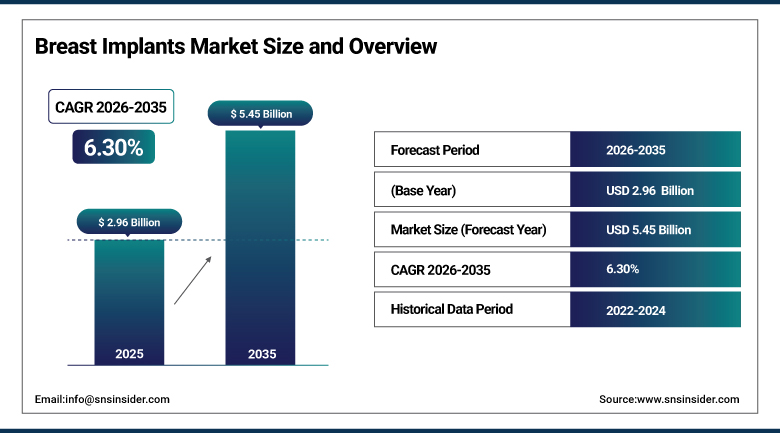
The Breast Implants Market was valued at USD 2.96 Billion in 2025 and is expected to reach USD 5.45 Billion by 2035, growing at a CAGR of 6.30% from 2026-2035.
The market for breast implants is growing as more women opt for cosmetic enhancement and breast reconstruction following mastectomy becomes increasingly available. Silicone gel-filled implants have the lion’s share, and companies work on creating implants with smoother surface, lighter fill and ergonomically designed for safety purposes. Product development and marketing is largely influenced by monitoring of safety, registration of patients and regulations regarding devices. Medical tourism and increasing disposable income fuel the demand in Latin America and Asia.
⮞In September 2026, the International Society of Aesthetic Plastic Surgery reported about 4.7 million breast procedures worldwide in its 2025 global survey, up 5.7%. The volume underlines the central place of breast surgery in aesthetic practice.
To Get more information Breast Implants Market - Request Free Sample Report
Breast Implants Market Trends
-
Preference for smooth-surface and ergonomic implant designs
-
Larger sizes and new devices for post-mastectomy reconstruction
-
Patient registries and recall alerts strengthening device surveillance
-
Medical tourism shaping demand in Latin America and Asia
-
Growth of clinic and ambulatory surgical center procedures
U.S. Breast Implants Market Outlook
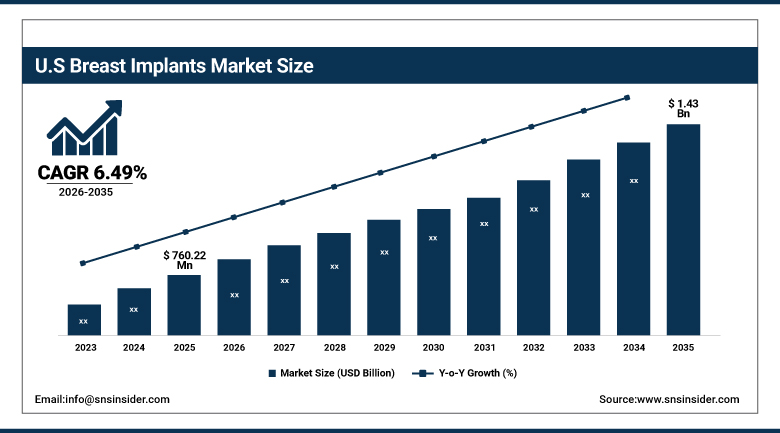
The U.S. Breast Implants Market was valued at USD 760.22 Million in 2025 and is expected to reach USD 1.43 Billion by 2035, growing at a CAGR of 6.49% from 2026-2035.
U.S. Breast Implants Market holds the status of the biggest national market on the back of a broad array of board certified plastic surgeons, consumer awareness, and federal coverage for post-mastectomy reconstruction. Silicone gel products lead the pack, while the FDA mandates use of patient decision aids and long-term studies. Fierce competition exists between just a few manufacturers with approval to sell their products. Social networks and cosmetic surgery clinics are driving more patient queries.
⮞In September 2026, the American Society of Plastic Surgeons reported 304,234 breast augmentation and revision procedures in 2025, up 11%, along with 159,140 reconstructions. Both cosmetic and reconstructive volumes are rising together.
Breast Implants Market Segment Analysis
-
By Material, the Silicone segment dominated the Breast Implants Market with approximately 84.75% share in 2025, and is also the fastest growing with a CAGR of approximately 6.40%.
-
By Shape, the Round segment dominated the Breast Implants Market with approximately 78.27% share in 2025, while the Anatomical segment is the fastest growing with a CAGR of approximately 7.10%.
-
By Application, the Augmentation segment dominated the Breast Implants Market with approximately 75.09% share in 2025, and is also the fastest growing with a CAGR of approximately 6.60%.
-
By End User, the Hospitals segment dominated the Breast Implants Market with approximately 55.23% share in 2025, while the Clinics segment is the fastest growing with a CAGR of approximately 6.70%.
By Material, Silicone Dominates the Breast Implants Market and Is Also the Fastest Growing
Silicone gel implants lead because their feel and shape are closer to natural tissue than saline devices, and cohesive gel formulations hold form even if the shell is damaged. Surgeons and patients prefer them for augmentation and reconstruction. Regulatory approvals in the United States, Europe and Asia cover several silicone product lines, and brand competition has produced softer and more durable options.
Silicone is also the fastest growing material as smooth and microtextured shells, lighter gels and improved shell designs address earlier safety concerns. Reconstruction patients increasingly receive silicone devices, and emerging markets in Asia and Latin America are shifting from saline. Saline remains a lower-cost alternative, but its share is eroding as surgeons adopt newer silicone products.
⮞The U.S. Food and Drug Administration reports 1,380 unique cases of breast implant-associated anaplastic large cell lymphoma and 64 deaths through June 2024. The data keeps attention on textured surfaces and drives preference for smooth devices.
By Shape, Round Dominates the Breast Implants Market and Anatomical Grows Fastest
Round implants lead because they provide upper-pole fullness, which most augmentation patients seek, and rotation does not affect the final appearance. Surgeons find placement straightforward, and the products cover wide ranges of profile and volume. Their lower revision risk linked to rotation and broad availability keep round devices at the center of manufacturer portfolios.
Anatomical implants are the fastest growing as surgeons use teardrop shapes for natural slope, especially in reconstruction and for thin patients. Improved gels and stable shells lower the risk of rotation. Ergonomic and hybrid shapes, which adapt to body movement, are being introduced, and surgeons trained in advanced techniques are increasingly specifying them.
⮞In 2026, the British Association of Aesthetic Plastic Surgeons reported 4,761 breast augmentations in the United Kingdom in 2025, down 8%, making it the most common surgical procedure in its audit. The figure reflects steady demand for shape-focused aesthetic surgery.
By Application, Augmentation Dominates the Breast Implants Market and Is Also the Fastest Growing
Augmentation leads because breast enlargement is one of the most requested aesthetic surgeries worldwide, and it is driven by patient preference for fuller shape and improved proportions. Elective procedures are paid privately, so surgeons set pricing and promote premium devices. Social media exposure and a growing number of aesthetic clinics keep inquiries high.
The same application is growing fastest as disposable incomes rise and medical tourism expands in Latin America, Eastern Europe and Asia. Younger patients are entering the market, and surgeons are offering financing and package pricing. Reconstruction remains important, supported by insurance coverage in many countries, while revision and exchange procedures add a steady stream of device demand.
⮞In February 2026, the Australian Breast Device Registry reported 7,281 cosmetic and 3,166 reconstructive implant cases among 17,720 insertions in 2024. The split shows the larger weight of aesthetic procedures.
By End User, Hospitals Dominate the Breast Implants Market and Clinics Grow Fastest
Hospitals lead because reconstruction procedures, complex revisions and many augmentation cases take place in operating theaters with anesthesia teams and overnight facilities. Tendering and group purchasing in public hospitals channel large volumes to approved suppliers. Teaching hospitals train surgeons and are often early adopters of new devices.
Clinics are the fastest growing end user as independent aesthetic practices and cosmetology clinics offer convenient scheduling, private rooms and package pricing. Many perform procedures in accredited surgical suites. Chain operators advertise widely and negotiate volume pricing with manufacturers. Ambulatory surgical centers are also expanding, helped by shorter recovery times and lower costs.
⮞In October 2025, NHS England reported 17,765 breast and cosmetic implant operations in 2024, with 73% of patients treated by independent providers. The share shows the weight of private clinics in implant surgery.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
72.72 |
|
Europe |
Germany |
23.64 |
|
Asia Pacific |
China |
34.81 |
|
Latin America |
Brazil |
46.38 |
|
Middle East & Africa |
Saudi Arabia |
29.47 |
North America Breast Implants Market Insights
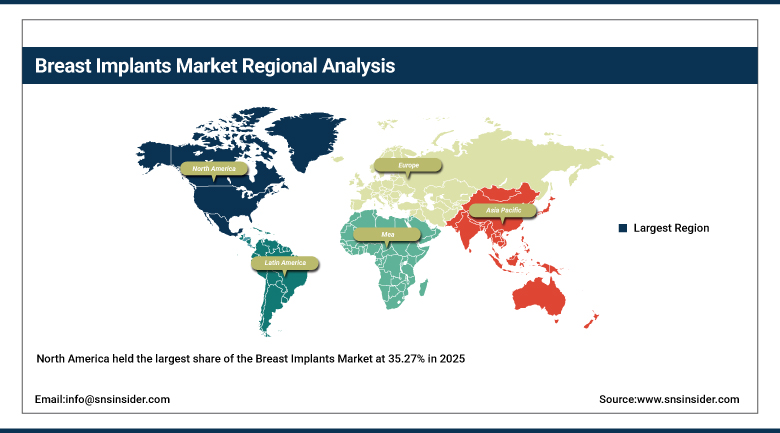
North America held the largest share of the Breast Implants Market at 35.27% in 2025, led by the United States with Canada as the smaller market. Strong consumer awareness, a large number of plastic surgeons and federal coverage of reconstruction support demand. Approved silicone and saline devices are supplied by a small group of major manufacturers.
FDA rules require patient decision checklists and post-approval studies, and recent approvals of new devices have intensified competition. Canada has introduced additional recall notification tools, and Mexico's proximity encourages some patients to seek lower-cost procedures abroad. Removal and exchange procedures are rising alongside new augmentations.
⮞In May 2026, Health Canada launched a voluntary registry for breast implant recall alerts, noting 14 breast implant recalls and safety alerts since 2015. The registry improves patient notification.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Breast Implants Market Insights
Europe held about 23.44% of the Breast Implants Market in 2025 and is led by the United Kingdom, Germany, France, Italy and Spain. Several implant makers are based in the region, including Polytech in Germany and GC Aesthetics in Ireland, and strong reconstruction coverage supports volumes.
The Medical Device Regulation has raised clinical evidence requirements, and national registries in the United Kingdom, Italy and the Netherlands collect traceability data. The collapse of one French manufacturer in 2025 left patients without a producer for warranty and monitoring, underscoring supply chain risks. Cosmetic demand is steady, and medical tourism to Spain and Eastern Europe is growing.
⮞In May 2026, Italy's Ministry of Health breast implant register reported that 55.7% of 68,776 procedures between August 2023 and December 2025 were reconstructive. The data shows the weight of oncologic surgery in European implant use.
Asia Pacific Breast Implants Market Insights
Asia Pacific is projected to be the fastest growing region in the Breast Implants Market, at a CAGR of 7.32% over 2026-2035, and held about 19.18% share in 2025. China, Japan, South Korea, Australia and India lead. Rising incomes, a large pool of younger patients and a booming aesthetic clinic sector fuel demand.
South Korea is a hub for aesthetic surgery and local implant production, while China is expanding approvals of local and imported devices. Australia operates a national registry that tracks implants and outcomes. Cultural preferences for smaller, natural shapes shape product choice, and price-sensitive markets such as India favor lower-cost brands.
⮞In June 2025, the International Society of Aesthetic Plastic Surgery reported that Japan performed 24,400 breast augmentations in 2024. The figure shows the sizeable regional procedure base.
MEA & Latin America Breast Implants Market Insights
Latin America and the Middle East and Africa together hold about 22.11% of the Breast Implants Market. In Latin America, Brazil, Mexico, Argentina and Colombia are leading aesthetic surgery markets, and Mexico attracts North American patients through medical tourism. Brazil is home to implant makers such as Silimed and has a large public and private surgery system.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Turkey, Egypt and South Africa are the leading markets, supported by growing aesthetic clinic networks and medical tourism. Regulatory oversight varies by country, and imports dominate supply. Brazilian authorities have previously recalled non-compliant imported implants, showing the need for strong quality enforcement.
⮞In August 2026, Brazil's regional plastic surgery society reported that breast plastic surgeries in the public health system rose 54.3% over 2016-2025 to 14,213 cases in 2025. The growth shows rising access to reconstruction.
Market Dynamics
Growth Drivers: Rising Cosmetic Procedures and Breast Cancer Reconstruction Drive Growth in the Breast Implants Market
Increasing cosmetic procedures are the primary cause. Disposable income, aesthetic consciousness, social media and flexible financing have widened the pool of candidates, particularly younger ones. The number of aesthetic clinics has surged in Asia and Latin America, while globally procedure numbers keep on growing. The manufacturers help the surgeons in training and marketing campaigns.
Reconstruction following breast cancer surgery is another growth factor. Increasing numbers of women survive breast cancer and opt for reconstruction using implants. The insurance coverage in the USA and most of the European countries guarantees access, while there are new large-size products for women who had no other choice. Screening leads to more conservative surgeries with an immediate reconstruction.
⮞In 2026, the American Cancer Society estimated about 321,910 new invasive breast cancer cases among U.S. women, 31.5% of all new female cancers. The incidence sustains demand for reconstruction devices.
Restraints: Safety Concerns and Manufacturer Instability Restrain Growth in the Breast Implants Market
Safety concerns restrain growth. Reports of breast implant-associated lymphoma, capsular contracture, rupture and systemic symptoms have led to recalls, label warnings and removals of textured devices. Some patients delay or avoid surgery, and surgeons spend more time on counseling. Litigation risk raises costs for manufacturers.
Manufacturer instability adds further limits. The market has seen bankruptcies and withdrawals, leaving patients without producers for follow-up or warranties. Stricter regulation raises the cost of evidence generation, and small producers struggle to meet requirements. Price competition from lower-cost makers and counterfeit risks in some markets add uncertainty.
⮞In April 2025, France's medicines safety agency ANSM reported that implant maker Groupe Sebbin ceased trading and entered compulsory liquidation with no legal successor. Patients were left without manufacturer post-market surveillance or warranty.
Opportunities: Reconstruction Coverage Expansion and Next-Generation Implants Create Opportunities in the Breast Implants Market
Reconstruction coverage expansion offers a major opportunity. Legislators are proposing to widen insurance requirements for breast and chest wall reconstruction, which would increase procedures and device demand. Hospitals and breast centers can build programs around immediate reconstruction. Manufacturers with devices designed for reconstruction can gain share.
Next-generation implants offer further potential. Smoother surfaces, bio-engineered shells, lightweight fills and ergonomic shapes are entering the market, and companies are conducting long-term clinical studies to differentiate. Digital tools for sizing and surgical planning help surgeons and patients choose devices. Emerging markets offer growth for brands that secure local approvals.
⮞In October 2025, a bill titled the Women's Health and Cancer Rights Modernization Act was introduced in the U.S. House of Representatives to require plans to cover breast and chest wall reconstruction. The measure would widen access to reconstruction.
Recent Developments:
-
In May 2025, Johnson & Johnson MedTech launched MENTOR MemoryGel Enhance implants in the United States for primary and revision post-mastectomy reconstruction. The sizes range from 930 to 1,445 cc, compared with a previous maximum of 800 cc, to serve patients who lacked a fitting size.
-
In December 2025, Establishment Labs submitted a premarket approval application to the FDA for Motiva SmoothSilk Round and Ergonomix implants in primary and revision reconstruction. The submission is supported by a U.S. study enrolling 274 patients at 17 U.S. centers.
-
In April 2026, Silimed announced that the Munich Regional Court granted a preliminary injunction against Polytech over polyurethane-coated implants that use Silimed's patent. The ruling bars Polytech from making and marketing the implants in Germany, and Polytech has appealed.
-
In July 2026, POLYTECH Health & Aesthetics said it is phasing in an updated Microthane process covered by a European patent application filed in June 2026. The company said the process gives a flat posterior surface and smooth edges, and rollout will depend on manufacturing capacity and regulation.
Breast Implants Market Key Players
-
Allergan Aesthetics (AbbVie Inc.)
-
Mentor (Johnson & Johnson MedTech)
-
Establishment Labs Holdings Inc.
-
Sientra (Tiger Aesthetics Medical, LLC)
-
GC Aesthetics plc
-
POLYTECH Health & Aesthetics GmbH
-
Silimed Industria de Implantes Ltda.
-
Bimini Health Tech (Serene)
-
HansBiomed Co., Ltd.
Breast Implants Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.96 Billion |
| Market Size by 2035 | USD 5.45 Billion |
| CAGR | CAGR of 6.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Silicone and Saline) • By Shape (Round and Anatomical) • By Application (Augmentation, Reconstruction, and Revision) • By End User (Hospitals, Clinics, and Ambulatory Surgical Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Allergan Aesthetics (AbbVie Inc.), Mentor (Johnson & Johnson MedTech), Establishment Labs Holdings Inc., Sientra (Tiger Aesthetics Medical, LLC), GC Aesthetics plc, POLYTECH Health & Aesthetics GmbH, Silimed Industria de Implantes Ltda., Bimini Health Tech (Serene), HansBiomed Co., Ltd. |

Frequently Asked Questions
Key players include Allergan Aesthetics (AbbVie), Mentor (Johnson & Johnson MedTech), Establishment Labs, Sientra (Tiger Aesthetics), GC Aesthetics, POLYTECH Health & Aesthetics, Silimed, Bimini Health Tech and HansBiomed.
Key opportunities include wider reconstruction coverage, next-generation smooth and ergonomic implants, digital sizing tools and fast-growing Asia Pacific demand.
Rising cosmetic procedures and breast cancer reconstruction are the main growth factors.
By Material, the Silicone segment dominated the market in 2025 with an estimated 84.75% share, supported by a natural feel and shape retention.
North America dominated the market with a share of 35.27% in 2025, driven by strong consumer awareness, many plastic surgeons and reconstruction coverage.
