
Sepsis Diagnostics Market Report Scope & Overview:
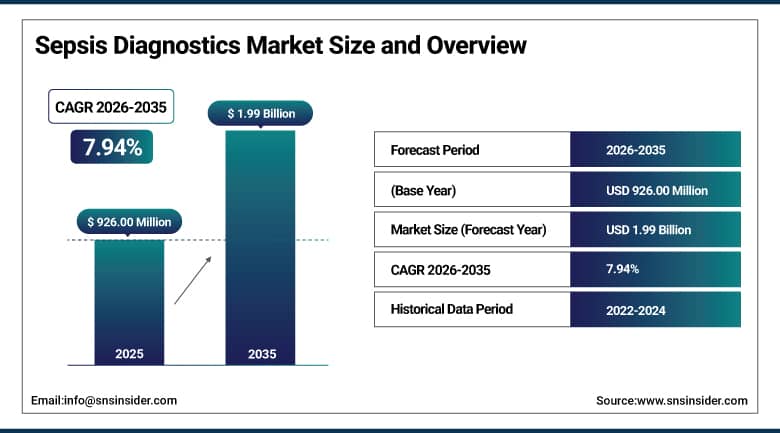
The Sepsis Diagnostics Market, which covers blood culture media, assays and reagents, instruments, and software used to detect sepsis and identify its cause, was valued at USD 926.00 Million in 2025 and is estimated at USD 999.52 Million in 2026. It is projected to reach USD 1.99 Billion by 2035, registering a compound annual growth rate (CAGR) of 7.94% from 2026 to 2035. Hospitals are building sepsis programs that depend on earlier cultures, faster pathogen identification, and decision support tools. Demand is also supported by antimicrobial resistance and steady laboratory automation.
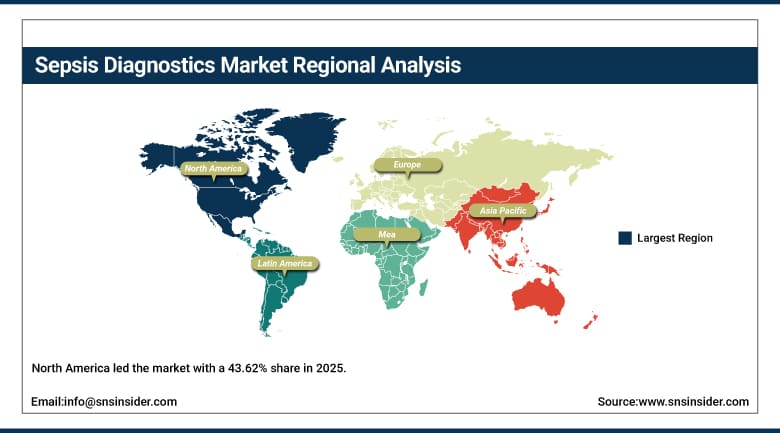
North America accounted for the largest share of the market at 43.62% in 2025, supported by widespread hospital sepsis programs, strong laboratory infrastructure, and early clearance of new tests and software. Europe holds the second position, where laboratories are upgrading blood culture systems under new device rules. Asia Pacific is expected to expand at the fastest pace through 2035, as hospitals in China, India, and Japan strengthen intensive care and laboratory capacity. Latin America and the Middle East and Africa remain smaller. Hospital accreditation programs are widening testing in these smaller regions.
To Get More Information On Sepsis Diagnostics Market - Request Free Sample Report
Key Report Takeaways
- By product, blood culture media held a 37.46% share in 2025, while assay kits and reagents are the fastest growing.
- By technology, microbiology held a 45.18% share in 2025, while molecular diagnostics is the fastest growing.
- By pathogen, bacterial infections held a 77.41% share in 2025, while fungal infections are the fastest growing.
- By end user, hospitals and clinics held a 76.83% share in 2025, while pathology and reference laboratories are the fastest growing.
- By region, North America held a 43.62% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
- Host-response tests that read the immune signature of infection are moving into emergency departments.
- AI and electronic health record-based sepsis software is gaining regulatory clearances and payment support.
- Rapid identification and susceptibility testing directly from positive blood cultures is shortening time to targeted therapy.
- Blood culture systems are adding capacity and automation to handle rising test volumes.
- Portfolio consolidation among diagnostics suppliers is reshaping the competitive landscape.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High sepsis burden and hospital programs |
+3.68% |
United States, Europe |
Long term (4 years or more) |
|
Guideline emphasis on early cultures and lactate |
+2.74% |
Global |
Short term (2 years or less) |
|
Faster pathogen and resistance identification |
+3.12% |
United States, Europe |
Medium term (2 to 4 years) |
|
Payment and policy support in the U.S. |
+2.31% |
United States |
Medium term (2 to 4 years) |
|
AI and host-response test entrants |
+2.87% |
United States, Europe |
Medium term (2 to 4 years) |
High Sepsis Burden Keeps Hospital Programs Expanding
Sepsis is a leading cause of hospital deaths and a costly condition to treat, so hospitals invest in programs that screen patients early and confirm infection quickly. In August 2026, the U.S. Centers for Disease Control and Prevention reported that about 1.7 million adults in the United States develop sepsis each year. Dedicated coordinators, standard screening, and rapid response teams all rely on laboratory tests, which raises demand for cultures, assays, and software. Similar programs are spreading in Europe and Asia.
Guideline Emphasis on Early Cultures Raises Testing Volumes
Clinical guidance stresses that blood cultures should be drawn before antimicrobial therapy begins and that lactate should be measured in patients with suspected sepsis. In March 2026, the Surviving Sepsis Campaign released updated adult guidelines with 129 statements, 46 of them new, which reinforce these steps for hospitals worldwide. Laboratories respond by increasing culture capacity and turnaround, and emergency departments adopt protocols that trigger testing at triage. Each additional case screened adds consumables and instrument use. Hospital quality teams also track bottle collection compliance.
Faster Pathogen and Resistance Identification Improves Treatment Decisions
Clinicians want to move from broad antibiotics to targeted therapy as early as possible, and tests that identify the organism and its resistance markers within hours make this possible. Multiplex panels, rapid susceptibility systems, and mass spectrometry workflows shorten the time between a positive culture and an actionable result. Stewardship teams value these tools because they reduce unnecessary antibiotic use and length of stay. Suppliers continue to expand panels and menus, which supports replacement of older systems. Faster answers also shorten intensive care stays for many patients.
Payment and Policy Support Encourages New Technology Use
Policy makers in the United States are linking hospital payment to sepsis outcomes and are encouraging new technology through add-on payments. In July 2026, the Centers for Medicare and Medicaid Services finalized its fiscal year 2027 inpatient payment rule, which approved a new technology add-on payment for a sepsis flagging device and advanced a sepsis readmission measure. Such moves signal that hospitals will be rewarded for better detection, and they improve the business case for diagnostic tools. Hospitals use these signals when planning budgets for laboratory upgrades.
AI and Host-Response Test Entrants Broaden the Market
New entrants are adding software and blood tests that estimate the risk of sepsis from electronic records or from the immune response of the patient. Several have obtained U.S. regulatory authorization, which gives hospitals confidence to adopt them alongside cultures. These tools target the early hours of care when the diagnosis is uncertain, and they create demand for new reagents, analyzers, and software subscriptions. Investors continue to fund the category, which supports product development and wider clinical trials. Large health systems are testing these tools across several emergency departments.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Guideline caution on single biomarkers |
-2.36% |
Global |
Medium term (2 to 4 years) |
|
Reimbursement and definition conflicts |
-1.89% |
United States |
Short term (2 years or less) |
|
European device regulation workload |
-1.43% |
Europe |
Medium term (2 to 4 years) |
|
Limited evidence base for new tests in public systems |
-1.10% |
United Kingdom, Europe |
Medium term (2 to 4 years) |
Guideline Caution on Single Biomarkers Limits Routine Use
Current clinical guidance states that sepsis is a clinical diagnosis and should not be ruled in or ruled out using a single biomarker or test. Evidence for novel rapid host-response tests is still limited, and many hospitals wait for stronger trial data before adding them to standard care pathways. This caution slows adoption of new assays even when they are cleared by regulators, and it keeps blood culture as the reference method. Suppliers must therefore fund large studies to demonstrate value.
Reimbursement and Definition Conflicts Create Uncertainty
Hospitals in the United States face differing definitions of sepsis, since federal quality measures and many private payers use different clinical criteria. This creates uncertainty about which patients are counted, how cases are coded, and whether faster testing will be reimbursed. Laboratories hesitate to invest in new systems when payment rules are changing, and hospital finance teams ask for proof of savings before approving purchases. Clearer rules would help suppliers plan pricing and contracts. Hospital executives also need clearer rules before expanding budgets.
European Device Regulation Raises Compliance Workload
Diagnostic manufacturers selling in Europe must move their products through the in vitro diagnostic regulation, which requires notified-body review, performance evidence, and post-market monitoring. Regulation (EU) 2024/1860, in force from July 2024, extended the transition periods, with deadlines running to December 2027 for the highest-risk class, but the work remains substantial. Smaller companies may delay launches or drop products, which narrows choice for laboratories. Notified-body capacity can limit review speed, so companies must plan product launches years ahead of time.
Limited Evidence in Public Systems Delays Adoption
Public health systems adopt tests only when cost effectiveness is clear. In March 2026, the National Institute for Health and Care Excellence in the United Kingdom moved its procalcitonin testing topic to the awaiting development stage, which leaves routine use dependent on local decisions. Without national guidance, trusts differ in how they buy and use sepsis tests. Budget pressure in public hospitals further slows the purchase of new instruments and panels. Public hospitals often require local pilots before approving wider purchases.
Sepsis Diagnostics Market Segment Analysis
By Product, Blood Culture Media Dominates Sepsis Diagnostics Market; Assay Kits and Reagents to Register Fastest Growth.
Blood culture media accounted for a 37.46% share in 2025 because culture remains the reference method for confirming bloodstream infection and every suspected case requires paired bottles. Laboratories consume large volumes of single-use bottles, which generate recurring demand. Guidelines that call for cultures before antibiotics support steady growth in orders, and automated incubators in hospital laboratories are built around specific bottle formats. Distribution agreements and training services from suppliers help hospital laboratories maintain consistent quality across multiple sites.
Assay kits and reagents are projected to grow at a CAGR of 9.24% from 2026 to 2035 as hospitals add multiplex panels, rapid susceptibility tests, and immune biomarker assays to the culture workflow. These products deliver results in hours rather than days and support stewardship goals. Each test run consumes cartridges and reagents, so installed instruments create a steady stream of consumable sales as menus expand. Suppliers also bundle software and service contracts with reagent supply to retain laboratory customers.
By Technology, Microbiology Dominates Sepsis Diagnostics Market; Molecular Diagnostics to Register Fastest Growth.
Microbiology accounted for a 45.18% share in 2025 because culture, identification, and susceptibility testing are performed for almost every suspected sepsis case. Automated incubation systems, mass spectrometry, and susceptibility instruments are installed in most hospital laboratories. Clinical microbiologists trust culture-based results because they provide live isolates for treatment decisions, and this trust sustains replacement and upgrade cycles. Rapid methods are usually added on top of this workflow rather than replacing it, which keeps microbiology equipment in constant use.
Molecular diagnostics is expected to register a CAGR of 10.14% from 2026 to 2035 as polymerase chain reaction panels and sequencing methods identify pathogens and resistance genes directly from blood or positive cultures. Results arrive within about an hour, which allows clinicians to adjust therapy sooner. Cartridge-based systems need little technical training, which supports use in smaller hospitals and emergency departments. Hospital laboratories are also testing sequencing for difficult cases, although cost and workflow complexity limit its use for now.
By Pathogen, Bacterial Infections Dominate Sepsis Diagnostics Market; Fungal Infections to Register Fastest Growth.
Bacterial infections accounted for a 77.41% share in 2025 because bacteria such as Escherichia coli, Staphylococcus aureus, and Klebsiella species cause most cases of sepsis. Testing is directed at identifying these organisms and their resistance patterns, and hospital protocols focus on prompt antibiotic therapy. Rising antimicrobial resistance increases the need for susceptibility tests, which keeps spending on bacterial diagnostics high across all regions. Surveillance programs also track resistant organisms, which keeps laboratories focused on bacterial identification and susceptibility profiling.
Fungal infections are projected to grow at a CAGR of 9.14% from 2026 to 2035 as more patients have weakened immune systems from cancer treatment, transplants, and prolonged intensive care. Invasive candidiasis is hard to detect with culture alone, so laboratories adopt molecular and biomarker tests to find it earlier. Rising resistance in Candida species also drives interest in rapid identification. Antifungal stewardship efforts are encouraging earlier testing in high-risk wards, and suppliers are adding fungal targets to multiplex panels.
By End User, Hospitals and Clinics Dominate Sepsis Diagnostics Market; Pathology and Reference Laboratories to Register Fastest Growth.
Hospitals and clinics held a 76.83% share in 2025 because sepsis is diagnosed and treated in emergency rooms, wards, and intensive care units, where on-site laboratories run cultures and panels around the clock. Hospital sepsis programs require rapid turnaround, so large systems invest in their own instruments and staffing. Purchasing is often centralized across health networks, which favors suppliers that offer complete workflows from bottles to software. Standard order sets in electronic records also route most samples to these laboratories.
Pathology and reference laboratories are expected to register the fastest CAGR of 9.34% from 2026 to 2035, as smaller hospitals outsource complex testing and laboratory networks consolidate. Large reference laboratories handle high volumes and can justify investment in automation, mass spectrometry, and molecular platforms. Courier networks and digital reporting allow them to serve distant hospitals with competitive turnaround. Private laboratory chains in several countries are also expanding blood culture services to win contracts from smaller hospitals and clinics.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
92.83% |
|
Europe |
Germany |
23.46% |
|
Asia Pacific |
China |
38.17% |
|
Middle East & Africa |
Saudi Arabia |
34.91% |
|
Latin America |
Brazil |
51.28% |
North America Sepsis Diagnostics Market
North America led the market with a 43.62% share in 2025, supported by widespread hospital sepsis programs, strong laboratory infrastructure, and early clearance of new tests and software. The United States generated USD 374.96 Million in 2025 and is projected to grow at a CAGR of 8.24% from 2026 to 2035. Large health systems standardize sepsis protocols across hospitals, while Canada adds demand through provincial quality programs. Group purchasing contracts also shape supplier selection for culture bottles and rapid panels across large networks.
Regulatory clearance of blood tests and software for sepsis from the Food and Drug Administration gives American hospitals early access to new tools, and hospital networks run pilots across several sites. Laboratories consolidate culture and molecular testing in central facilities, and suppliers compete on automation, menu breadth, and integration with electronic health records. Staffing shortages in microbiology laboratories encourage adoption of automated systems. Quality programs run by hospital associations and state agencies also encourage adoption of sepsis protocols across many community hospitals.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Sepsis Diagnostics Market
Europe is the second largest regional market in 2025. Germany leads the region, followed by the United Kingdom, France, Italy, and Spain. National health systems fund laboratory services through central budgets, so procurement is tender based and focused on cost per test. Large academic hospitals in Germany and France adopt molecular panels earlier, while smaller hospitals rely on culture and mass spectrometry. Pooled procurement between neighboring hospitals also helps smaller sites obtain advanced systems at lower cost.
Stewardship programs and national action plans on antimicrobial resistance support demand for rapid identification and susceptibility testing. Laboratory consolidation in the Nordic countries, the Netherlands, and Germany raises throughput requirements and favors automated platforms. Southern and Eastern Europe still depend on manual workflows in many hospitals, which leaves a large base for upgrades once budgets allow. Reference laboratories in the United Kingdom and Germany handle growing volumes for smaller hospitals, which supports demand for high-throughput culture and identification systems across the region.
Asia Pacific Sepsis Diagnostics Market
The Asia Pacific is projected to grow at the highest rate, which is a CAGR of 9.08% during 2026 to 2035, owing to the growth in intensive care unit and laboratory in hospitals. China leads the market for the nation-wise growth in Asia Pacific owing to its well-developed hospital infrastructure and local diagnostic companies as well as increased adoption of molecular diagnostics. The market in Japan is developed and the adoption of automation in culture techniques is high. South Korea and Australia are the markets with good stewardship programs.
India is the fastest-growing country in Asia Pacific, due to expansion in the number of intensive care unit beds in private hospital chains and expansion in the laboratories for the sake of meeting accreditation guidelines. The Southeast Asian countries like Thailand, Malaysia, and Singapore are expanding sepsis testing in tertiary hospitals. Higher prevalence of infections and AMR drive the demand, whereas price sensitivity drives the adoption of local suppliers and flexible reagents. The hospitals that cater to medical tourists in Thailand and India invest in advanced laboratories.
Latin America Sepsis Diagnostics Market
Latin America accounted for 5.46% of the market in 2025, led by Brazil, which has the largest hospital network in the region. Mexico, Argentina, Chile, and Colombia follow, with demand concentrated in private hospital groups and large public referral centers. High infection rates in intensive care units and growing awareness of sepsis protocols support demand for blood culture systems and rapid identification tools in major cities. Public and private hospitals in the region also join patient safety programs that promote sepsis protocols in intensive care units.
Growth is supported by hospital accreditation programs, investment in private health networks, and public campaigns that promote early sepsis recognition. Currency swings raise the cost of imported reagents and instruments, so laboratories prefer reagent rental contracts and local distributors. Smaller hospitals still depend on manual culture methods, which leaves room for automation as budgets improve. Regional distributors provide training and technical support for culture systems, and larger hospital groups negotiate multi-year agreements that bundle instruments, bottles, and service for several sites.
Middle East & Africa Sepsis Diagnostics Market
The Middle East and Africa market growth is driven in the region by new hospitals, medical cities, and mandatory national accreditation with the biggest share of demand in each country belonging to Saudi Arabia, followed by the United Arab Emirates and Qatar. Governments invest in intensive care facilities and laboratory services, and international manufacturers work with local distributors for installing automated solutions. Hospitals built in Saudi Arabia, the United Arab Emirates, and Qatar have modern laboratories demanding automated culture and identification systems from the very beginning.
In September 2024, the World Health Organization has introduced the Global Agenda for Sepsis until 2030, encouraging countries to enhance prevention, diagnostics and clinical management of this disease. The most advanced network of laboratories in Africa belongs to South Africa; insufficient culture capacity in other countries limits volume of tests performed. Training and donor programs help in building basic laboratory facilities for microbiology. Insufficient laboratory capacities, lack of specialized personnel and poor supply chain limit test volume in many African hospitals and therefore sepsis treatment is done without diagnostics.
Competitive Landscape
The Sepsis Diagnostics Market is moderately concentrated. Major diagnostics companies, instrument manufacturers, molecular diagnostic firms, and software companies all provide products for the diagnosis of sepsis, and no company controls more than 50 percent of revenue. Well-known vendors win business due to their culture systems and comprehensive menu of reagents, whereas new market players rely on host response testing and decision support software.
Three major strategies are adopted by vendors. Firstly, they develop rapid identification and susceptibility panels that perform directly on positive blood cultures. Secondly, they incorporate automation and throughput into their culture systems to cater to increasing demand. Lastly, they focus on host response testing and artificial intelligence technologies, which assist clinicians in detecting sepsis earlier.
Sepsis Diagnostics Market Industry Leaders
1. bioMérieux: Supplies blood culture, identification, and susceptibility systems, including the VITEK REVEAL rapid susceptibility platform.
2. Roche Diagnostics: Offers Elecsys procalcitonin and interleukin-6 assays and cobas eplex blood culture identification panels.
3. BD (Waters): Provides BD BACTEC blood culture systems, which moved into the Waters combination in 2026.
4. Qiagen: Develops QIAstat-Dx syndromic panels for bloodstream infection with resistance markers.
5. Bruker: Delivers MALDI Biotyper mass spectrometry systems for microbial identification.
Companies Covered in this Report
- bioMérieux
- Roche Diagnostics
- BD (Waters)
- Qiagen
- Bruker
- Immunexpress
- Prenosis
- Bayesian Health
- Inflammatix
Recent Industry Developments
- January 2025: Inflammatix received U.S. Food and Drug Administration marketing authorization for the TriVerity host-response test for suspected sepsis and acute infection.
- February 2026: Prenosis raised USD 40.00 Million, including a federal contract, to expand its Sepsis ImmunoScore artificial intelligence diagnostic.
- March 2026: Immunexpress presented clinical data for its SeptiCyte RAPID host-response test at the Society of Critical Care Medicine congress.
- May 2026: Bayesian Health received U.S. Food and Drug Administration 510(k) clearance for its artificial intelligence sepsis monitoring tool.
- June 2026: Waters announced U.S. Food and Drug Administration clearance of the BD BACTEC FXI blood culture system.
- June 2026: Bruker expanded claims for its MALDI Biotyper CA System and introduced the Bruker Arc rapid susceptibility workflow at ASM Microbe 2026.
- August 2026: Qiagen received U.S. Food and Drug Administration clearance for the QIAstat-Dx BCID GPF Plus AMR Panel for bloodstream infections.
Scope and Research Methodology
The study defines the Sepsis Diagnostics Market as in vitro diagnostic products and diagnostic software used to detect sepsis, identify the causative pathogen, and guide treatment. Covered offerings include blood culture media and bottles, assay kits and reagents, analyzers and identification instruments, and software for risk prediction and monitoring. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. Therapeutics, general hospital information systems, and routine chemistry tests that are not used for sepsis assessment are excluded. Contract research services and veterinary diagnostics are not counted, and only products used in human patients are included in the market.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations, regulatory filings, clinical guidelines, health agency databases, product documentation, and peer-reviewed publications. Primary research consists of structured interviews and surveys with microbiologists, intensivists, laboratory directors, procurement heads, and diagnostics executives across the value chain. These discussions validate assumptions on test volumes, technology mix, pricing, and adoption of rapid methods. Responses are cross-checked against company disclosures, and interview findings are weighted by the relevance and seniority of each respondent. Where information is partial, estimates are tested against installed base and test volume data.
Market engineering follows a bottom-up build from test volumes, case counts, and vendor revenue, cross-checked top-down against hospital laboratory spending and sepsis incidence indicators. Triangulation across both approaches narrows differences before values are finalized. Forecasts reflect drivers such as guideline changes, payment policy, and new test approvals. Regional estimates are aligned so that country values add to regional totals, and each estimate passes through an analyst quality review before publication. Sensitivity checks test the effect of changes in adoption speed, pricing, and regulation on each segment, and global totals equal the sum of regional values.
Sepsis Diagnostics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 926.00 Million |
| Market Size by 2035 | USD 1.99 Billion |
| CAGR | CAGR of 7.94% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Blood Culture Media, Assay Kits and Reagents, Instruments, and Software) • By Technology (Microbiology, Molecular Diagnostics, Immunoassay, and Others) • By Pathogen (Bacterial, Fungal, and Others) • By End User (Hospitals and Clinics, Pathology and Reference Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | bioMérieux, Roche Diagnostics, BD (Waters), Qiagen, Bruker, Immunexpress, Prenosis, Bayesian Health, Inflammatix |

Frequently Asked Questions
The market was valued at USD 926.00 Million in 2025 and is projected to reach USD 1.99 Billion by 2035 at a CAGR of 7.94%.
North America led the market with a 43.62% share in 2025, supported by hospital sepsis programs and early clearance of new tests.
Asia Pacific is expected to grow the fastest, at a CAGR of 9.08% from 2026 to 2035.
Blood culture media, microbiology, bacterial infections, and hospitals and clinics hold the largest shares in their segments.
Assay kits and reagents, molecular diagnostics, fungal infections, and pathology and reference laboratories are the fastest growing segments.
