
Cell Lysis and Disruption Market Report Scope & Overview:
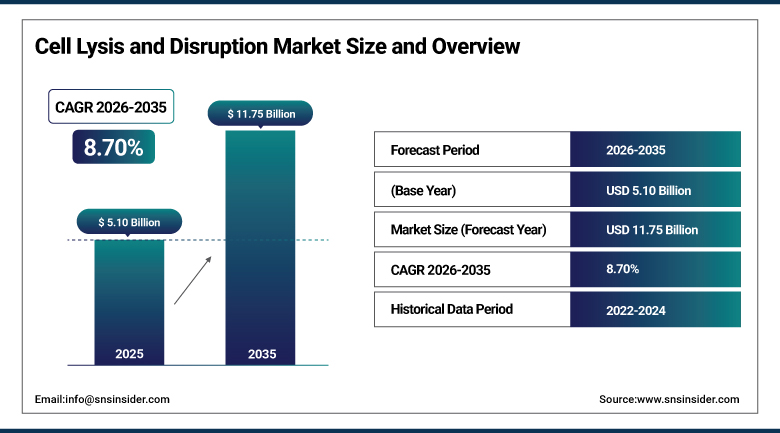
The Cell Lysis and Disruption Market was valued at USD 5.10 Billion in 2025 and is expected to reach USD 11.75 Billion by 2035, growing at a CAGR of 8.70% from 2026-2035.
The Cell Lysis and Disruption Market covers reagents, kits and instruments that break open cells to release proteins, nucleic acids, organelles and viral vectors for research, diagnostics and biopharmaceutical manufacturing. Methods include detergent and enzyme-based lysis, bead milling, homogenization, sonication, micro fluidization and high-pressure disruption. Growth is supported by biologics and gene therapy manufacturing, proteomics and genomics research, and molecular diagnostics, while lysis efficiency at scale, damage to sensitive products, cost of single-use consumables and the need for validated, reproducible workflows shape adoption.
⮞In July, 2024, Avantor launched the J.T.Baker Cell Lysis Solution and J.T.Baker Endonuclease for the gene therapy harvest process. The lysis solution is a biodegradable alternative to Octoxynol-9, a substance of very high concern under REACH, and together with the endonuclease can reduce the number of harvest steps in adeno-associated virus production.
To Get more information Cell Lysis and Disruption Market - Request Free Sample Report
Cell Lysis and Disruption Market Trends
- Growth of viral vector and cell therapy manufacturing that needs gentle, scalable lysis
- Replacement of restricted detergents with biodegradable lysis reagents
- Adoption of automated, high-throughput homogenizers for omics sample preparation
- Use of single-use and closed-system disruption in biopharmaceutical production
- Rising demand for lysis workflows that feed digital PCR and sequencing
- Integration of lysis with purification in kits to reduce hands-on time
U.S. Cell Lysis and Disruption Market Outlook
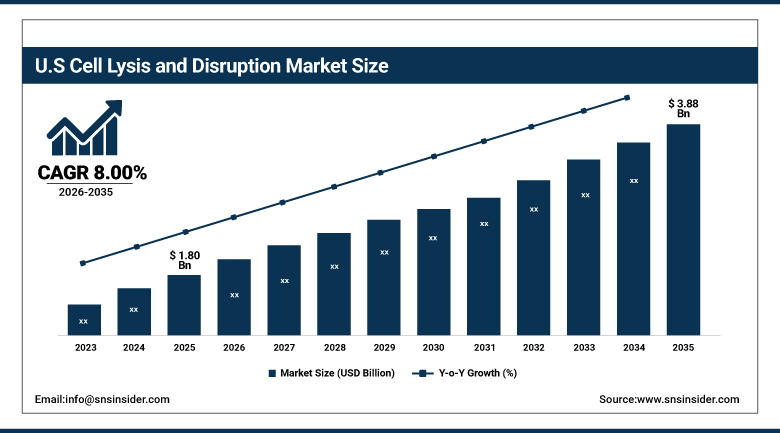
The U.S. Cell Lysis and Disruption Market was valued at USD 1.80 Billion in 2025 and is expected to reach USD 3.88 Billion by 2035, growing at a CAGR of 8.00% from 2026-2035.
The U.S. Cell Lysis and Disruption Market is the largest national market, supported by a dense base of biopharmaceutical manufacturers, genomics and proteomics laboratories, academic medical centers and life science tool suppliers. Demand comes from drug discovery, biologics and cell and gene therapy production, and molecular diagnostics. Federal research funding, contract development and manufacturing growth and local bioprocessing investment support steady orders. Growth is moderated by research budget swings and by pressure to reduce consumable cost.
⮞In February, 2025, Thermo Fisher Scientific signed an agreement to acquire Solventum's purification and filtration business for about USD 4.10 billion in cash. The business generated roughly USD 1 billion of revenue in 2024 and complements Thermo Fisher's bioproduction offering across upstream and downstream workflows.
Cell Lysis and Disruption Market Segment Analysis
- By Product, reagents and consumables segment dominated the Cell Lysis and Disruption Market in 2025 with an estimated 66.00% share; instruments segment is the fastest-growing segment, with an estimated CAGR of 9.40% during 2026–2035.
- By Cell Type, mammalian cells segment dominated the Cell Lysis and Disruption Market in 2025 with an estimated 48.00% share; yeast, fungi and algae cells segment is the fastest-growing segment, with an estimated CAGR of 10.40% during 2026–2035.
- By Technique, mechanical disruption segment dominated the Cell Lysis and Disruption Market in 2025 with an estimated 55.00% share; enzymatic lysis segment is the fastest-growing segment, with an estimated CAGR of 10.10% during 2026–2035.
- By Application, protein isolation segment dominated the Cell Lysis and Disruption Market in 2025 with an estimated 35.00% share; nucleic acid isolation segment is the fastest-growing segment, with an estimated CAGR of 10.30% during 2026–2035.
By Product, Reagents and Consumables Dominates Cell Lysis and Disruption Market; Instruments to Register Fastest Growth.
Reagents and consumables dominate the Cell Lysis and Disruption Market because every experiment and production batch uses lysis buffers, detergents, enzymes, kits, beads and tubes that must be replaced each time. Repeat purchases create recurring revenue for suppliers, and laboratories prefer validated, ready-to-use formulations that give consistent yields. Pharmaceutical manufacturers also buy enzymes such as nucleases in bulk, and quality-grade products for good manufacturing practice add value to the segment. Suppliers also bundle reagents with instruments to lock in long-term consumable use. Standardized kits also reduce operator variation.
Instruments are projected to register the fastest growth as laboratories and manufacturers invest in homogenizers, bead mills, sonicators, microfluidizers and high-pressure disruptors that process more samples with less effort. Automated systems improve reproducibility and protect sensitive proteins, which matters for omics workflows and biologics development. Scale-up of cell therapy and vaccine production also requires disruption equipment that can be validated, cleaned and integrated with downstream purification trains. Service contracts and software for protocol control add a recurring layer of revenue for vendors.
By Cell Type, Mammalian Cells Dominates Cell Lysis and Disruption Market; Yeast, Fungi and Algae Cells to Register Fastest Growth.
Mammalian cells dominate the Cell Lysis and Disruption Market because most biologics, monoclonal antibodies, recombinant proteins and viral vectors are produced in mammalian cell lines such as Chinese hamster ovary and human embryonic kidney cells. These cells have soft membranes that can be lysed with mild detergents or gentle mechanical methods, which preserves protein structure. Drug discovery, cell biology and diagnostics research also work mainly with mammalian cells, supporting steady demand for kits. Contract manufacturers running these cell lines for several clients also create large and repeated purchasing programs.
Yeast, fungi and algae cells are projected to register the fastest growth because they are used to produce enzymes, vaccines, bio-based chemicals, food ingredients and omega-3 oils. Their tough cell walls need strong mechanical force, specialized enzymes or high-pressure systems, which raises the value of disruption equipment and reagents. Bacterial cells remain important for recombinant protein and plasmid production, while plant cells add smaller but growing demand in agricultural research and natural product extraction. Tissue-like cell clumps and spores can need specialized steps, and suppliers are developing tailored kits and enzymes.
By Technique, Mechanical Disruption Dominates Cell Lysis and Disruption Market; Enzymatic Lysis to Register Fastest Growth.
Mechanical disruption dominates the Cell Lysis and Disruption Market because bead milling, homogenization, sonication and high-pressure methods work across cell types and tissues, and do not rely on detergents that can interfere with downstream analysis. Research laboratories use bead mills for tough samples such as soil, spores and tissue, while industrial users use high-pressure homogenizers to process large volumes of bacterial and yeast cultures. Established instruments and broad applicability keep this technique ahead. Easy automation and compatibility with many sample types also make this the standard choice for core laboratories.
Enzymatic lysis is projected to register the fastest growth because enzymes such as lysozyme, lyticase and nucleases release cell contents gently, work under mild conditions and can be tuned to a cell type. Gene therapy and cell therapy manufacturers prefer gentle methods that protect fragile viral vectors, and enzymes reduce the need for harsh detergents. Chemical lysis with detergents remains widely used for routine protein work, while ultrasonic and thermal methods serve specialized samples. Combination protocols, such as brief mechanical shearing followed by enzymes, are also becoming common.
By Application, Protein Isolation Dominates Cell Lysis and Disruption Market; Nucleic Acid Isolation to Register Fastest Growth.
Protein isolation dominates the Cell Lysis and Disruption Market because extracting proteins from cells is a basic step in proteomics, antibody development, enzyme production and recombinant biologics manufacturing. Researchers need reproducible lysis that keeps proteins intact for purification, assays and structural work. Biopharmaceutical processes harvest therapeutic proteins from cell cultures after lysis, and the scale of these operations makes protein isolation the largest application by value. Mass spectrometry laboratories also rely on efficient, clean extractions for accurate quantification. Reproducible yields are therefore a key buying criterion.
Nucleic acid isolation is projected to register the fastest growth as genomics, molecular diagnostics, sequencing and digital PCR workflows expand. Clinical laboratories, infectious disease testing and cancer diagnostics rely on efficient lysis to release DNA and RNA from blood, tissue and microbial samples. Gene therapy developers also need to quantify viral genomes after lysis. Cell organelle isolation and downstream processing add specialized demand in cell biology and biomanufacturing. Companion diagnostics and liquid biopsy programs add further demand for reliable extraction.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
86.00 |
|
Europe |
Germany |
28.00 |
|
Asia Pacific |
China |
43.00 |
|
Latin America |
Brazil |
58.00 |
|
Middle East & Africa |
Saudi Arabia |
27.00 |
North America Cell Lysis and Disruption Market Insights
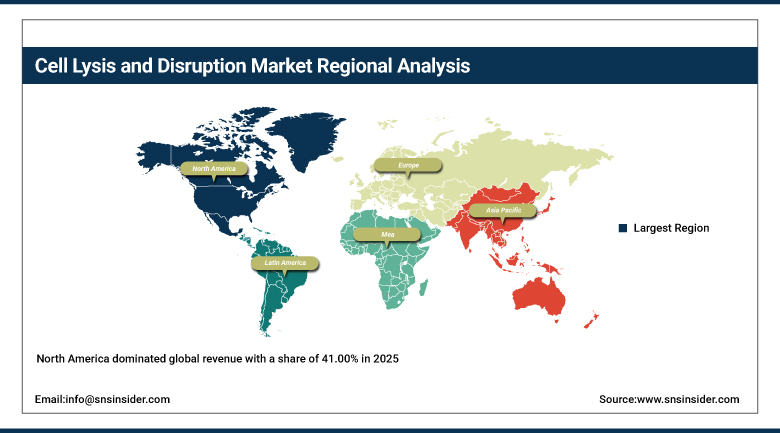
North America dominated global revenue with a share of 41.00% in 2025. The United States accounts for about 86.00% of regional demand, with Canada contributing through research institutes and biomanufacturing. Thermo Fisher Scientific, Danaher, Bio-Rad Laboratories, Avantor, Parr Instrument, Covaris, Promega and New England Biolabs are among the suppliers serving researchers and manufacturers. Canada adds demand through research hospitals, vaccine developers and contract laboratories. Pharmaceutical hubs in Massachusetts, North Carolina and California lead purchases.
The region has the largest base of biopharmaceutical companies, contract manufacturers, academic centers and sequencing laboratories, and benefits from strong research funding. Cell and gene therapy production is growing quickly, creating demand for scalable lysis reagents and nucleases. Research funding changes, cost control by laboratories and consolidation among customers can slow orders in some years, but the pipeline of biologics keeps demand strong. Large pharmaceutical companies also place long-term supply agreements with tool suppliers, which gives stability to reagent and consumable volumes across the region and encourages suppliers to invest in local capacity.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Cell Lysis and Disruption Market Insights
In Europe Germany leads regional demand, followed by the United Kingdom, France, Switzerland and the Netherlands, supported by pharmaceutical companies, research universities and biotechnology clusters. Qiagen, Merck KGaA, Eppendorf, Miltenyi Biotec, Sartorius, Roche and Bertin Technologies are among the major suppliers headquartered in the region. Contract research and manufacturing organizations in Switzerland, Ireland, Denmark and Belgium add demand through large viral vector and recombinant protein facilities that serve global sponsors, while Nordic countries support strong academic research.
European regulation shapes product choice, as REACH restrictions on certain detergents push suppliers toward biodegradable lysis reagents. The region has strong academic research in genomics and proteomics, and contract manufacturers are expanding capacity for viral vectors and recombinant proteins. Fragmented funding across countries and cost pressure on public laboratories temper growth, although regional leadership in analytical instruments supports exports to other markets. Instrument makers in Germany and the United Kingdom export homogenizers and high-pressure disruptors worldwide, and close cooperation between universities and industry supports steady product development across the region.
⮞In June, 2025, Bio-Rad Laboratories announced and closed its acquisition of Stilla Technologies, a France-based maker of droplet digital PCR systems, for total purchase consideration of about USD 257.70 million. The deal strengthens Bio-Rad's digital PCR offering for nucleic acid analysis workflows that begin with cell lysis.
Asia Pacific Cell Lysis and Disruption Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 11.20% during 2026-2035. China leads regional demand, followed by Japan, South Korea, India and Singapore, supported by growth in contract research, clinical trials, biologics manufacturing and healthcare infrastructure. Takara Bio, Shimadzu and a growing set of Chinese reagent makers compete with multinational suppliers. Australia and Singapore add demand through research institutes and regional hubs for biologics manufacturing, while India is growing as a center for vaccine, biosimilar and contract development work that needs reliable reagents and equipment. Rising biotechnology start-ups also help.
Governments are funding biotechnology parks and vaccine and biologics capacity, and global pharmaceutical companies are outsourcing research and manufacturing to the region. Local manufacturers are gaining share in basic reagents and kits through lower prices, while multinational firms lead in high-end instruments and good manufacturing practice grade products. Variable quality standards and import dependence for specialized enzymes remain challenges, but rising research spending sustains rapid growth. Academic research funding in China, Japan and South Korea also supports strong purchases of homogenizers, sequencing sample preparation tools and high-throughput lysis systems.
MEA & Latin America Cell Lysis and Disruption Market Insights
In Latin America, Brazil leads on the strength of its research universities, vaccine producers and growing biotechnology sector, followed by Mexico, Argentina and Chile. Regional demand supported by public research funding and diagnostics growth. Most products are imported and sold through distributors, so price and logistics shape purchasing. Colombia and Peru add smaller volumes through universities, and vaccine and diagnostics programs in the region sustain demand for basic lysis kits, centrifuges and consumables used in public health laboratories and hospitals.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, and South Africa lead demand. Genomics programs, new research institutes and pharmaceutical localization policies in the Gulf are creating demand for laboratory consumables and instruments. Limited local manufacturing, import costs and a shortage of trained researchers restrain adoption across much of Africa. Egypt, Turkey and Nigeria add smaller volumes through universities and diagnostics laboratories, and international development funding supports equipment purchases for genomic and infectious disease programs in the region.
Market Dynamics
Growth Drivers: Biologics, Gene Therapy and Omics Research
Growth of biologics and gene therapy manufacturing is a central driver of the Cell Lysis and Disruption Market. Monoclonal antibodies, recombinant proteins, viral vectors and cell therapies all require cells to be opened to recover the product, and manufacturers need reagents and equipment that work at scale. Each new clinical program adds demand for validated lysis and nuclease reagents. Government funding for pandemic preparedness and vaccine research further supports reagent purchases. Rising investment in precision medicine adds to sample volumes.
Proteomics, genomics and molecular diagnostics are a second driver. Sequencing, mass spectrometry and digital PCR workflows start with sample preparation, and laboratories are automating this step to process more samples with consistent quality. Rising research funding in Asia and growth of clinical testing add to demand for kits and homogenizers. Outsourcing to contract laboratories is also increasing the number of companies purchasing lysis products. Cell-free manufacturing is a long-term opportunity.
Restraints: Scale-Up Challenges, Product Damage and Cost
Lysing cells at large scale without damaging the product is difficult. Heat, shear and harsh detergents can degrade proteins and viral vectors, and manufacturers must validate each step, which lengthens process development. Some methods that work in the laboratory do not scale, forcing costly redesign. Tough cell walls in yeast, fungi and spores require strong methods that can be harder to control. Tight budgets and slow grant cycles can postpone equipment purchases.
Consumable and instrument costs weigh on academic laboratories with limited budgets, and regulations on certain detergents force reformulation. Variability between cell types means that no single method suits all samples, so users often buy several products, which complicates purchasing and adds training needs. Switching suppliers can require revalidation, which discourages price-driven changes in regulated processes. Variation between lots of enzymes can complicate quality control.
Opportunities: Greener Reagents, Automation and Cell and Gene Therapy
Biodegradable lysis reagents that replace restricted detergents offer suppliers a route to win business in regulated markets, particularly in gene therapy and pharmaceutical manufacturing. Automation of sample preparation also offers growth as laboratories seek to increase throughput and reduce errors. Instrument makers can add value by pairing equipment with software that records parameters for audit. Single-use disruption systems reduce cleaning needs and cross-contamination risk.
Cell and gene therapy production is a large opportunity because it needs gentle, closed and scalable lysis steps linked to analytics. Kits that connect lysis to digital PCR or sequencing can shorten workflows and add value for biopharma customers and contract laboratories. Emerging markets investing in biologics plants also represent first-time buyers of complete workflows.
⮞In August 2023, Qiagen launched a CGT Viral Vector Lysis Kit for digital PCR workflows that begin with cell lysates, enabling quantification of viral titers across multiple serotypes on its QIAcuity system.
Recent Developments:
- In June 2025, Bio-Rad Laboratories completed the acquisition of Stilla Technologies, a French maker of droplet digital PCR systems, for about USD 257.70 million. The deal broadens Bio-Rad's molecular testing offering.
- In February 2025, Thermo Fisher Scientific agreed to acquire Solventum's purification and filtration business for about USD 4.10 billion. The business supports biologics production across downstream workflows.
- In July 2024, Avantor launched the J.T.Baker Cell Lysis Solution and J.T.Baker Endonuclease for gene therapy harvest. The products offer a biodegradable alternative to a substance of very high concern under REACH.
- In August 2023, Qiagen launched a CGT Viral Vector Lysis Kit for digital PCR workflows. The kit supports absolute quantification of viral titers across multiple serotypes.
Cell Lysis and Disruption Market Key Players are:
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- QIAGEN N.V.
- Merck KGaA
- Bio-Rad Laboratories, Inc.
- F. Hoffmann-La Roche Ltd
- Becton, Dickinson and Company
- Agilent Technologies, Inc.
- Eppendorf SE
- Miltenyi Biotec
- Takara Bio Inc.
- Promega Corporation
- New England Biolabs, Inc.
- Covaris, LLC
- Microfluidics International Corporation
- Parr Instrument Company
- Bertin Technologies
- Constant Systems Ltd
- Avantor, Inc.
- Sartorius AG
Cell Lysis and Disruption Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.10 Billion |
| Market Size by 2035 | USD 11.75 Billion |
| CAGR | CAGR of 8.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Reagents and Consumables, and Instruments) • By Cell Type (Mammalian Cells, Bacterial Cells, Yeast, Fungi and Algae Cells, and Plant Cells) • By Technique (Mechanical Disruption, Chemical Lysis, Enzymatic Lysis, and Ultrasonic and Thermal Methods) • By Application (Protein Isolation, Nucleic Acid Isolation, Cell Organelle Isolation, and Downstream Processing) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Thermo Fisher Scientific Inc.; Danaher Corporation; QIAGEN N.V.; Merck KGaA; Bio-Rad Laboratories, Inc.; F. Hoffmann-La Roche Ltd; Becton, Dickinson and Company; Agilent Technologies, Inc.; Eppendorf SE; Miltenyi Biotec; Takara Bio Inc.; Promega Corporation; New England Biolabs, Inc.; Covaris, LLC; Microfluidics International Corporation; Parr Instrument Company; Bertin Technologies; Constant Systems Ltd; Avantor, Inc.; Sartorius AG |

Frequently Asked Questions
Key players include Thermo Fisher Scientific Inc., Danaher Corporation, QIAGEN N.V., Merck KGaA, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company and Agilent Technologies, Inc.
Key opportunities include biodegradable lysis reagents, automated sample preparation, and scalable lysis for cell and gene therapy production.
The major growth factor is expansion of biologics and gene therapy manufacturing, together with growth in proteomics, genomics and molecular diagnostics workflows.
By Product, the Reagents and Consumables segment dominated the market in 2025 with an estimated 66.00% share, supported by repeat purchases of buffers, enzymes and kits.
North America dominated the market with a share of 41.00% in 2025, driven by a large base of biopharmaceutical manufacturers, research institutions and life science tool suppliers.
