
Centrifugal Pump Market Report Scope & Overview:
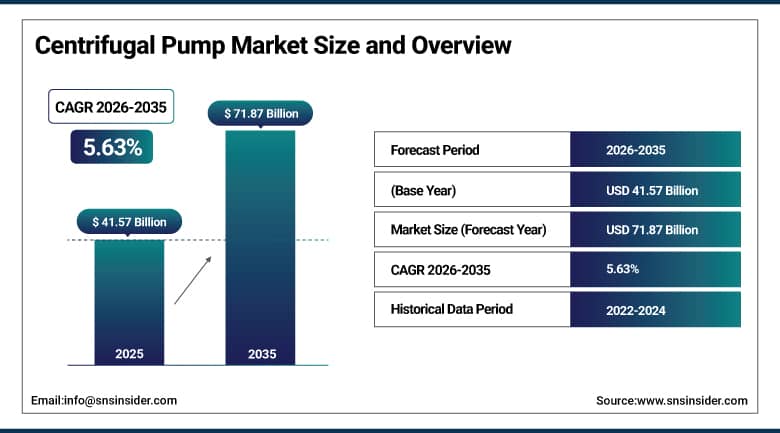
The Centrifugal Pump Market was valued at USD 41.57 Billion in 2025 and is expected to reach USD 71.87 Billion by 2035, growing at a CAGR of 5.63% from 2026-2035.
Centrifugal pumps are one of those pieces of industrial equipment that rarely get much attention until something goes wrong, but they're quietly moving fluid through almost every major infrastructure system in the world, water treatment plants, power stations, chemical facilities, irrigation networks, and oil and gas operations all depend on them running reliably day after day. What's pushing demand higher right now is a genuine convergence of forces: aging water infrastructure across developed economies needs replacing, rapidly industrializing economies need new pumping capacity to support growing cities and factories, and energy efficiency regulations are pushing operators to swap out older, less efficient units for modern equivalents faster than they otherwise might. Add in the growing appeal of smart, IoT-enabled pumps that can flag maintenance needs before a failure actually happens, and it's clear why this market keeps expanding at a pace well ahead of general industrial growth.
In March 2025, Flowserve Corporation launched INNOMAG TB-MAG Dual Drive, the world's first sealless magnetic drive centrifugal pump featuring true secondary containment. Sealless magnetic drive technology eliminates the mechanical seals that have traditionally been a common failure point and safety concern in pumps handling hazardous or toxic fluids, and adding true secondary containment on top of that design takes the safety case a step further still, giving operators in chemical processing and other demanding applications a genuinely differentiated option for handling their most sensitive fluid transfer requirements.
To Get More Information On Centrifugal Pump Market - Request Free Sample Report
Centrifugal Pump Market Trends
-
Rising adoption of IoT-enabled smart pumps supporting predictive maintenance and real-time performance monitoring.
-
Growing demand for energy-efficient electric-driven pumps replacing older, less efficient diesel and hydraulic units.
-
Expanding use of corrosion-resistant materials extending pump service life in aggressive fluid-handling applications.
-
Increasing investment in desalination infrastructure driving demand for large-scale centrifugal pumping systems.
-
Rising consolidation among pump manufacturers through targeted acquisitions expanding water technology portfolios.
-
Growing replacement demand as aging municipal water infrastructure across developed markets nears end of service life.
U.S. Centrifugal Pump Market Outlook
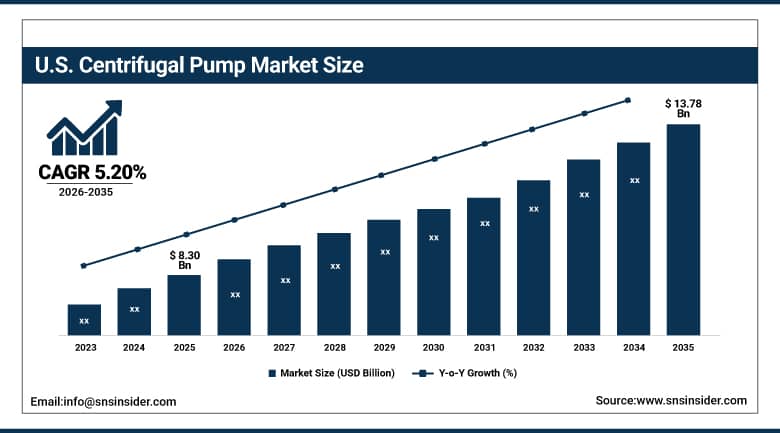
The U.S. Centrifugal Pump Market was valued at USD 8.30 Billion in 2025 and is expected to reach USD 13.78 Billion by 2035, growing at a CAGR of 5.20% from 2026-2035.
The U.S. market is served by an extensive and old installed base of water infrastructure, which is at a point of needing replacement rather than maintenance. In 2024, the U.S. Environmental Protection Agency provided funding towards efficiency improvements in urban and industrial infrastructures, such as pumps, a change in policy that has led to more frequent replacement cycles for municipal water utilities and industrial sites. Apart from water infrastructure, the United States has major sectors in oil and gas processing, chemical processing and power generation, all of which require regular replacement and development, alongside the adoption of smart pumps based on IoT and SCADA monitoring.
On December 10, 2024, Xylem completed its acquisition of Global Omnium Idrica S.L. for total consideration of approximately $637 million, a deal that significantly expands the company's water technology and digital solutions portfolio. That's a substantial acquisition even by the standards of a company Xylem's size, and it reflects a broader pattern among leading domestic pump manufacturers of pursuing digital and data-driven water technology capability alongside their traditional hardware business, recognizing that customers increasingly want intelligence and analytics bundled with their fluid-handling equipment rather than purchased as an afterthought.
Centrifugal Pump Market Segment Analysis
-
By Stage, the Single-Stage segment dominated the Centrifugal Pump Market with approximately 62.60% share in 2025, while the Multi-Stage segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Flow, the Radial Flow segment dominated the Centrifugal Pump Market with approximately 64.10% share in 2025, while the Mixed Flow segment is the fastest growing with a CAGR of approximately 6.90%.
-
By Operation Type, the Electrical segment dominated the Centrifugal Pump Market with approximately 58.60% share in 2025, and is also the fastest growing with a CAGR of approximately 7.40%.
-
By Impeller Type, the Enclosed segment dominated the Centrifugal Pump Market with approximately 68.60% share in 2025, while the Semi-Open segment is the fastest growing with a CAGR of approximately 7.00%.
-
By End-User, the Water & Wastewater segment dominated the Centrifugal Pump Market with approximately 36.60% share in 2025, while the Chemical Processing segment is the fastest growing with a CAGR of approximately 7.60%.
By Stage Type, Single-Stage Dominates the Centrifugal Pump Market and Multi-Stage Grows Fastest
Single-stage pumps hold a commanding lead in this market, and their leadership comes down to a genuinely practical combination: cost-effectiveness, operational simplicity, and broad applicability across water supply, wastewater treatment, irrigation, commercial facilities, and general industrial operations. When an application doesn't demand exceptionally high pressure, a single-stage design does the job reliably and cheaply, which is exactly why it remains the default choice across the widest range of pumping applications worldwide.
Multi-stage pumps are growing fastest, as applications requiring higher pressure, including deep well water extraction, boiler feed systems, and certain industrial processes, continue expanding across both developed and emerging markets. These pumps stack multiple impellers in series to build pressure well beyond what a single-stage design can deliver, and as industrial processes and infrastructure projects increasingly demand that higher-pressure capability, multi-stage pumps are capturing a growing share of new equipment orders.
By Flow, Radial Flow dominates the Centrifugal Pump Market and Mixed Flow shows fastest growth
The Radial Flow segment dominated the Centrifugal Pump Market owing to its widespread use across water and wastewater treatment, oil & gas, chemical processing, power generation, and industrial applications. Radial flow pumps are particularly suitable for applications requiring high pressure and moderate flow rates, making them effective for water supply, boiler feed, process fluid transfer, and pipeline systems. Their relatively simple design, operational reliability, broad availability, and ability to handle varying operating conditions further support their extensive installation across established industrial infrastructure.
The Mixed Flow segment is the fastest growing in the Centrifugal Pump Market driven by increasing demand for pumps capable of delivering high flow rates at moderate pressure levels. Mixed flow pumps combine characteristics of radial and axial flow designs, providing an effective balance between discharge capacity and pumping head. Their adoption is increasing in irrigation, flood control, drainage, municipal water supply, cooling-water circulation, and large-scale infrastructure projects. Expanding agricultural irrigation networks and water-management infrastructure are expected to further support demand for mixed flow centrifugal pumps.
By Operation Type, Electrical Dominates the Centrifugal Pump Market and Also Grows Fastest
Electric Operation dominates in this market since most of the centrifugal pumps deployed in different applications, whether municipal water or industrial, depend on electric motors, an option that is favored due to the high reliability and controllability of electricity in addition to the compatibility with variable frequency drive technology. The preference for electric operation will continue driving its dominance as the largest operation type category in virtually all end-use applications.
Electric Operation is also the fastest growing operation type category in the market due to trends toward electrification, emission standards and efforts to adopt energy-efficient systems which are delivered by electric motors especially those equipped with the variable frequency drive technology better than diesel and hydraulic motors. The replacement of older diesel and hydraulic pumps with newer electric counterparts in order to reach efficiency and emission requirements is adding further strength to the dominance of this operation type category.
By Impeller Type, Enclosed Dominates the Centrifugal Pump Market and Semi-Open Grows Fastest
Enclosed impeller designs dominate this market thanks to their superior efficiency for handling clean or lightly contaminated fluids, a design advantage that makes them the preferred choice across the majority of water supply, chemical processing, and general industrial pumping applications where fluid clarity isn't a major concern. That efficiency advantage in clean-fluid applications continues to sustain enclosed impellers' position as the largest impeller type category.
Semi-open impellers are growing fastest, largely because of their superior tolerance for slurry and particulate-laden fluids in demanding applications including mining and wastewater treatment. As mining operations and wastewater facilities alike continue expanding, particularly in rapidly industrializing regions, demand for impeller designs that can handle abrasive, particulate-heavy fluids without rapid wear is climbing faster than the broader enclosed-impeller-dominated market.
By End-User, Water & Wastewater Dominates the Centrifugal Pump Market and Chemical Processing Grows Fastest
Water and wastewater treatment represents the largest end-user category for centrifugal pumps, reflecting the sheer scale of municipal and industrial water infrastructure that depends on reliable pumping capacity to function at all. Rising wastewater treatment requirements, growing investment in water desalination, and the ongoing modernization of aging water infrastructure across both developed and emerging economies continue reinforcing this end-user category's position as the largest source of centrifugal pump demand.
Chemical processing is the fastest-growing end-user category, as expanding chemical manufacturing and processing activity worldwide continues driving demand for pumps engineered specifically to handle aggressive and process-critical fluids safely. Growth in specialty and industrial chemicals production keeps pushing demand for pumps with improved material compatibility and safety features, including the sealless, magnetic drive designs increasingly favored for handling hazardous chemical fluids, positioning chemical processing for above-market growth through the forecast period.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Middle East & Africa |
United Arab Emirates |
32.60% |
|
Latin America |
Brazil |
27.60% |
Asia Pacific Centrifugal Pump Market Insights
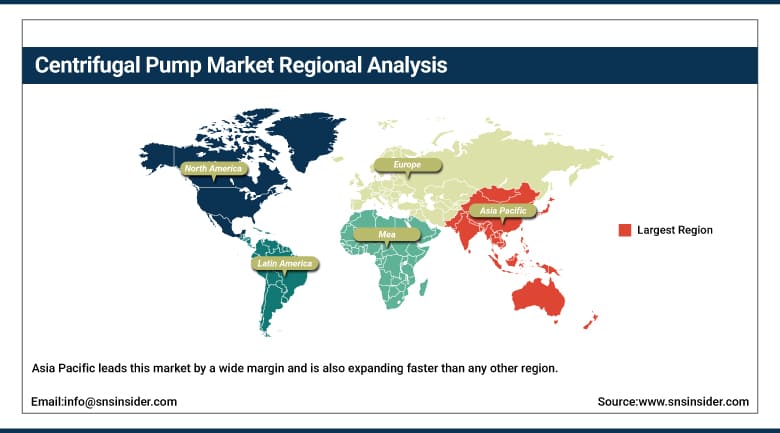
Asia Pacific leads this market by a wide margin and is also expanding faster than any other region, a combination driven by rapid industrialization and infrastructure development across China, India, and Southeast Asia. The region's massive urban expansion continues requiring new water supply, wastewater treatment, and industrial pumping capacity at a scale that keeps regional demand climbing well ahead of the global average.
China's substantial manufacturing base and infrastructure investment pipeline continue anchoring regional demand, while India's rapidly growing population and expanding industrial sector are becoming an increasingly significant growth driver in their own right. Southeast Asian markets are contributing additional scale as regional governments continue investing in water infrastructure and industrial development, keeping Asia Pacific firmly on track as both the largest and fastest-growing regional market through 2035.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Centrifugal Pump Market Insights
North America is seen contributing significantly to the global centrifugal pump market owing to the aged water infrastructure of the US and the need for continuous replacements. In addition, North America has already developed its industries, ranging from oil and gas, chemicals, to power generation industries. These industries still require regular investments in pumps for further development in spite of the slow pace of growth compared to emerging markets of Asia.
The contribution of Canada and Mexico to the demand in this region will be due to the continued development of water infrastructure and industrial base of these countries. With the continuous efforts being made at the domestic level for adoption of smart pumps through the EPA funding program, steady growth of the region is expected in the coming years.
Europe Centrifugal Pump Market Insights
Europe represents a significant share of the global centrifugal pump market, anchored by Germany's substantial industrial and manufacturing base. Infrastructure modernization, stringent regulatory systems, and increasing investment in energy-efficient and sustainable water management systems continue driving stable regional growth, as recent activities across the region focus on modernizing aging water infrastructure and minimizing leakage rates to meet EU stipulations.
France, Italy, and the United Kingdom contribute steady regional demand as their own water treatment and industrial sectors continue requiring reliable, efficient pumping systems. Regional manufacturers continue investing in energy-efficient designs to meet the EU's stringent sustainability targets, supporting continued steady growth even as the region's mature infrastructure base limits growth relative to faster-expanding emerging markets.
MEA & Latin America Centrifugal Pump Market Insights
The Middle East & Africa segment of the centrifugal pump market features the UAE and Saudi Arabia as leading countries due to continued demand for desalination projects which require high flow pumps. Governments have invested extensively in infrastructure to provide solutions to water shortages in the area, which guarantees continued above average growth throughout the period of forecast.
In Latin America, Brazil leads the segment with steady demand generated from an extensive industrial and agriculture sector present in the country. Growth is coming from Mexico where there is continuing expansion of industrial and agricultural activities in the region, while adoption of centrifugal pumps in Latin America is limited to larger industrial companies.
Market Dynamics
Growth Drivers: Water Infrastructure Modernization and Industrial Expansion
The global push to modernize aging water infrastructure represents the primary driver of centrifugal pump market growth, as municipal and industrial water systems across both developed and emerging economies increasingly require replacement or expansion to meet growing population and regulatory demands. Rising wastewater treatment requirements and growing investment in water desalination continue creating favorable conditions for centrifugal pump manufacturers and service providers across virtually every major regional market.
Rapid industrialization and infrastructure development represent a second major growth driver, as expanding power generation capacity, chemical processing activity, and oil and gas exploration and processing all require reliable fluid-handling systems that only well-engineered centrifugal pumps can provide at the scale modern industrial operations demand. Government-backed investment in advanced pumping and pipeline infrastructure continues reinforcing this trend, particularly across rapidly industrializing economies in Asia Pacific and the Middle East.
Restraints: Technical Skill Shortages and High Capital Investment
A lack of technical skills, funding, and infrastructure to properly manage, operate, and maintain centrifugal pump systems represents a meaningful restraint on market growth, particularly across emerging markets where the technical workforce needed to keep increasingly sophisticated, digitally connected pump systems running reliably remains in short supply relative to demand.
High capital investment requirements represent a further restraint, as large-scale industrial and municipal pumping systems command substantial upfront costs that can be genuinely difficult for smaller utilities and industrial operators to justify, particularly in price-sensitive emerging markets where budget constraints can delay necessary infrastructure investment even when the underlying need is clear.
Opportunities: Smart Pump Technology and Desalination Infrastructure Growth
Continued adoption of IoT-enabled smart pumps represents a substantial opportunity, as manufacturers that can deliver genuinely reliable predictive maintenance and real-time performance monitoring capability are positioned to differentiate themselves in an increasingly digitally-oriented industrial equipment market. Operators are increasingly willing to pay a premium for pumps that can flag maintenance needs before failure occurs, reducing costly unplanned downtime across critical infrastructure applications.
The continued expansion of desalination infrastructure offers a further avenue for growth, as water-scarce regions, particularly across the Middle East, continue investing in large-scale desalination mega-projects requiring substantial centrifugal pumping capacity. Manufacturers that can deliver reliable, high-capacity pumping systems suited to desalination's demanding operating conditions are well positioned to capture significant new demand as these projects continue advancing worldwide.
Recent Developments:
-
In September 2024, Grundfos acquired Culligan's commercial and industrial business in Italy, France, and the UK, expanding its position in the European water treatment market.
-
In October 2024, Sulzer launched the ZF-RO end-suction pump, matching the technical requirements of the energy recovery device booster pump service.
Centrifugal Pump Market Key Players
-
Grundfos Holding A/S
-
Xylem Inc.
-
Flowserve Corporation
-
Sulzer Ltd.
-
KSB SE & Co. KGaA
-
Wilo SE
-
ITT Inc.
-
Pentair plc
-
Ebara Corporation
-
Weir Group PLC
-
SPX FLOW, Inc.
-
Gorman-Rupp Company
-
Ruhrpumpen Group
-
Kirloskar Brothers Limited
-
Shanghai Kaiquan Pump (Group) Co., Ltd.
-
Torishima Pump Mfg. Co., Ltd.
-
Franklin Electric Co., Inc.
-
CIRCOR International, Inc.
-
Crane Co.
-
Eaton Corporation plc
Centrifugal Pump Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 41.57 Billion |
| Market Size by 2035 | USD 71.87 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Stage (Single-Stage, Multi-Stage) • By Flow (Radial, Axial, Mixed) • By Operation Type (Electrical, Diesel/Engine-Driven, Hydraulic) • By Impeller Type (Enclosed, Semi-Open, Open) • By End-User (Water & Wastewater, Oil & Gas, Power Generation, Chemical Processing, Agriculture, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Grundfos Holding A/S, Xylem Inc., Flowserve Corporation, Sulzer Ltd., KSB SE & Co. KGaA, Wilo SE, ITT Inc., Pentair plc, Ebara Corporation, Weir Group PLC, SPX FLOW, Inc., Gorman-Rupp Company, Ruhrpumpen Group, Kirloskar Brothers Limited, Shanghai Kaiquan Pump (Group) Co., Ltd., Torishima Pump Mfg. Co., Ltd., Franklin Electric Co., Inc., CIRCOR International, Inc., Crane Co., Eaton Corporation plc |

Frequently Asked Questions
Key players include Grundfos Holding A/S, Xylem Inc., Flowserve Corporation, Sulzer Ltd., KSB SE & Co. KGaA, Wilo SE, and ITT Inc., among other global pump manufacturers.
Continued adoption of IoT-enabled smart pumps and continued expansion of desalination infrastructure represent the biggest opportunities for centrifugal pump manufacturers.
Growth is driven mainly by the global push to modernize aging water infrastructure, combined with rapid industrialization and infrastructure development across emerging economies.
By Stage/Product Type, Single-Stage held approximately 62.60% share in 2025, reflecting its cost-effectiveness and broad applicability across water supply, wastewater, and general industrial applications.
Asia Pacific led with approximately 42.60% share in 2025, driven by rapid industrialization and infrastructure development across China, India, and Southeast Asia.
