
Commercial Vehicle Telematics Market Report Scope & Overview:
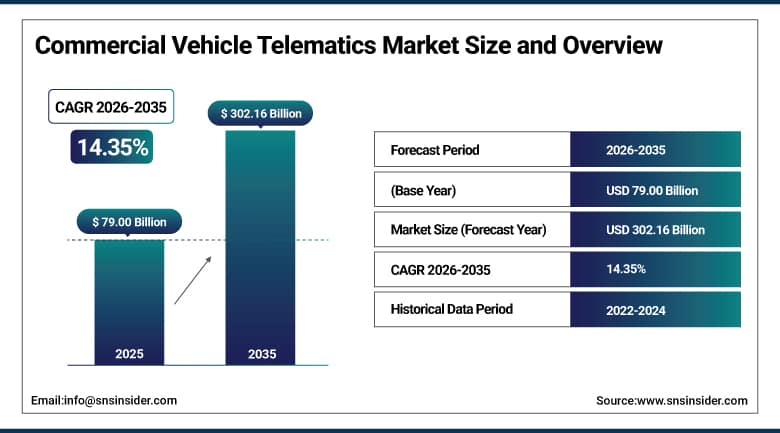
The Commercial Vehicle Telematics Market was valued at USD 79.00 Billion in 2025 and is expected to reach USD 302.16 Billion by 2035, growing at a CAGR of 14.35% from 2026-2035.
The primary factor driving Commercial Vehicle Telematics Market is growing adoption among fleet managers of connected vehicle information for purposes of lowering fuel bills, regulatory compliance and protecting profit margins amid the highly competitive environment in the freight and logistics industries. With the help of telematics solutions, which include on-board equipment, wireless network and cloud software, fleet managers get up-to-date information about location, driver performance, engine diagnostics and fuel consumption, turning this technology into an essential part of business operations. The demand is also driven by the regulatory requirements for compliance with drivers' working time regulations, vehicle load monitoring and emissions control. Integration of AI-based video analytics, predictive maintenance and 5G connection is further increasing the scope of benefits that can be gained through telematics, setting the stage for the fast growth of the industry throughout the next decade.
In October 2025, Geotab announced the acquisition of Verizon Connect's international commercial telematics operations across Australia, the United Kingdom, Ireland, Italy, France, Portugal, Poland, the Netherlands, and Germany, adding approximately 400 employees and significantly expanding its global footprint in the small to mid-sized fleet segment. The acquisition illustrates the accelerating consolidation underway across the commercial vehicle telematics industry as larger platform providers seek to expand international scale and deepen their fleet intelligence capabilities.
To Get More Information On Commercial Vehicle Telematics Market - Request Free Sample Report
Commercial Vehicle Telematics Market Trends:
-
Accelerating industry consolidation as larger telematics platform providers acquire regional and international operators.
-
Growing integration of AI-powered video telematics for driver safety scoring and incident classification.
-
Rising adoption of hybrid cellular-satellite connectivity architectures to close coverage gaps in remote operating areas.
-
Increasing demand for predictive maintenance analytics to reduce unplanned vehicle downtime.
-
Continued regulatory pressure around hours-of-service compliance and emissions tracking driving adoption.
U.S. Commercial Vehicle Telematics Market Outlook:
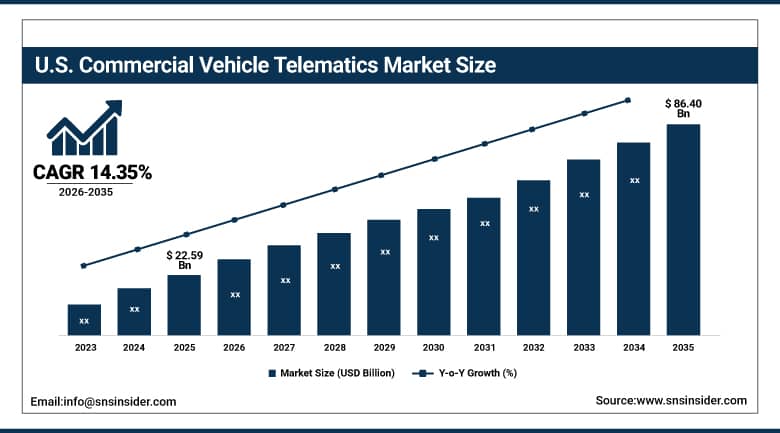
The U.S. Commercial Vehicle Telematics Market was valued at USD 22.59 Billion in 2025 and is expected to reach USD 86.40 Billion by 2035, growing at a CAGR of 14.35% from 2026-2035.
The growth of the U.S. Commercial Vehicle Telematics Market is still fueled by the large commercial trucking and logistics industry in the country, strict enforcement of regulations on electronic logging devices and hours of services, and investments in AI-driven safety and compliance solutions made by local fleet operators. This segment of demand is additionally driven by the presence of telematics platforms vendors in the United States that are growing through both innovation and acquisitions of other businesses. The rise of online commerce and last mile deliveries drives demand for telematics platforms providing real-time data on vehicle location and performance.
In October 2024, Powerfleet closed its acquisition of Fleet Complete, a prominent connected vehicle technology and fleet management provider, creating a combined company with more than USD 400 million in forecasted revenue, including over USD 300 million in recurring SaaS revenue and 2.6 million total combined subscribers. The transaction, headquartered at Powerfleet's Woodcliff Lake, New Jersey base, immediately scaled the company's presence across North America and Europe while strengthening its position in the fast-growing AI-powered video telematics market.
Commercial Vehicle Telematics Market Segment Analysis:
-
By Provider Type, the OEM segment dominated the Commercial Vehicle Telematics Market with approximately 58.71% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 15.14%.
-
By Vehicle Class, the Light Commercial Vehicles segment dominated the Commercial Vehicle Telematics Market with approximately 48.89% share in 2025, while the Heavy & Medium Trucks segment is the fastest growing with a CAGR of approximately 15.17%.
-
By Communication Technology, the Cellular segment dominated the Commercial Vehicle Telematics Market with approximately 82.33% share in 2025, while the Hybrid Architectures segment is the fastest growing with a CAGR of approximately 15.38%.
-
By End-User Vertical, the Transportation & Logistics segment dominated the Commercial Vehicle Telematics Market with approximately 39.63% share in 2025, while the Construction & Mining segment is the fastest growing with a CAGR of approximately 16.19%.
By Provider Type, OEM dominates and Aftermarket grows fastest
The OEM installed telematics platform continues to be the largest provider segment in the Commercial Vehicle Telematics Market, based on the increasing trend among truck and vehicle manufacturers to install telematics hardware at the time of manufacturing. The OEM-installed platforms have better integration with the vehicle system and thus provide better engine diagnostic data compared to after-market solutions, besides being easier to service and warranty.
The aftermarket telematics segment is expected to be the fastest growing one, due to the need to add connectivity and compliance features to existing fleets, rather than relying on natural fleet renewal process. After-market telematics are based on platforms which can easily integrate with different vehicle types and years. Thus, this segment will become popular among small and medium sized fleets.
By Vehicle Class, Light Commercial Vehicles dominates and Heavy & Medium Trucks grows fastest
Light Commercial Vehicles remain the dominant vehicle class segment within the Commercial Vehicle Telematics Market, reflecting the sheer scale of global light-duty delivery and service fleets operating across e-commerce, utilities, and field service industries. This segment benefits from lower device price points and quicker installation relative to heavy-duty applications, supporting rapid, high-volume telematics adoption across large delivery and service vehicle fleets.
Heavy & Medium Trucks are emerging as the fastest-growing vehicle class segment, driven by stringent regulatory compliance requirements around driver hours-of-service, weight monitoring, and emissions tracking that apply specifically to heavy-duty commercial vehicles. This segment focuses on higher-value telematics packages incorporating multiple cameras, advanced driver-assistance sensors, and 5G connectivity gateways, positioning heavy and medium trucks to capture disproportionate revenue growth despite their smaller unit volume relative to light commercial vehicles.
By Communication Technology, Cellular dominates and Hybrid Architectures grow fastest
Cellular connectivity is still the leading technology segment in the Commercial Vehicle Telematics Market owing to wide spread coverage of 4G LTE networks, declining cost of modules, and affordable pricing of data plans. This segment thrives in an ecosystem characterized by an established and proven technological base that still manages to provide high-quality performance throughout the entire route of operations for commercial vehicles.
The hybrid connectivity solution involving both satellite and Wi-Fi technologies is the fastest growing communication technology segment in the market owing to the desire of fleet operators to be able to track their vehicles at all times through remote operating regions where there is poor cellular network coverage. This segment thrives on seamless network switching technology that ensures uninterrupted data flow despite changes in network coverage zones.
By End-User Vertical, Transportation & Logistics dominates and Construction & Mining grows fastest
Transportation & Logistics continues to be the leading end user vertical in the Commercial Vehicle Telematics market due to the high mileage operation nature of this industry, along with tough competition where fuel and labor expenses have to be minimized. This vertical utilizes the benefits offered by telematics systems, such as reduction of fuel waste through efficiency optimization and minimizing idle times, which ensure ROI of these systems, thus fostering their adoption on a wide scale.
Construction & Mining is the fastest-growing end user vertical in the Commercial Vehicle Telematics market since operators in this industry are interested in monitoring asset usage, asset security, and compliance with regulations in their geographically diverse sites. Rugged telematics devices designed for off-road operations will be particularly important in this segment in order to monitor asset usage and optimize it.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.50% |
|
Asia Pacific |
China |
48.60% |
|
Europe |
Germany |
24.70% |
|
Latin America |
Brazil |
46.90% |
|
Middle East & Africa |
United Arab Emirates |
27.40% |
North America Commercial Vehicle Telematics Market Insights
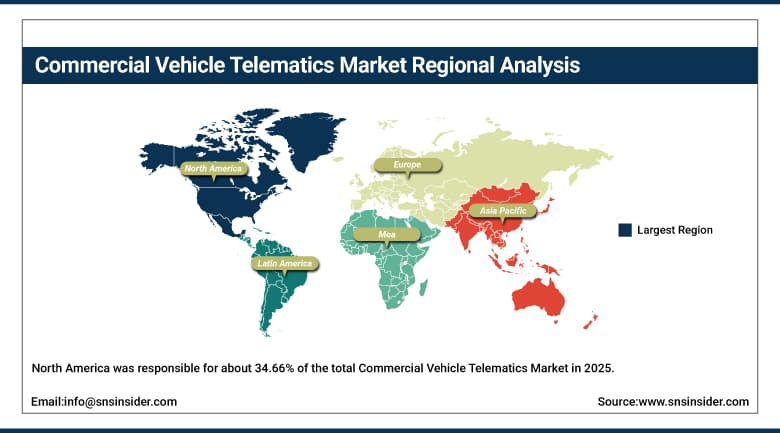
North America was responsible for about 34.66% of the total Commercial Vehicle Telematics Market in 2025 due to North America's significant commercial trucking & logistics, strong regulatory environment for electronic logging devices, and presence of leading commercial vehicle telematics platforms providers. The U.S. represents the major share of the regional demand due to its extensive commercial vehicles and the fact that it is the location of telematics firms pushing platform development and industry consolidation.
Canada and Mexico represent the additional regional demand volume backed by cross border logistics operations as part of the regional supply chain integration. The ongoing hours-of-service compliance enforcement and adoption of artificial intelligence based video safety technology strengthen the leadership of North America as the dominant regional market for commercial vehicle telematics.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Commercial Vehicle Telematics Market Insights
Asia Pacific region is expected to witness a CAGR of around 15.78% across the Commercial Vehicle Telematics Market owing to the fast growth of domestic e-commerce and logistics, along with an increase in the adoption of IoT and 5G technologies. China constitutes the largest individual contributor in this region, due to its large commercial vehicle fleet and fast-growing logistics and freight transportation segment.
The Indian subcontinent and Southeast Asian countries constitute significant contributors to growth in the region on account of increasing e-commerce infrastructure and growing government interest in vehicle tracking regulations in commercial vehicle fleets. The presence of mature automotive electronics manufacturing industries in Japan and South Korea is an important driver for the hardware supply chain in Asia Pacific, which makes the region the fastest-growing market globally for commercial vehicle telematics.
Europe Commercial Vehicle Telematics Market Insights
Europe represents a significant regional market for commercial vehicle telematics, anchored by Germany's large logistics and freight transportation sector and its concentration of major truck manufacturers integrating factory-fitted telematics hardware. Germany's share within the European market reflects both its outsized share of regional commercial vehicle production and its role as a logistics hub for broader European freight movement.
France and the United Kingdom contribute additional regional demand, supported by established logistics and construction sectors. Continued European Union regulatory focus on driver working-time compliance and vehicle emissions monitoring supports steady regional demand for telematics platforms capable of automating compliance reporting.
MEA & Latin America Commercial Vehicle Telematics Market Insights
The Latin American Commercial Vehicles Telematics Market is dominated by Brazil owing to its substantial commercial trucking industry as well as its status as a regional logistics center. The continued modernization of fleet management processes along with increasing logistics demand from the rise in e-commerce contribute to the sustained growth of the regional market.
The Middle East & Africa Region still contributes less to global demand but has growth limited to GCC countries like the United Arab Emirates where logistics infrastructure expansion and large-scale construction are gradually driving up the adoption of telematics. South Africa continues to lead telematics demand in the African region due to its relatively more developed commercial trucking and logistics industry.
Market Dynamics:
Growth Drivers: Fleet Cost Pressure and Regulatory Compliance Requirements
Intensifying competitive pressure across freight and logistics markets represents a primary growth driver for the Commercial Vehicle Telematics Market, as fleet operators increasingly rely on real-time vehicle data to reduce fuel consumption, minimize idle time, and optimize route efficiency in order to protect thin operating margins. This dynamic is reinforced by continued regulatory enforcement of hours-of-service compliance, vehicle weight monitoring, and emissions tracking requirements, which have made telematics adoption effectively mandatory for many commercial fleet operators.
Rapid growth in e-commerce and last-mile delivery volumes provides an additional significant source of demand, as logistics operators require real-time visibility into vehicle location and delivery performance across increasingly complex distribution networks. Growing integration of AI-powered video telematics for driver safety scoring further supports market growth as fleet operators seek to reduce accident-related costs and insurance premiums.
Restraints: High Implementation Costs and Data Privacy Concerns
The high initial costs involved in installing the hardware, integrating the software, and providing training to the personnel constitute a major restraint that will impact the Commercial Vehicle Telematics Market, especially when small and midsize operators assess the viability of implementing a full telematics solution from the cost-benefit perspective. This challenge is exacerbated by the difficulties encountered when implementing telematics in legacy fleet management systems or even older vehicles, which could result in project delays and higher than expected costs.
Privacy issues among drivers and even labor unions pose yet another challenge and act as a restraint to the growth of the market as some fleet managers encounter internal resistance to implement more sophisticated tracking capabilities of telematics solutions.
Opportunities: AI-Powered Analytics and Emerging Market Expansion
Future development and enhancement of the AI-based video analytics and predictive maintenance services will create a significant opportunity for the Commercial Vehicle Telematics Market. These services represent advanced offerings that will enable companies to offer solutions beyond basic GPS tracking with the ability to collect and analyze comprehensive data on the fleets, allowing them to earn high revenues from such services. Companies which will be able to showcase benefits of using their services in terms of improved safety and efficiency of operation will have a high chance of success in the market.
Fast growth of the logistics sector in Asia Pacific and Latin America presents an opportunity for telematics providers to grow in markets where fleet management practices are less advanced. With the development of logistics infrastructure in these regions, telematics service providers will be able to obtain an outsized share of the growing demand.
Recent Developments:
-
In April 2024, Powerfleet completed its business combination with MiX Telematics, a leading global provider of fleet and mobile asset management solutions serving over one million subscribers across more than 120 countries, expanding Powerfleet's international customer base and platform capabilities.
-
In October 2025, Samsara entered into a strategic partnership with Allianz UK to make advanced risk management technology more accessible to a broader range of commercial fleet operators insured by Allianz in the United Kingdom, expanding access to Samsara's connected safety and telematics platform.
Commercial Vehicle Telematics Market Key Players:
-
Geotab Inc.
-
Verizon Connect
-
Trimble Inc.
-
Samsara Inc.
-
Powerfleet, Inc.
-
Omnitracs LLC
-
Zonar Systems, Inc.
-
MiX Telematics
-
Fleet Complete
-
Inseego Corporation
-
Octo Group S.p.A.
-
Microlise Group Limited
-
Harman International Industries
-
Webfleet Solutions B.V.
-
Robert Bosch GmbH
-
Continental AG
-
Teletrac Navman
-
Omnicomm Group
-
ZF Friedrichshafen AG
-
Motive Technologies, Inc.
Commercial Vehicle Telematics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 79.00 Billion |
| Market Size by 2035 | USD 302.16 Billion |
| CAGR | CAGR of 14.35% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Provider Type (OEM and Aftermarket) • by Vehicle Class (Light Commercial Vehicles and Heavy & Medium Trucks) • by Communication Technology (Cellular and Hybrid Architectures) • by End-User Vertical (Transportation & Logistics, Construction & Mining, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Geotab Inc., Verizon Connect, Trimble Inc.,Samsara Inc., Powerfleet, Inc. , Omnitracs LLC, Zonar Systems, Inc., MiX Telematics, Fleet Complete, Inseego Corporation, Octo Group S.p.A., Microlise Group Limited, Harman International Industries, Webfleet Solutions B.V., Robert Bosch GmbH, Continental AG, Teletrac Navman, Omnicomm Group, ZF Friedrichshafen AG, Motive Technologies, Inc. |
Frequently Asked Questions
Leading companies in the Commercial Vehicle Telematics Market include Geotab, Verizon Connect, Trimble, Samsara, and Powerfleet, among others.
Key opportunities include continued advancement of AI-powered video analytics and predictive maintenance capabilities, and rapid expansion of e-commerce and logistics infrastructure across emerging Asia Pacific and Latin American markets.
Intensifying competitive pressure across freight and logistics markets, combined with continued regulatory enforcement of hours-of-service compliance and emissions tracking requirements, is the major factor driving market growth.
The Light Commercial Vehicles segment dominated the Commercial Vehicle Telematics Market with approximately 48.89% share in 2025.
North America dominated the Commercial Vehicle Telematics Market in 2025 with approximately 34.66% share, driven by the region's large commercial trucking and logistics sector, led by the United States.
