
Comprehensive Metabolic Panel Testing Market Report Scope & Overview:
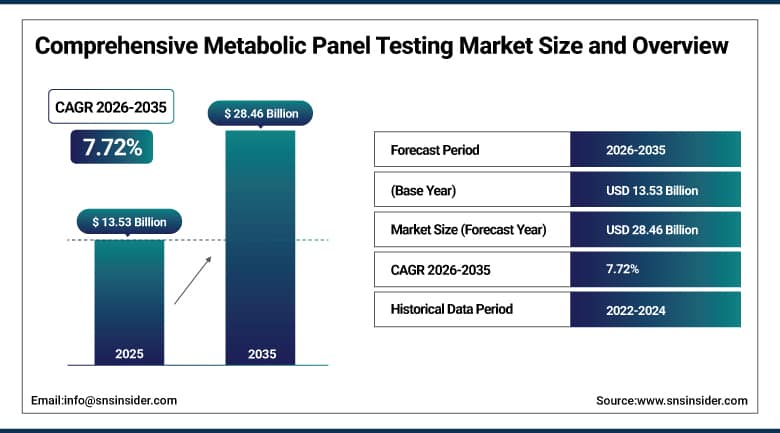
The Comprehensive Metabolic Panel Testing Market was valued at USD 13.53 Billion in 2025 and is expected to reach USD 28.46 Billion by 2035, growing at a CAGR of 7.72% from 2026-2035.
The Comprehensive Metabolic Panel Testing Market is growing as routine blood chemistry becomes central to preventive care and chronic disease management. The panel measures glucose, electrolytes, kidney markers, and liver enzymes from a single sample. Clinicians order it at annual checkups, hospital admissions, and medication monitoring visits. Automation allows laboratories to run large volumes at low unit cost. Point of care analyzers are bringing the panel to clinics and emergency settings. Rising diabetes and kidney disease prevalence keeps ordering volumes high. Capillary sampling and home collection are widening access further. Integrated health networks are also improving test utilization across care settings.
⮞In April 2025, the International Diabetes Federation reported in its Diabetes Atlas that an estimated 252 million adults with diabetes remain undiagnosed. Large undiagnosed populations sustain demand for routine glucose and metabolic panel screening.
To Get More Information On Comprehensive Metabolic Panel Testing Market - Request Free Sample Report
Comprehensive Metabolic Panel Testing Market Trends:
-
Shift of routine panels toward point of care analyzers and capillary sampling
-
Higher throughput chemistry automation in core and hospital laboratories
-
Growth of at home sample collection and direct to consumer ordering
-
Integration of laboratory results with electronic records and decision support tools
-
Expansion of public screening programs for diabetes and kidney disease
U.S. Comprehensive Metabolic Panel Testing Market Outlook:
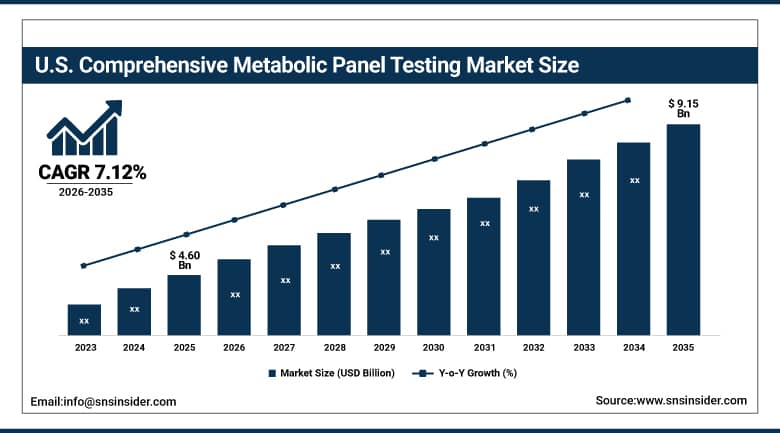
The U.S. Comprehensive Metabolic Panel Testing Market was valued at USD 4.60 Billion in 2025 and is expected to reach USD 9.15 Billion by 2035, growing at a CAGR of 7.12% from 2026-2035.
The U.S. Comprehensive Metabolic Panel Testing Market is supported by one of the highest rates of routine laboratory ordering among major economies. Physicians include the panel in annual physicals, pre-operative assessments, and chronic disease visits. Reference laboratories, hospital systems, and independent networks compete on turnaround and test access. Large insured populations and electronic ordering keep volumes predictable. Medicare reimbursement policy influences laboratory economics and investment plans. Point of care chemistry is expanding in urgent care and primary care clinics. Payers favor screening to detect kidney disease and diabetes early. These dynamics make the United States the reference market for panel volumes and technology adoption.
⮞As of March 2026, the Centers for Disease Control and Prevention estimates that about 14% of U.S. adults have chronic kidney disease. Creatinine and urea measures in the panel remain first line tools for detecting it.
Comprehensive Metabolic Panel Testing Market Segment Analysis:
-
By Test Type, the Kidney Function Tests segment dominated the Comprehensive Metabolic Panel Testing Market with approximately 31.12% share in 2025, while the Glucose Tests segment is the fastest growing with a CAGR of approximately 10.06%.
-
By Disease, the Kidney Diseases segment dominated the Comprehensive Metabolic Panel Testing Market with approximately 34.44% share in 2025, while the Diabetes segment is the fastest growing with a CAGR of approximately 8.74%.
-
By End User, the Laboratories segment dominated the Comprehensive Metabolic Panel Testing Market with approximately 62.05% share in 2025, while the Point of Care Centers segment is the fastest growing with a CAGR of approximately 9.77%.
-
By Panel Type, the Basic Panel segment dominated the Comprehensive Metabolic Panel Testing Market with approximately 58.50% share in 2025, and is also the fastest growing with a CAGR of approximately 9.02%.
By Test Type, Kidney Function Tests Dominates the Comprehensive Metabolic Panel Testing Market and Glucose Tests Grows Fastest
Kidney function markers anchor panel ordering because creatinine and urea results guide drug dosing, contrast imaging decisions, and chronic disease staging. Clinicians repeat these measures often in patients with diabetes, hypertension, and heart disease, which builds recurring volume. Laboratories value the assays because they run reliably on high throughput chemistry platforms and allow estimated filtration rate reporting without extra sample. Guidelines that call for regular monitoring of at risk adults keep these tests embedded in primary care workflows. Reagent suppliers compete on precision and standardization to support consistent results across sites.
Testing for glucose is increasing due to the expansion of prediabetes and diabetes screening. Fasting tests are still part and parcel of regular checkups in preventive medicine, and employers incorporate them in their wellness programs. Capillary blood samples taken with point of care analyzers yield results in less than a minute, thereby facilitating decision-making on the spot. Increased incorporation of panels that measure glucose in combination with kidney and liver functions increases demand for orders. Improvement in enzymatic procedures and interference management is making manufacturers develop tests suitable for use in decentralized sites with few trained laboratory technicians.
⮞In March 2026, Roche received U.S. FDA clearance for its cobas c 703 analyzer, which runs up to 2,000 tests per hour. The platform expands chemistry throughput for laboratories that process large panel volumes.
By Disease, Kidney Diseases Dominates the Comprehensive Metabolic Panel Testing Market and Diabetes Grows Fastest
Kidney disease is the leading indication because the panel is the main tool for detecting and tracking declining filtration. Many patients remain unaware of reduced kidney function, so opportunistic testing during routine visits identifies cases that would otherwise progress. Nephrology referral pathways, dialysis planning, and medication safety reviews all rely on repeated panel results. Health authorities are strengthening policy attention on kidney health, which supports screening protocols in primary care and diabetes clinics. Laboratories gain steady volumes from this monitoring work throughout the year. Primary care teams also use panel trends to adjust prescriptions for blood pressure and diabetes control.
Diabetes is the faster growing indication as prevalence rises in Asia, the Middle East, and Latin America. Panels help clinicians track glucose, kidney function, and liver enzymes in patients on combination therapy. New classes of glucose lowering drugs require baseline and follow up metabolic monitoring, which increases ordering. Public screening campaigns and workplace programs expand the tested population. Integrated care models link primary care, laboratories, and digital tools so that abnormal results trigger follow up. These patterns lift volumes beyond what population growth alone would explain. Clinicians use the results to decide on dose changes for therapies that affect kidney function.
⮞In May 2025, the 78th World Health Assembly adopted the first global resolution on kidney health. The resolution raises policy priority for early detection programs that depend on routine metabolic testing.
By End User, Laboratories Dominates the Comprehensive Metabolic Panel Testing Market and Point of Care Centers Grows Fastest
Centralized labs make up most of the tests due to the economies of scale associated with chemistries analyzers’ costs per test. The hospital labs take care of in-patients and emergency room patients, whereas independent networks handle outpatients' requisitions made by physicians and employers. Automation and track systems minimize manual handling of samples, and results are ready within a few hours. Centralization in large networks provides negotiating power in purchasing from reagents suppliers. Labs can also report results automatically as critical values and integrate into electronic medical record systems, making them the preferred way of conducting routine test panels. Reference labs conduct send-out tests in small hospitals as well.
Clinics, urgent care centers, and pharmacies are adopting compact analyzers that run panel tests from a small blood sample. Results within minutes allow a clinician to adjust treatment during the same visit. Rural areas and decentralized health programs use these devices where reference laboratories are far away. Vendors are improving cartridge stability, calibration, and connectivity, which narrows the gap with central laboratory performance. Regulatory waivers for simple devices support wider placement, and reimbursement for near patient testing is improving in several markets, which strengthens the business case for adoption.
⮞In July 2026, Quest Diagnostics reported that requisition volume rose 13.1% in the second quarter of 2026. Growth in routine ordering confirms the central role of reference laboratories in panel testing.
By Panel Type, Basic Panel Dominates the Comprehensive Metabolic Panel Testing Market and Also Grows Fastest
Basic panels hold the leading position because they cover the electrolyte, glucose, and kidney markers that clinicians need for most acute and routine decisions. Hospitals order them frequently for admissions, emergency care, and pre-procedure screening, where speed and low cost matter. Compact analyzers and point of care devices run the core analytes efficiently. Payers reimburse the tests widely, and clinical pathways list them as standard first line investigations. This breadth keeps order counts high across care settings and across patient age groups. Standardized reporting formats make results easy to compare over time.
The same segment is also expanding fastest as decentralized testing grows. Clinics and emergency departments favor the smaller analyte set because it can be run quickly on portable platforms and provides actionable results. Expanded panels that add liver enzymes and proteins remain important for comprehensive checkups but require larger instruments in most settings. Growth in basic ordering is further supported by routine monitoring of patients on kidney active drugs. Manufacturers are also adding capillary sample claims to extend reach beyond venous draws. Community health programs also use compact panels to screen large groups at low cost.
⮞In March 2025, Beckman Coulter received FDA 510(k) clearance for its DxC 500i clinical analyzer, which runs 800 chemistry tests per hour. The system gives mid volume laboratories a compact platform for routine panel work.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
90.64% |
|
Europe |
Germany |
22.87% |
|
Asia Pacific |
China |
35.42% |
|
Latin America |
Brazil |
48.13% |
|
Middle East & Africa |
Saudi Arabia |
27.69% |
North America Comprehensive Metabolic Panel Testing Market Insights
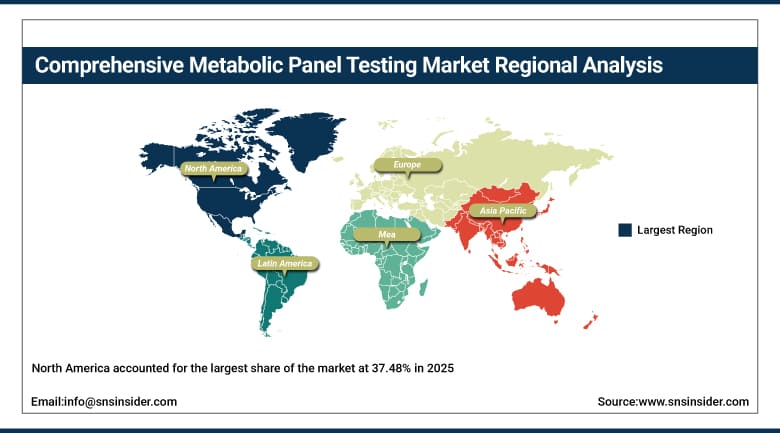
North America accounted for the largest share of the market at 37.48% in 2025, supported by high routine testing rates, large reference laboratory networks, and broad insurance coverage. The United States drives most regional volume, and Canada adds steady demand through provincial laboratory systems. Annual physicals, chronic disease management programs, and pre-surgical screening keep panel orders high. Hospital systems are consolidating laboratory operations to improve efficiency, and this strengthens demand for high throughput chemistry platforms. Consumer access to direct ordering is also widening the tested population. Laboratory groups continue to invest in new facilities to serve outpatient growth.
⮞Regulatory and reimbursement policy shape investment decisions. Laboratory developed tests remain under the oversight of laboratory regulators rather than device regulators, which preserves flexibility for in house chemistry assays. Medicare payment schedules influence margins for outpatient testing and affect purchasing of new analyzers. Home collection and at home kits are gaining traction, and providers are adding mobile phlebotomy services. Competition among suppliers centers on throughput, reagent quality, and middleware that links analyzers to electronic records. Vendors also offer service agreements and reagent rental models that lower upfront costs for mid sized laboratories.
In September 2025, the U.S. Food and Drug Administration issued a ministerial rule that implements a court vacatur of its laboratory developed test rule. The action leaves laboratory run chemistry tests outside device oversight.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Comprehensive Metabolic Panel Testing Market Insights
Europe is fueled by national health systems, which make use of routine blood chemistry analysis as part of primary care and hospital workflow. The major part of regional demand comes from Germany, the UK, France, Italy, and Spain. There are centralized laboratory networks in several countries using the large analyzer platforms to provide low cost analysis while private groups continue their expansion of outpatient testing. Aging population drives the need for kidney, liver and metabolic disease monitoring, thus creating stable growth in orders. Cross-border laboratory organizations utilize common platforms and contracts on standardized reagents for better efficiency between countries. In public tenders, it pays off to offer stable service and reagent availability.
Product strategy is influenced by regulations. In vitro diagnostic regulation increases the documentation and conformity assessment demands for the chemistry reagents and analyzers, while transition extensions allow more time for manufacturers to comply. The reimbursement in different countries makes suppliers adjust their menus and service models. Community diagnostics projects in the UK and elsewhere add testing capacity outside the hospitals. The sustainability initiatives force laboratories to reduce reagent wastage and use energy-efficient analyzers.
⮞In July 2024, the European Union adopted Regulation (EU) 2024/1860, which extends transition periods under the in vitro diagnostic regulation until 2027, 2028, and 2029 depending on device class. The extension keeps established chemistry reagents on the market while manufacturers complete conformity assessment.
Asia Pacific Comprehensive Metabolic Panel Testing Market Insights
The Asia Pacific region will show the highest growth rate, with an anticipated CAGR of 9.61%, between 2026 and 2035 due to China, India, Japan, and South Korea. Increased hospital capacity, high incidence of diabetes, and increasing demand for health checkups from the middle classes fuel ordering. China is focusing on upgrading laboratory capacities and manufacturing analyzers locally, whereas India is expanding its organized diagnostic chain as well as free diagnostics programs for the masses. The prevention culture for checkups in Japan and South Korea ensures mature and frequent testing. Affordable chemistry systems are being introduced by local manufacturers.
Networking is one of the key features of the region. Diagnostic chains are expanding their capacities through collection centers as well as home sampling facilities, and booking platforms are gaining popularity in urban centers. Public sector initiatives of several countries ensure funding for basic diagnostics at the primary health care center level such as electrolytes, kidney markers, and liver enzymes. Reagent supplies are localized as manufacturers are building regional manufacturing units for reagents. Cost per test is reduced through these efforts, and routine panels have been made available to semiurban and rural populations which were under-serviced.
⮞In July 2026, Thyrocare reported that it processed about 55.2 million tests in the first quarter of fiscal 2027. Volumes of this scale show how organized laboratory chains are absorbing rising routine testing demand in India.
MEA & Latin America Comprehensive Metabolic Panel Testing Market Insights
Latin America is led by Brazil and Mexico, where large public systems and private laboratory groups drive routine panel volume. Rising diabetes and hypertension prevalence supports screening and monitoring programs. Mexico is treated as part of this region in market estimates, and its social security institutes run large detection campaigns. Brazil has dense private diagnostic chains that centralize chemistry on high throughput platforms. Currency volatility and import dependence raise reagent costs, yet public procurement and expanding private insurance continue to add test volumes. Argentina, Chile, and Colombia contribute through hospital upgrades.
⮞In January 2026, Brazil's Ministry of Health reported through its Vigitel survey that diabetes prevalence among adults reached 12.9% in 2024. Higher prevalence expands the population that needs regular glucose and kidney monitoring.
The Middle East and Africa region is expanding through government health programs and private laboratory investment, particularly in Saudi Arabia, the United Arab Emirates, and South Africa. National transformation programs fund preventive screening and expand primary care capacity. A high diabetes and kidney disease burden in Gulf populations supports demand for routine panels. South Africa runs a large national public laboratory service with centralized chemistry. Limited laboratory infrastructure in parts of sub-Saharan Africa constrains access, which creates opportunities for point of care devices and mobile testing. Private hospital groups are adding in house chemistry capacity to shorten turnaround.
⮞In January 2026, the Saudi Ministry of Health highlighted the Taakad screening program under Vision 2030, which screens for diabetes, lipid disorders, and other conditions across Riyadh health clusters. Population screening of this kind raises routine chemistry ordering.
Market Dynamics:
Growth Drivers: Rising Chronic Disease Burden and Preventive Screening Drive Growth in the Comprehensive Metabolic Panel Testing Market
Diabetes, kidney disease, and liver conditions require repeated laboratory monitoring, and each patient generates several panel orders each year. Aging populations enlarge this base of patients and add medication related testing because many drugs affect kidney and liver function. Primary care guidelines place the panel in routine checkups, which makes it one of the most frequently ordered blood tests. Employers and insurers promote screening to reduce long term cost. Hospitals also include the panel in admission and pre-procedure protocols, which anchors demand in acute care. Rising awareness of metabolic health among younger adults adds further tested volume.
Technology gains support this demand. High throughput analyzers lower cost per result, while integrated software helps clinicians interpret abnormal values quickly. Capillary sampling and home collection reduce barriers to testing for patients who avoid clinic visits. Expanding diagnostic networks in emerging economies bring routine panels to new populations. Automation helps laboratories manage workforce shortages without sacrificing turnaround time. Digital portals that deliver results directly to patients encourage repeat testing, and wellness programs add scheduled testing cycles that lift ordering frequency over the forecast period. Telemedicine visits increasingly trigger laboratory orders after remote consultations.
⮞As of 31 March 2026, Dr Lal PathLabs operated 7,727 patient service centers across India. Dense collection networks of this kind bring routine panels within reach of more patients.
Restraints: Reimbursement Pressure and Compliance Costs Restrain Growth in the Comprehensive Metabolic Panel Testing Market
The payment pressure is still the most evident factor. Payers, both public and private, have decreased or threatened to decrease payments for routine lab tests, including impacts on the margins of volume-intensive testing like metabolic profiles. Laboratories deal with such challenges by consolidation, lifecycle extension, and delays in purchasing new instruments. Instability in reagents prices is another issue because enzyme-based assays require specific reagents. Small laboratories cannot sustain such cost fluctuations and either leave the market or consolidate. Competitiveness of reagent vendors is another challenge since it decreases profit margins for manufacturers. Renewal of payer contracts usually involves volume tiers that decrease per-test income.
Regulations increase the costs of doing business. Quality system for laboratory operations, instrumentation validation, and compliance testing need skilled personnel and documentation. Lack of clinical chemists and technologists is a problem for capacity expansion in many markets. Inability of laboratory information systems to exchange the data with electronic health records increases the burden of automation. Concerns about test utilization also make some payers impose restrictions on order repetition of panel tests for low-risk patients. Cybersecurity and data protection regulations are additional burdens.
⮞In February 2026, the American Society for Clinical Pathology reported that a law signed on 3 February 2026 blocks scheduled Medicare payment cuts of up to 15% for laboratory services for the remainder of 2026. The episode shows how payment policy can quickly change laboratory economics.
Opportunities: Point of Care Testing and Decentralized Sample Collection Create Opportunities in the Comprehensive Metabolic Panel Testing Market
Point of care platforms that deliver a full panel from a small sample offer a large opportunity in clinics, pharmacies, emergency departments, and remote health posts. Faster results shorten visit length and allow treatment decisions during the same encounter. Manufacturers that secure waived status for their devices expand the addressable customer base to settings without trained laboratory staff. Connectivity to electronic records and cloud dashboards adds value for chronic disease programs. Reimbursement alignment for near patient testing in several markets is also improving the business case. Pharmacy based chronic disease clinics are an emerging customer for these systems.
Decentralized sample collection opens another path. Capillary blood draws reduce the need for venipuncture and enable home or workplace sampling. Laboratory vendors are validating central analyzers for capillary samples so that results stay consistent with venous testing. Mobile phlebotomy, retail collection points, and direct to consumer ordering are creating new demand channels. Artificial intelligence tools that flag patterns across panel results can add clinical value and support test utilization programs. Providers that combine capillary capability, digital ordering, and reliable logistics can capture growth from patients that traditional networks reach poorly.
⮞In July 2026, Siemens Healthineers announced 24 capillary blood assay claims with CE mark that cover key assays used in the panel. The claims let laboratories offer finger prick sampling on existing core laboratory systems.
Recent Developments:
-
In August 2025, QuidelOrtho launched a certified analyzer program for its VITROS XT 7600 and VITROS XT 5600 integrated systems, designed to support community laboratories that run general chemistry.
-
In May 2026, Mayo Clinic Laboratories announced the opening of a new laboratory in Southaven as part of a wider expansion of its laboratory footprint, with no change to how clients place orders.
-
In July 2026, Eurofins reported in its first half results that it had consolidated SYNLAB Spain into its clinical diagnostics business and divested Dutch clinical entities. The portfolio changes concentrate routine chemistry volumes in markets where the group holds dense laboratory networks.
Comprehensive Metabolic Panel Testing Market Key Players are:
-
Roche Diagnostics
-
Abbott Laboratories
-
Siemens Healthineers
-
Beckman Coulter
-
QuidelOrtho
-
Mindray
-
Randox Laboratories
-
Quest Diagnostics
-
Labcorp
-
ARUP Laboratories
-
Mayo Clinic Laboratories
-
Sonic Healthcare
-
Eurofins Scientific
-
Dr Lal PathLabs
-
Thyrocare
Comprehensive Metabolic Panel Testing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.53 Billion |
| Market Size by 2035 | USD 28.46 Billion |
| CAGR | CAGR of 7.72% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Test Type (Kidney Function Tests, Glucose Tests, Liver Function Tests, and Electrolyte Tests) • By Disease (Kidney Diseases, Diabetes, Liver Diseases, and Others) • By End User (Laboratories, Point of Care Centers, and Others) • By Panel Type (Basic Panel and Expanded Panel) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, QuidelOrtho, Mindray, Randox Laboratories, Quest Diagnostics, Labcorp, ARUP Laboratories, Mayo Clinic Laboratories, Sonic Healthcare, Eurofins Scientific, Dr Lal PathLabs, Thyrocare |

Frequently Asked Questions
Key players in the market include Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, Quest Diagnostics, and Labcorp, among others.
Key opportunities include point of care testing platforms that deliver a full panel from a small sample, and decentralized sample collection through capillary draws, home sampling, and mobile phlebotomy.
The rising burden of diabetes, kidney disease, and liver conditions is the major growth factor. These conditions require repeated laboratory monitoring and place the panel in routine checkups and hospital protocols.
The Kidney Function Tests segment dominated the market in 2025 with approximately 31.12% share, as creatinine and urea results guide drug dosing, imaging decisions, and chronic disease staging.
North America dominated the market in 2025 with approximately 37.48% share, supported by high routine testing rates, large reference laboratory networks, and broad insurance coverage.
