
Cone Beam Computed Tomography Market Report Scope & Overview:
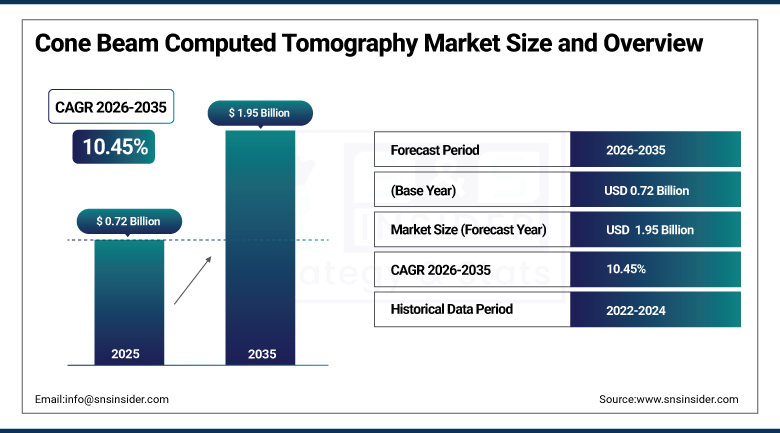
The Cone Beam Computed Tomography Market was valued at USD 0.72 Billion in 2025 and is expected to reach USD 1.95 Billion by 2035, growing at a CAGR of 10.45% from 2026-2035.
Cone beam computed tomography has transformed dental and medical imaging by delivering highly detailed, three-dimensional visualisations at meaningfully lower radiation exposure than conventional computed tomography scanners. The technology is now widely used in dental implantology, orthodontics, endodontics, and maxillofacial surgery, alongside a growing footprint in ENT and select orthopedic applications, enabling practitioners to plan and execute interventions with far greater precision than earlier imaging modalities allowed. Rising global awareness of oral health, an ageing population increasingly requiring implant and reconstructive procedures, and continued demand for minimally invasive treatment planning continue to widen the addressable patient base. Sustained investment in artificial intelligence-assisted image reconstruction, alongside expanding adoption among small and mid-sized dental practices, continues to reinforce this market's position as a durable, technology-led segment of the broader diagnostic imaging industry.
In May 2025, GE HealthCare launched CleaRecon DL, a deep-learning powered technology designed to enhance the quality of cone beam computed tomography images. The company said the tool improves diagnostic confidence by producing clearer, more consistent image reconstructions across a wider range of patient body types and imaging conditions.
To Get more information On Cone Beam Computed Tomography Market - Request Free Sample Report
Cone Beam Computed Tomography Market Trends
-
Rising integration of deep-learning image reconstruction improving diagnostic clarity across patient types.
-
Growing adoption of compact, cost-effective CBCT systems among small and mid-sized dental practices.
-
Expanding use of CBCT technology beyond dental applications into ENT and orthopedic imaging.
-
Increasing manufacturer investment in lower-radiation-dose systems supporting broader patient safety standards.
-
Rising demand for supine patient positioning offering improved comfort during extended imaging procedures.
-
Growing private equity and strategic investment activity supporting continued CBCT product innovation.
U.S. Cone Beam Computed Tomography Market Overview
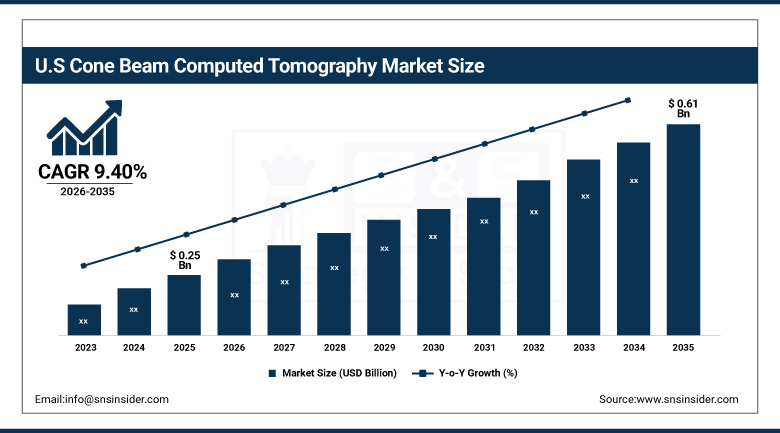
The U.S. Cone Beam Computed Tomography Market was valued at USD 0.25 Billion in 2025 and is expected to reach USD 0.61 Billion by 2035, growing at a CAGR of 9.40% from 2026-2035.
The domestic market will benefit from the already existing stable foundation of privately owned dental centers and implant-specific clinics that have gradually been acquiring smaller versions of CBCT devices for better and quicker diagnostic testing. The ongoing process of regulation of new-generation products in conjunction with rising knowledge about the benefits of the CBCT method over conventional two-dimensional radiography ensures steady domestic demand for CBCT equipment.
In September 2024, Carestream Dental secured a USD 525 million investment from General Atlantic Credit's Atlantic Park fund to fuel continued CBCT innovation and support the launch of an Oral Healthcare Innovation Hub. The investment is expected to accelerate product development across the company's imaging portfolio.
Cone Beam Computed Tomography Market Segment Analysis
-
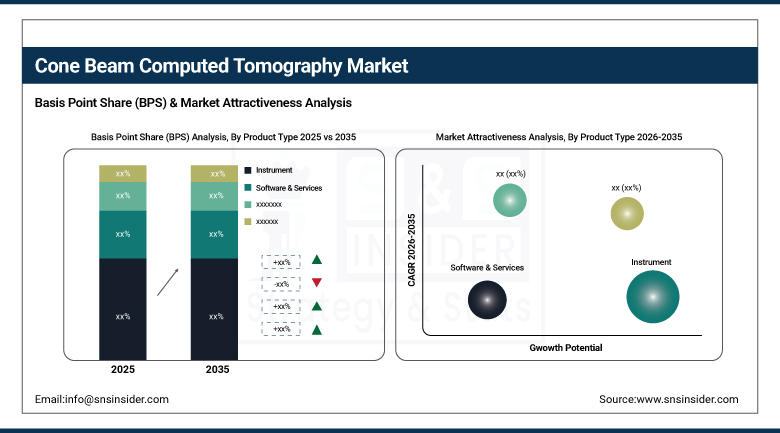
By Product Type, the Instrument segment dominated the market with a 76.40% share in 2025, while the Software & Services segment is the fastest growing with a CAGR of 13.60% during 2026-2035.
-
By Application, the Dental Imaging segment dominated the market with a 65.80% share in 2025, while the ENT Imaging segment is the fastest growing with a CAGR of 12.40% during 2026-2035.
-
By Patient Position, the Supine segment dominated the market with a 48.60% share in 2025, and is also the fastest growing with a CAGR of 11.80% during 2026-2035.
-
By End-User, the Dental Clinics segment dominated the market with a 44.90% share in 2025, while the Hospitals segment is the fastest growing with a CAGR of 12.20% during 2026-2035.
By Product Type, Instrument Dominates the Market and Software & Services Grows Fastest
Instrument systems dominated the market in 2025. The scanner itself remains the core capital investment for any practice adopting cone beam technology, and this fundamental hardware requirement continues to anchor instrument systems as the largest product category, particularly as practices upgrade from two-dimensional imaging equipment for the first time. Replacement and upgrade cycles across an ageing installed base continue to sustain steady instrument revenue.
Software & Services is projected to be the fastest-growing product category over the forecast period. Deep-learning image reconstruction tools and ongoing maintenance and calibration services continue to command a growing share of overall spending, as practices increasingly view software capability as a genuine differentiator rather than a bundled afterthought. This shift continues to pull software and services growth ahead of the broader hardware-dominated product mix.
By Application, Dental Imaging Dominates the Market and ENT Imaging Grows Fastest
Dental imaging dominated the market in 2025. Implant planning, orthodontic assessment, and endodontic diagnosis continue to represent the technology's original and still largest clinical use case, supported by growing patient demand for precise, minimally invasive treatment planning. This entrenched clinical role continues to sustain dental imaging as the clear leading application category.
ENT imaging is projected to be the fastest-growing application over the forecast period. Continued expansion of CBCT use for sinus and temporal bone evaluation continues to appeal to specialists seeking detailed three-dimensional visualisation without the higher radiation exposure conventional CT imposes, positioning this application for sustained above-market growth relative to the broader dental-dominated application mix.
By Patient Position, Supine Dominates the Market and Also Grows Fastest
Supine positioning dominated the market in 2025. The comfort and ease this position offers during imaging procedures continues to make it the preferred configuration across an expanding range of clinical settings, particularly for longer scans or patients less able to remain still in an upright position. This practical advantage continues to anchor supine positioning as the leading patient position category.
Supine positioning is also expected to grow fastest over the forecast period. Continued expansion of CBCT into hospital and orthopedic settings, where supine imaging already represents standard practice for other modalities, continues to reinforce this position's growing adoption, extending its lead over standing and seated configurations even further across the broader market.
By End-User, Dental Clinics Dominates the Market and Hospitals Grows Fastest
Dental clinics dominated the market in 2025. The sheer number of private and specialty dental practices worldwide, combined with CBCT's now well-established role in implant and orthodontic planning, continues to sustain dental clinics as the largest end-user category by a clear margin. Continued adoption among smaller, independent practices continues reinforcing this leadership position.
Hospitals are expected to be the fastest-growing end-user category over the forecast period. Continued expansion of CBCT use beyond dedicated dental applications into maxillofacial surgery, ENT, and select orthopedic procedures continues to drive hospital-based adoption, positioning this end-user category for sustained above-market growth relative to the broader dental-clinic-dominated market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
86.90% |
|
Europe |
Germany |
25.40% |
|
Asia Pacific |
China |
37.60% |
|
Latin America |
Brazil |
28.30% |
|
Middle East & Africa |
United Arab Emirates |
21.90% |
North America Cone Beam Computed Tomography Market Insights
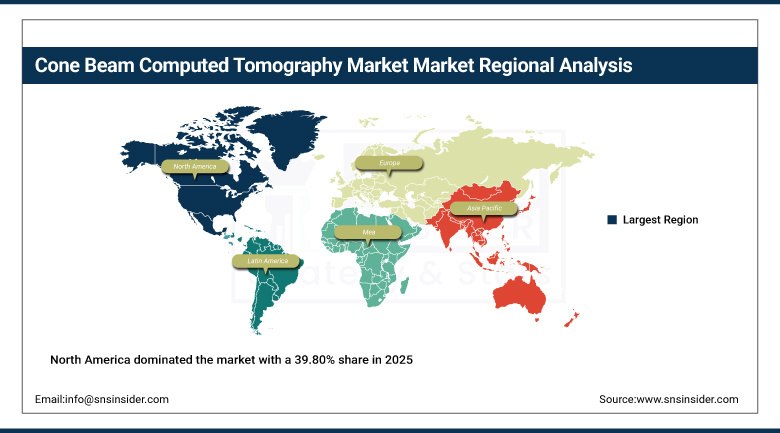
North America dominated the market with a 39.80% share in 2025. A well-established base of private dental clinics and implant specialty practices, combined with early adoption of AI-assisted image reconstruction technology, continues to anchor this leadership position. The presence of leading manufacturers headquartered within the region further reinforces sustained investment in next-generation CBCT development.
Canada contributes steady incremental demand as its own dental and medical imaging sectors continue modernising equipment. Continued domestic investment in compact, cost-effective CBCT systems, alongside sustained regulatory clearance activity for next-generation devices, is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Cone Beam Computed Tomography Market Insights
Asia-Pacific is expected to remain the fastest-growing region at a CAGR of 12.60% for 2026-2035. The presence of large patient base, increasing prevalence of dental and oral diseases, and investments in healthcare infrastructure have been driving the demand in the region. Increasing number of dental clinics in China and increasing investments in healthcare are also driving regional demand.
India, with its growing dental care industry and increasing awareness about oral hygiene, is also contributing to regional growth. Countries like Japan and South Korea provide more depth in the form of well-established medical devices industry in the region, with regional players developing miniaturized systems for smaller clinics. Thus, the region is expected to remain the fastest-growing market up to 2035.
Europe Cone Beam Computed Tomography Market Insights
Europe holds a meaningful share of the global market, supported by growing government initiatives promoting oral healthcare and advanced imaging, alongside the presence of well-established dental and medical institutions. Favourable reimbursement policies for CBCT procedures across several European countries continue to reinforce sustained regional demand.
Germany's substantial dental and medical device manufacturing base anchors regional demand, while the United Kingdom, France, and other major European markets contribute consistent demand as national health systems continue extending advanced imaging technology into routine dental and specialist practice.
MEA & Latin America Cone Beam Computed Tomography Market Insights
The Middle East & Africa market is supported by growing healthcare infrastructure spending across the United Arab Emirates and Saudi Arabia, where rising dental tourism and expanding private healthcare investment continue to lift demand for advanced imaging equipment across the region.
Latin America's market is anchored by Brazil, where a sizeable domestic dental care sector sustains steady equipment demand. Mexico contributes further incremental growth as dental clinic infrastructure continues to expand, though adoption of the most advanced AI-enabled systems across the broader region still lags more established global markets.
Market Dynamics
Growth Drivers: Rising Dental Disease Prevalence and Minimally Invasive Procedure Demand
Growing prevalence of dental and maxillofacial disorders stands as the primary growth driver, as increasing incidence of dental caries, periodontal disease, temporomandibular joint disorders, and oral cancers continues to widen the patient population requiring advanced diagnostic imaging. Improved global awareness of oral health continues to reinforce sustained demand across both established and emerging dental care markets.
Rising demand for minimally invasive procedures represents a second major driver, as CBCT's ability to deliver detailed three-dimensional visualisation at meaningfully lower radiation exposure than conventional CT continues to make it the preferred imaging choice for implant planning and surgical guidance. Continued government initiatives promoting advanced imaging access further reinforce sustained market expansion.
Restraints: High Equipment Costs and Radiation Safety Regulation
High equipment costs remain a genuine restraint, as advanced CBCT systems incorporating AI-assisted reconstruction and expanded field-of-view capability continue to command premium pricing that smaller, independent practices can struggle to justify against limited capital budgets.
Stringent radiation safety regulation presents a further restraint, as manufacturers must continue to navigate varying international dose limit standards and certification requirements, adding development cost and complexity to bringing new systems to market across multiple jurisdictions simultaneously.
Opportunities: AI-Assisted Reconstruction and Expanding Clinical Applications
The continued development of AI-supported image reconstructions provides a major advantage to manufacturers, as those that provide truly sharper, more diagnostic images for various patient body types will be able to distinguish themselves in a growing market of medical equipment.
Expanding to ENT, orthopedic, and other hospital applications is another potential area of development, as those manufacturers that can expand their CBCT from the dental specialty area to wider use will be able to tap into new medical specializations that require precise and low-dosage 3D images.
Recent Developments:
-
In July 2024, Epica International obtained 510(k) clearance for its See Factor CT3 system, broadening clinical imaging options across both dental and medical settings.
-
In 2025, CurveBeam AI and PreXion introduced specialised CBCT solutions for orthopedic and dental imaging, focusing on precise three-dimensional visualisation for specialist clinical applications.
-
In 2025, J. Morita Corporation, Fussen Group, iCRco Inc., and Idetec Medical Imaging expanded their compact and affordable CBCT system offerings, widening adoption among small and mid-sized dental practices.
-
In 2026, Vatech America and Carestream Health developed high-resolution CBCT systems with lower radiation exposure, supporting safer and more accurate imaging for dental clinics and hospitals.
Cone Beam Computed Tomography Market Key Players
-
Planmeca Group
-
Fussen Group
-
PreXion Corporation
-
iCRco Inc.
-
Idetec Medical Imaging
-
CurveBeam AI
-
J. Morita Corporation
-
GE HealthCare Technologies Inc.
-
NewTom (Cefla s.c.)
-
Owandy Radiology
-
Genoray Co., Ltd.
-
Asahi Roentgen Ind. Co., Ltd.
-
Epica International, Inc.
-
Xoran Technologies LLC
-
Palodex Group (KaVo)
-
Midmark Corporation
-
Danaher Corporation
Cone Beam Computed Tomography Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.72 Billion |
| Market Size by 2035 | USD 1.95 Billion |
| CAGR | CAGR of 10.45% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Instrument and Software & Services) • by Application (Dental Imaging, ENT Imaging, Orthopedic Imaging, and Breast Imaging) • by Patient Position (Supine, Standing/Sitting, and Seated) • by End-User (Dental Clinics, Hospitals, Orthopedic Centers, and Ambulatory Surgical Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Planmeca Group, Dentsply Sirona Inc., Vatech Co., Ltd., Carestream Health, Inc., Fussen Group, PreXion Corporation, iCRco Inc., Idetec Medical Imaging, CurveBeam AI, J. Morita Corporation, GE HealthCare Technologies Inc., NewTom (Cefla s.c.), Owandy Radiology, Genoray Co., Ltd., Asahi Roentgen Ind. Co., Ltd., Epica International, Inc., Xoran Technologies LLC, Palodex Group (KaVo), Midmark Corporation, Danaher Corporation |

Frequently Asked Questions
Key players include Planmeca Group, Dentsply Sirona Inc., Vatech Co., Ltd., Carestream Health, Inc., GE HealthCare Technologies Inc., and J. Morita Corporation, among other imaging equipment manufacturers.
Continued advancement of AI-assisted image reconstruction and expansion into ENT, orthopedic, and broader hospital-based applications represent the primary opportunities for manufacturers.
Standing Position, Seated Position, and Supine Position are the sub-segments of by product type.
By Product Type, Instrument dominated the market with a 76.40% share in 2025, reflecting the scanner's role as the core capital investment for adopting practices.
North America dominated the market with a 39.80% share in 2025, supported by a well-established dental clinic base and early adoption of AI-assisted imaging technology.
