
Dental Practice Management Software Market Report Scope & Overview:
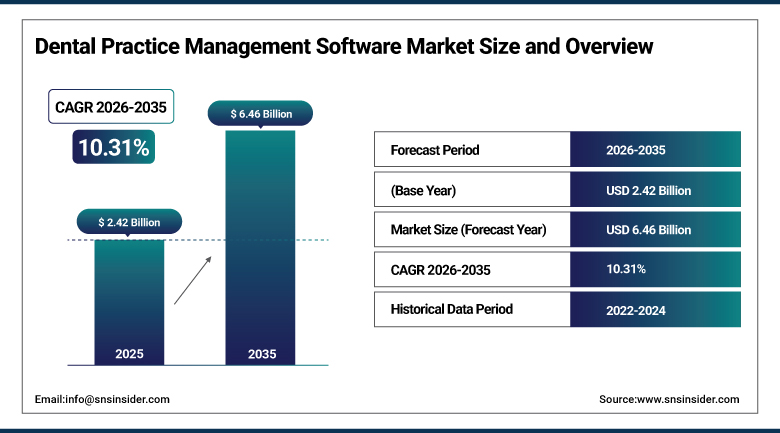
The Dental Practice Management Software Market was valued at USD 2.42 Billion in 2025 and is expected to reach USD 6.46 Billion by 2035, growing at a CAGR of 10.31% from 2026-2035.
The Dental Practice Management Software Market is expanding as dental offices replace paper charts and desktop programs with connected digital systems. These platforms manage scheduling, patient records, billing, insurance claims and patient messaging. Cloud delivery is lowering the cost of setup and allowing remote access across multiple offices. Dental service organizations are standardizing software across large groups. Artificial intelligence now supports voice charting, claim checks and appointment reminders. Links with imaging, payment and analytics tools are also becoming standard. Data privacy duties and migration risk still slow switching at small practices. The market is expected to grow as practices seek efficiency and better patient experience.
⮞In May 2026, a Dental Reviewed survey of 300 dentists in the United Kingdom, the United States and Canada found that 32% use at least one artificial intelligence tool. The adoption shows rising demand for software that connects clinical and administrative workflows.
To Get more information Dental Practice Management Software Market - Request Free Sample Report
Dental Practice Management Software Market Trends
-
Migration from on-premise servers to cloud-based platforms with subscription pricing
-
Use of artificial intelligence for voice charting, insurance checks and patient messaging
-
Standardization of one software platform across dental service organizations
-
Integration of practice software with imaging, payments and analytics tools
-
Growth of patient self-service tools such as online booking, forms and text reminders
U.S. Dental Practice Management Software Market Outlook
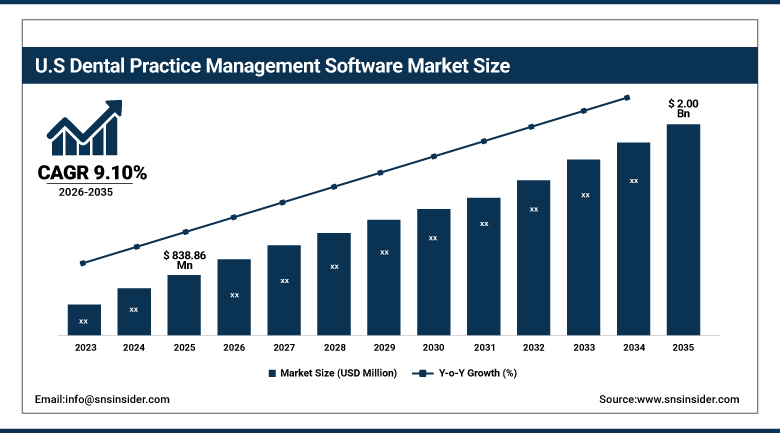
The U.S. Dental Practice Management Software Market was valued at USD 838.86 Million in 2025 and is expected to reach USD 2.00 Billion by 2035, growing at a CAGR of 9.10% from 2026-2035.
The U.S. Dental Practice Management Software Market is the largest national market and is supported by about 200,000 practicing dentists. Most offices already use some form of software, so demand centers on upgrades to cloud systems. Dental service organizations buy for many locations and prefer platforms with strong reporting. Insurance rules make claim handling a major use of software. Privacy rules under the Health Insurance Portability and Accountability Act raise security needs. Vendors compete on voice charting, patient communication and integrations. Switching costs and data migration remain barriers. Demand is therefore expected to rise as practices modernize and groups consolidate.
⮞In March 2026, Henry Schein One reported that its customers completed 191 million insurance eligibility checks in 2025. The volume shows how heavily U.S. practices rely on software for insurance workflows.
Dental Practice Management Software Market Segment Analysis
-
By Deployment, the Web-Based segment dominated the Dental Practice Management Software Market with approximately 47.23% share in 2025, while the Cloud-Based segment is the fastest growing with a CAGR of approximately 12.03%.
-
By Application, the Patient Communication segment dominated the Dental Practice Management Software Market with approximately 36.75% share in 2025, while the Analytics segment is the fastest growing with a CAGR of approximately 15.36%.
-
By End User, the Dental Clinics segment dominated the Dental Practice Management Software Market with approximately 56.80% share in 2025, while the Hospitals segment is the fastest growing with a CAGR of approximately 12.70%.
-
By Practice Size, the Solo Practices segment dominated the Dental Practice Management Software Market with approximately 40.13% share in 2025, while the Dental Service Organizations segment is the fastest growing with a CAGR of approximately 17.60%.
By Deployment, Web-Based Dominates the Dental Practice Management Software Market and Cloud-Based Grows Fastest
Web-based systems prevail because they let dentists and staff launch the software via their browser, instead of maintaining their own servers. There is already plenty of vendors that offer web-based solutions and they retain the user interface but make less use of on-premises hardware. Clinics appreciate the ability to check their schedules and charts online and it helps the owners who work with multiple locations. The updates are easy with web delivery as vendors update the software automatically and there is no need for a technician's visits anymore. Startups can also afford to buy web-based software with a monthly payment instead of buying licenses.
Cloud-based systems grow the fastest because vendors create software designed for multi-tenancy, automatic backups, and open integrations. Dental service organizations prefer cloud software because they can see the information about all of the sites and make changes quickly. Artificial intelligence services like voice charting and claim scrubbing are provided mostly via cloud solutions and that enhances their popularity. Cybersecurity needs are also driving practices towards using the cloud as there is no way to patch old on-premises servers and protect against cyber-attacks.
⮞In June 2024, tab32 said that about USD 1.80 billion in annual revenue flows through its cloud-based platform as it integrated Pearl Second Opinion. The figure shows the transaction volume that cloud vendors now handle.
By Application, Patient Communication Dominates the Dental Practice Management Software Market and Analytics Grows Fastest
Patient communication drives applications since practices require reminders, online forms, two-way texting, and review requests to keep the schedule full. No-shows cost practices money, and automated messaging eases the load on the front desk. Patients today expect booking, confirmation and payment online, so practices use tools that allow for that. Patient communication modules facilitate recall campaigns and treatment follow-ups which increase the case acceptance rates. Providers bundle these modules into their core platforms and partner with specialists to satisfy demand. Automated recall lists and treatment reminders are helpful in the re-engagement of patients lost to practices. Hence, patient communication software is currently one of the fastest ways of ROI.
Analytics is the fastest-growing technology since practice owners and group managers want to have clear insight into production, collections, treatment acceptance and provider performance. Dashboards allow dental service organizations to analyze different practices within the organization and find weaknesses in their scheduling or billing systems. Artificial intelligence allows for forecasting and benchmarking as well as recommendations to drive decision-making.
⮞In August 2026, Open Dental released version 26.2 in beta, adding a Glidewell integration and new API endpoints. The release shows how vendors are widening integration options for practices.
By End User, Dental Clinics Dominates the Dental Practice Management Software Market and Hospitals Grows Fastest
Dental clinics account for the largest share because most dentistry is delivered in private offices that need tools for scheduling, charting, billing and insurance. Clinics range from single-dentist offices to multi-specialty centers, and most now use some digital system. Owners look for software that is easy to learn and works with their imaging and payment tools. Vendors target them with bundled packages and training. Clinics also benefit from software that supports compliance with privacy rules, which lowers legal risk. Software is also used to manage referrals to specialists, patient consent forms and treatment estimates, which makes clinics the most active group of buyers.
Hospitals and specialty centers are growing fastest as health systems bring dental departments under shared information platforms. These organizations need links with medical records, appointment systems and enterprise billing. They place greater weight on security certification and audit features, and they run longer procurement cycles. Dental schools and academic centers also adopt software that supports teaching, research and patient care. As oral health is connected more closely to overall health, demand for integrated systems in hospital settings is expected to increase. Academic hospitals and dental schools also value audit trails and role-based access, which support teaching programs and research reporting.
⮞In May 2026, Planet DDS reported that its 2026 industry analysis covered 497 dental service organizations. The study shows the growing weight of group practices in the buyer base.
By Practice Size, Solo Practices Dominates the Dental Practice Management Software Market and Dental Service Organizations Grows Fastest
Solo practices account for the largest share of installations because most dentists still own and run a single office. These owners buy software that is simple to deploy and does not require an information technology team. Purchases are driven by features such as scheduling, charting, billing and insurance tracking, and by the reputation of the vendor. Many solo practices keep a system for years, so switching is limited. Subscription pricing and vendor-led onboarding are lowering the barrier for those who still use older tools. Owners of solo practices often rely on the vendor's support line and online training, so service quality is a decisive factor when they choose a platform.
Dental service organizations are growing fastest as private equity and group operators acquire independent practices and standardize their systems. A single software platform allows a group to centralize billing, reporting and compliance. Large buyers negotiate multi-year contracts and ask vendors for features such as role-based access, advanced analytics and API integration. Group operators also run acquisition integrations, which creates recurring migration projects for vendors. This segment offers high contract value and long customer lifetimes, so suppliers are building dedicated products for it. Reporting on provider productivity, collections and overhead helps them compare each acquired office with the group average and plan staffing.
⮞In September 2025, Standard Dental acquired the assets of iCoreConnect, which served more than 20,000 dental offices. The deal shows consolidation among providers of software to dental practices.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
81.35 |
|
Europe |
Germany |
23.62 |
|
Asia Pacific |
China |
31.46 |
|
Latin America |
Brazil |
52.27 |
|
Middle East & Africa |
Saudi Arabia |
28.91 |
North America Dental Practice Management Software Market Insights
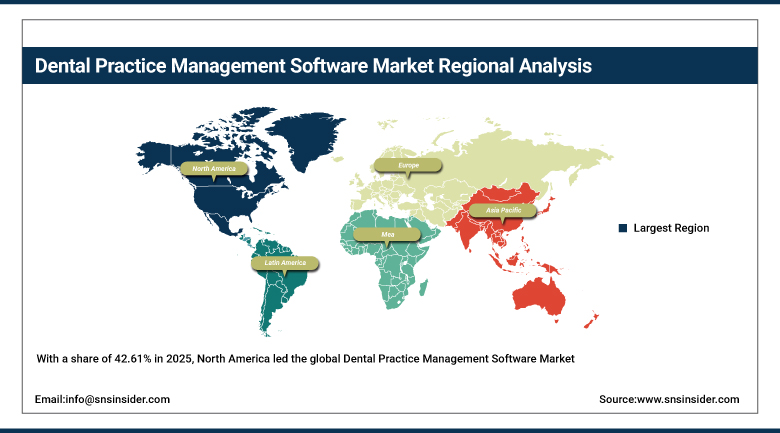
With a share of 42.61% in 2025, North America led the global Dental Practice Management Software Market. The United States contributes most regional demand because of its large dentist population, high spending on dental care and early adoption of cloud tools. Canada adds steady purchases as practices move away from legacy systems. Large dental service organizations in the region buy for hundreds of locations and push vendors to add reporting, security and integration features. Leading vendors include Henry Schein One, Planet DDS, Curve Dental, tab32, Open Dental and Archy, and competition centers on artificial intelligence features and ease of migration.
Regulatory requirements shape purchasing. Practices must protect patient data under privacy rules, and proposed updates to the security standard would require stronger controls such as multi-factor authentication. Insurance complexity increases the value of eligibility checks, claim scrubbing and electronic payments. Venture investment and private equity ownership have increased the pace of product development and acquisitions. Mexican practices serving cross-border patients adopt digital records and online booking, which adds a smaller growth stream to the regional total. Large buyers also run formal vendor reviews that score security, support quality and the pace of product updates, which favors established suppliers.
⮞In August 2025, Curve Dental, whose cloud platform has more than 80,000 users in the United States and Canada, added Pearl Practice Intelligence through an integration. The link shows how vendors are embedding artificial intelligence in the practice workflow.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Dental Practice Management Software Market Insights
Europe is the second largest region, led by Germany, the United Kingdom, France, Italy and Spain. The United Kingdom has a large private dentistry sector and established cloud vendors such as Dentally and Software of Excellence. Germany has tens of thousands of practices that must meet strict data protection rules and statutory billing procedures. Dental chains in Spain and the Nordic countries are expanding and are standardizing software across sites. Local language support and integration with national insurance or billing systems are important buying criteria in each country.
The General Data Protection Regulation raises the importance of secure hosting, access controls and audit trails. Workforce shortages in many countries are encouraging practices to automate administrative tasks, which supports adoption of online booking and digital forms. Internationally qualified dentists are joining national registers in larger numbers, which adds new practice owners. Vendors are adding artificial intelligence features for charting and patient communication, but they must adapt to differing national rules. Cross-border groups prefer cloud systems that can serve several countries under one contract.
⮞In December 2025, the General Dental Council counted 47,916 dentists on the United Kingdom register, an increase of 3.4%. The larger workforce expands the base of practices that buy management software.
Asia Pacific Dental Practice Management Software Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 12.81% during 2026-2035. China, Japan, India, Australia and South Korea lead regional demand. Rising incomes, a growing middle class and expansion of private dental chains are lifting software adoption. Australia has a mature market with local vendors such as Centaur Software, and many practices are migrating to cloud systems. India has a large number of independent clinics, and demand is growing for low cost cloud tools that handle appointments and billing.
China is building digital dental chains that rely on integrated systems for scheduling, patient records and payments. Japan has an older population and a high number of clinics, and software demand centers on insurance claims and recall. Southeast Asian countries are adding private clinics for dental tourism, which creates new buyers. Governments are promoting digital health initiatives, and mobile payment use is making online billing practical. Vendors from North America and Europe are partnering with local resellers to enter these markets.
⮞In January 2025, Australian vendor Centaur Software integrated Pearl's artificial intelligence second opinion into its Mediasuite platform. The link shows how local vendors are adding imaging analysis to their software.
MEA & Latin America Dental Practice Management Software Market Insights
In Latin America, the largest market is Brazil due to the presence of a significant number of dentists and the activity of the private clinic segment. Other big players include Mexico, Argentina, Colombia, and Chile where clinics utilize cloud software for appointment management, payment and messaging. Vendors cater to Portuguese and Spanish speakers and integrate with the local tax system. Changes in currency exchange rates and tight budgets prevent heavy spending, thus subscription-based pricing model helps small clinics implement digital solutions. Dental tourism in Mexico and Costa Rica promotes investments in online booking and patient communication.
In Middle East and Africa, the biggest market is Saudi Arabia and United Arab Emirates because of the launch of new private dental practices and large hospital networks. Health initiatives in the Gulf region promote digitalization of dental records and electronic billing. In South Africa, there is an advanced private dental industry and growing adoption of cloud solutions. The lack of training and poor broadband infrastructure hinders implementation in other countries in Africa. Vendors gain access to these markets through regional distributors and dental associations partnerships. Public hospitals in the Gulf region upgrade their dental departments and tender electronic records and online scheduling.
⮞In May 2026, Saudi Arabia's Ministry of Health reported more than 32,000 dental practitioners in the country. The workforce shows the scale of the Gulf market that software vendors can address.
Market Dynamics
Growth Drivers: Digitization of Dental Offices and Artificial Intelligence
Digitization of dental offices is the main driver of the market. Practices are replacing paper charts, local servers and manual claim handling with systems that connect scheduling, clinical notes, billing and insurance. These tools reduce administrative work, which matters at a time when many offices face staffing shortages. Cloud delivery lowers upfront cost, and subscriptions spread payments over time. Dentist populations are growing in many countries, which adds new offices that need software from the start. Integration of software with digital imaging and payment terminals saves time for staff and reduces errors in daily operations.
Artificial intelligence adds a second layer of demand. Voice charting lets clinicians dictate notes during procedures, and automated tools check insurance eligibility, prepare claims and answer routine patient messages. Vendors that embed these features can charge higher subscription prices and increase customer retention. Dental service organizations favor platforms with automation because they reduce cost across many locations. As adoption grows, practices that have not yet digitized face pressure to upgrade to remain competitive. Patients also expect to receive text reminders and pay online, which pushes practices that have not yet digitized to adopt new tools.
⮞In Germany, the Kassenzahnärztliche Bundesvereinigung reported 63,049 dentists in mid-2025, of whom 20,501 were employed. The dentist base shows the large number of practices and employment arrangements that need software.
Restraints: Data Privacy Requirements and Switching Costs
The restraints include data privacy and cybersecurity concerns. Dentists' offices deal with highly private patient information and should adhere to regulations like the HIPAA in the US and the GDPR in Europe. Failing to do so can result in fines and reputational damage. Small dental practices lack technical specialists to address their security issues, and vendors should spend money on encryption, authentication, and audits, thus increasing their pricing and the sales cycle. Cybersecurity breaches at healthcare institutions receive media attention, and one should expect more audits of smaller healthcare providers.
Costs associated with switching to a different product represent another restraint. Migrating patient data, imaging, accounting, and other data from one system to another takes time and can generate mistakes. The personnel should get accustomed to a different workflow, and many dental practices will not generate revenue while the process is going on. That is why many owners prefer sticking to older software that is inferior to the new software in functionality. High upfront expenses associated with learning the software and its integration into an office also make small dental practices in emerging markets shy away from the switch due to poor connectivity and budget restrictions.
⮞In January 2025, the U.S. Department of Health and Human Services Office for Civil Rights proposed updates to the HIPAA Security Rule that include a 72-hour recovery objective. The proposal signals higher security expectations for software used by dental practices.
Opportunities: AI-Enabled Platforms and Group Practice Consolidation
AI-enabled platforms offer a significant opportunity. Vendors can sell voice documentation, insurance automation and patient messaging as premium modules, and these features show a clear return on investment. Partnerships with imaging, payment and analytics companies allow vendors to offer complete workflows from diagnosis to payment. Professional organizations are also endorsing platforms, which builds trust among members. Companies that deliver reliable automation can gain share from older systems. Vendors can also upsell payments, financing and patient engagement products that sit on top of the core platform.
Group practice consolidation provides another opportunity. Private equity backed networks and dental service organizations are buying independent offices and need standard systems across many sites. Vendors that can migrate data quickly and support enterprise reporting can win large contracts with high lifetime value. Emerging markets in Asia Pacific, Latin America and the Middle East also offer room for growth as dental chains expand and governments promote digital health. Subscription models make entry easier for smaller practices. Strong channel partnerships with dental distributors and laboratories can expand reach into practices that rarely respond to direct sales.
⮞In June 2026, the Academy of General Dentistry announced a partnership with Oryx that gives members preferred rates on its cloud-based, AI-powered practice management software. The partnership shows how associations are guiding members toward integrated platforms.
Recent Developments:
-
2025: Patterson Companies completed its acquisition by Patient Square Capital and ceased trading on Nasdaq. The company is the owner of the Eaglesoft and Fuse software lines, and the change gives its dental technology business private ownership.
-
2025: Dandy announced the acquisition of Neem, a provider of dental practice management software. The deal adds a cloud software product to Dandy's laboratory and digital dentistry services.
-
2026: Archy announced a USD 50 million Series C funding round led by JMI Equity. The company said that the funds will support product development for its cloud-based practice management platform.
Dental Practice Management Software Market Key Players are
-
Henry Schein One (Dentrix, Dentally, and Software of Excellence)
-
Planet DDS (Denticon)
-
tab32
-
Open Dental Software
-
CareStack (Good Methods Global Inc.)
-
Archy
-
Patterson Companies (Eaglesoft and Fuse)
-
Carestream Dental (Sensei Cloud and CS SoftDent)
-
Centaur Software (Dental4Windows)
Dental Practice Management Software Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.42 Billion |
| Market Size by 2035 | USD 6.46 Billion |
| CAGR | CAGR of 10.31% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Deployment (Web-Based, Cloud-Based, and On-Premise) • By Application (Patient Communication, Scheduling, Invoice and Billing, Payment Processing, Insurance Management, Analytics, and Other Applications) • By End User (Dental Clinics, Hospitals, and Other End Users) • qBy Practice Size (Solo Practices, Small Group Practices, Large Group Practices, and Dental Service Organizations) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Henry Schein One , Planet DDS Curve Dental, tab32, Open Dental Software, CareStack ,, Archy, Oryx Dental Software, Patterson Companies , Carestream Dental , Centaur Software |

Frequently Asked Questions
Key players include Henry Schein One, Planet DDS, Curve Dental, tab32, Open Dental Software, CareStack, Archy, Oryx Dental Software, Patterson Companies, Carestream Dental and Centaur Software.
Key opportunities include AI-enabled modules for voice charting and insurance automation, enterprise platforms for dental service organizations and growth in Asia Pacific and other emerging regions.
Digitization of dental offices is the main growth factor, supported by cloud delivery, artificial intelligence features and consolidation of practices into groups.
By Deployment, the Web-Based segment dominated the market in 2025 with an estimated 47.23% share, supported by easy browser access, lower hardware needs and subscription pricing.
North America dominated the market with a share of 42.61% in 2025, driven by a large dentist base, early adoption of cloud software and demand from dental service organizations.
