
Dairy Product Packaging Market Report Scope & Overview:
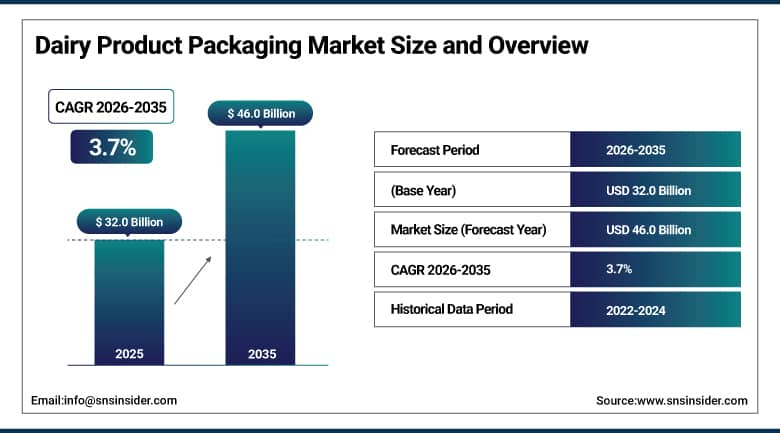
The Dairy Product Packaging Market was valued at USD 32.0 Billion in 2025 and is expected to reach USD 46.0 Billion by 2035, growing at a CAGR of 3.7% from 2026–2035.
Dairy packaging has to do more work than most food packaging categories, keeping a product fresh, cold, and safe from spoilage while surviving refrigerated transport, retail handling, and, increasingly, extended ambient shelf life for aseptic cartons. Milk still drives the bulk of category volume, but yogurt, cheese, butter, and ice cream each carry their own packaging demands around barrier protection, portion sizing, and shelf presentation. Sustainability pressure and single-serve convenience trends are reshaping format choices faster than almost any other packaging category right now.
Tetra Pak has spent years developing what it calls the industry's first fibre-based barrier to replace the thin aluminum layer inside a standard aseptic carton, first deployed commercially with Portuguese dairy producer Lactogal in 2023 and scaled onto high-speed production lines in Asia in 2026, where South Korea's Maeil Dairies became the first company anywhere to use it for a shelf-stable soya beverage. The technology, backed by roughly €100 million a year in ongoing Tetra Pak investment, aims to make aseptic cartons recyclable through standard paper-recycling streams rather than the specialized facilities aluminum-lined cartons require.
To Get More Information On Dairy Product Packaging Market - Request Free Sample Report
Dairy Product Packaging Market Trends
-
Manufacturers are racing to replace aluminum-lined aseptic cartons with fibre-based barrier alternatives that can be recycled through standard paper streams rather than specialized facilities most municipalities don't have.
-
Single-serve and portion-controlled packaging is expanding quickly as single-person households and busy lifestyles drive demand for smaller, on-the-go formats across milk, yogurt, and cheese products.
-
Smart packaging features, QR-enabled traceability and freshness indicators, are gaining traction as retailers and consumers both push for greater transparency around sourcing and shelf life.
-
Flexible pouches continue taking share from rigid bottles and cartons in price-sensitive and emerging markets, offering lower material costs and shipping weight for everyday milk and yogurt packaging.
-
Industry consolidation among major packaging suppliers is accelerating as companies chase the scale needed to absorb rising material costs and fund the sustainability R&D that dairy processors increasingly require from their packaging partners.
U.S. Dairy Product Packaging Market Outlook
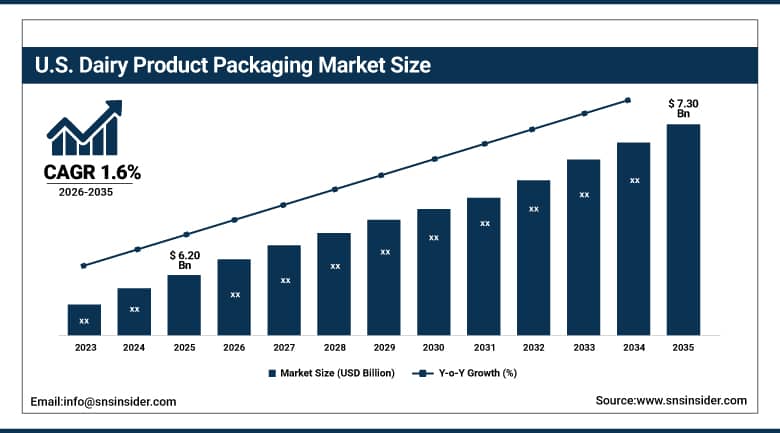
The U.S. Dairy Product Packaging Market was valued at approximately USD 6.20 Billion in 2025 and is expected to reach approximately USD 7.30 Billion by 2035, growing at a CAGR of approximately 1.6%.
In the USA, the demand is underpinned by high levels of dairy consumption, deep penetration of the packaged foods segment and packaging formats which influence the presence on shelves rather than products themselves within the retail sector. The growth of single household sizes and lifestyle trends keep driving demand towards single serve and portion-controlled packaging formats for cheeses, milk and yogurts at the expense of bulk packaging. Growth is relatively slow compared to fast-developing emerging markets, indicating the maturity of the segment in the USA.
Amcor completed its merger with Berry Global in 2025, combining two of the largest packaging companies serving U.S. dairy producers into a single organization with a substantially larger flexible and rigid plastic packaging portfolio. The deal reflects the broader consolidation pressure facing dairy packaging suppliers as they balance sustainability investment against the scale advantages needed to serve major U.S. dairy processors cost-effectively.
Dairy Product Packaging Market Segment Analysis
-
By Material, the Plastic segment dominated the Dairy Product Packaging Market with approximately 52.0% share in 2025, while the Paper & Paperboard segment is the fastest growing with a CAGR of approximately 6.4%.
-
By Packaging Type, the Rigid segment dominated the Dairy Product Packaging Market with approximately 46.0% share in 2025, while the Flexible segment is the fastest growing with a CAGR of approximately 6.8%.
-
By Format, the Cartons & Boxes segment dominated the Dairy Product Packaging Market with approximately 48.6% share in 2025, while the Pouches segment is the fastest growing with a CAGR of approximately 7.2%.
-
By Application, the Milk segment dominated the Dairy Product Packaging Market with approximately 38.0% share in 2025, while the Yogurt segment is the fastest growing with a CAGR of approximately 6.9%.
-
By End Use, the Household & Retail segment dominated the Dairy Product Packaging Market with approximately 64.0% share in 2025, while the Commercial & Foodservice segment is the fastest growing with a CAGR of approximately 5.8%.
-
By Distribution Channel, the Supermarkets & Hypermarkets segment dominated the Dairy Product Packaging Market with approximately 58.0% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 9.2%.
By Material, plastic dominates, paper & paperboard grows fastest
Plastic held the largest share of the material segment in 2025, valued for its low cost, light weight, and versatility across nearly every dairy packaging format, from yogurt cups to milk bottles. Its barrier properties and manufacturing flexibility keep it the default material choice for most mainstream dairy packaging applications.
Paper and paperboard are growing fastest as sustainability regulation and consumer preference both push dairy processors toward fibre-based alternatives that recycle more easily than plastic. New barrier technologies that let paperboard cartons match plastic's moisture and oxygen protection without an aluminum lining are accelerating this shift faster than paper packaging has historically been able to expand in liquid dairy applications.
By Packaging Type, rigid dominates, flexible grows fastest
The rigid packaging segment made up the biggest portion in 2025, which includes such containers as bottles, cartons, and tubs that provide good strength to protect items inside them and good visual shelf appeal, including items such as milk, yogurt, and butter. The rigid format also provides good shelf visibility, which is a critical factor for branded products competing for shelf space.
The flexible packaging segment is the fastest-growing due to the advantages that it provides compared to rigid formats because of its cheaper material, lighter weight in shipping and storage, and small volume. Flexible packaging is especially popular in price-conscious and emerging markets, where the pouches allow the processor to sell a product at a lower price but not lower shelf-life.
By Format, cartons & boxes dominate, pouches grow fastest
Cartons and boxes, which comprise mostly liquid paperboard cartons for milk, had the highest share of format in 2025, helped by years of proven technology for aseptic and gable-top cartons that dairy processors and retailers trust. High speed fill line capability and extended ambient shelf life of aseptic cartons make cartons dominant packaging for liquid dairy products.
Pouches are expected to grow the most as spouted and stand-up pouches become popular choices for milk, yogurt, and dairy beverages, especially in developing countries and those catering to on-the-go consumption segments. The low cost of raw materials and reduced shipping volume of pouches make them an increasingly preferred alternative to rigid packaging among dairy processors.
By Application, milk dominates, yogurt grows fastest
Milk accounted for the largest application share in 2025, reflecting its position as the highest-volume dairy product globally and the resulting scale of packaging demand needed to support it. Nearly every packaging format and material innovation in the category gets tested first in milk packaging given the sheer volume at stake.
Yogurt is the fastest-growing application as rising health consciousness and growing consumption of probiotic and functional yogurt products continue expanding the category faster than traditional milk consumption growth. Portion-controlled and single-serve yogurt packaging in particular has become a significant growth driver as consumers favor convenient, on-the-go formats.
By End Use, household & retail dominates, commercial & foodservice grows fastest
Household and retail uses were the leading end-use application segment in 2025 due to the nature of dairy products being a daily consumer item that is constantly bought by households across the globe. All aspects of retail packaging, its presentation on shelves, and size considerations are made with the consumer market in mind.
Commercial use and food service segments are experiencing the greatest rate of growth due to the increasing number of restaurants and cafés that drive the need for bulk and specialized food service dairy packaging. Expansion of coffee shops has contributed significantly to the rise of bulk milk and cream packaging.
By Distribution Channel, supermarkets & hypermarkets dominate, online retail grows fastest
Supermarkets and hypermarkets dominated the distribution channels share in 2025 and will continue to be the first choice for purchasing dairy products by most households because of their cold chain logistics system and extensive range of products. The refrigerated retail logistic system used for packaging of dairy products makes this distribution channel superior to smaller retail channels.
E-commerce is the fastest-growing distribution channel due to the growth of online groceries and dairy subscription and delivery channels, and packaging needs to be made resilient enough to protect itself against more handling and exposure to varying temperatures when shipped directly to consumers.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.0% |
|
North America |
United States |
81.0% |
|
Europe |
Germany |
24.0% |
|
Latin America |
Brazil |
40.0% |
|
Middle East & Africa |
Saudi Arabia |
29.0% |
Asia Pacific Dairy Product Packaging Market Insights
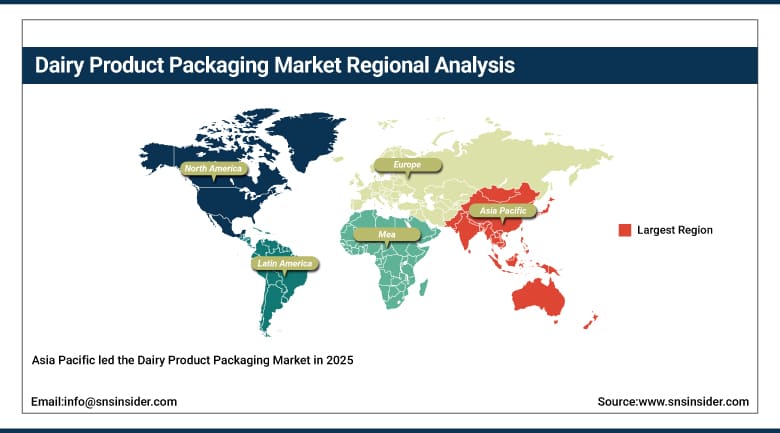
Asia Pacific led the Dairy Product Packaging Market in 2025 and is also expected to register the fastest regional growth through 2035, driven by rising dairy consumption, population growth, and expanding organized retail networks across China and India. Growing urbanization and rising disposable incomes continue pushing more consumers toward packaged, branded dairy products over unpackaged local alternatives.
China's large-scale dairy processing industry drives substantial regional packaging demand, while India's expanding organized dairy sector and private-brand growth are adding meaningful volume on top of the country's already massive traditional dairy cooperative network. Southeast Asian markets are following a similar trajectory as regional dairy consumption and modern retail infrastructure both continue expanding.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Dairy Product Packaging Market Insights
North America remains a significant dairy product packaging market, with the United States accounting for the large majority of regional demand thanks to high dairy consumption and deep packaged food retail penetration. Advanced packaging technology adoption, including smart packaging and enhanced barrier materials, is more developed in this region than in most emerging markets.
Canada contributes additional demand through its own dairy processing and retail sector, while Mexico's market continues expanding alongside growing packaged food consumption. Cross-border supply chains tie much of North American demand together, with major packaging suppliers typically serving all three markets through shared manufacturing and distribution networks.
Europe Dairy Product Packaging Market Insights
Europe is characterized by an established and regulated market for dairy products packaging where the influence of EU packaging waste directives and consumer demand for sustainable and recyclable packaging is extremely high. Germany is the center of regional demand due to its sizeable dairy processing sector as well as presence of several big companies manufacturing packaging products.
Another significant countries in terms of volume of demand are France, the Netherlands, and the UK as each of these countries has a significant dairy processing sector that adjusts to EU regulations regarding sustainability.
MEA & Latin America Dairy Product Packaging Market Insights
The Middle East and Africa represent a smaller but developing dairy product packaging market, with Saudi Arabia and the UAE driving demand through growing dairy consumption and modern retail expansion tied to rising urbanization. South Africa anchors demand across the rest of the continent, supported by a more established dairy processing and packaging infrastructure than most of its neighbors.
Latin America is a significant and growing market led by Brazil, where expanding organized dairy retail and rising packaged milk and yogurt consumption continue driving packaging demand higher. Mexico contributes a meaningful secondary share of regional demand, tied closely to its growing packaged food and beverage sectors.
Growth Drivers: Sustainability regulation and convenience packaging fueling demand
Tightening sustainability regulation across major markets is one of the clearest forces behind dairy packaging innovation, as EU packaging waste directives and similar frameworks elsewhere push processors toward recyclable and reduced-material formats. Packaging suppliers that can deliver credible sustainability improvements without sacrificing shelf life or barrier performance are capturing disproportionate new business as a result.
Rising demand for single-serve and portion-controlled packaging adds a second major driver, as single-person households and busy lifestyles continue reshaping how consumers buy and consume dairy products. That shift toward smaller, more convenient formats is reshaping packaging line investment across the industry, favoring processors and suppliers who can offer flexible, smaller-batch production.
Restraints: Cold-chain requirements and material cost volatility limiting margin stability
The need for a rigorous cold chain and shelf-life management protocol brings additional levels of complexity in relation to shelf-stable packaged food categories, restricting the scope for innovations in packaging towards reduced weight and costs, and preserving safety. This makes it difficult to cut costs significantly on the side of the packaging materials used for dairy.
The fluctuations in the prices of raw materials, especially plastic resin and specialty paperboard, bring even more challenges to the already squeezed margins. Suppliers not bound by contracts for the supply of the required materials face a serious challenge even when the demand for the finished products is constant.
Opportunities: Fibre-based barrier technology and smart packaging opening new growth avenues
Fibre-based barrier technology that eliminates the need for aluminum linings in aseptic cartons offers packaging suppliers a genuine path to capturing premium pricing from processors chasing credible sustainability improvements. Companies that scale this technology successfully are positioned to capture a growing share of the aseptic carton market as recyclability requirements continue tightening globally.
Smart packaging features, QR-enabled traceability, freshness indicators, and connected labeling, represent a second significant opportunity, letting brands differentiate on transparency and food safety in a category where consumer trust matters enormously. Packaging suppliers that build genuine smart-packaging capability are positioned to capture premium pricing from brands looking to differentiate beyond price alone.
Recent Developments
-
Q1 2024: SIG Combibloc opened a new manufacturing facility in India focused on aseptic carton packaging for dairy products, aiming to serve growing demand across South Asia.
-
Q3 2024: SIG Combibloc raised €100 million through a green bond offering, with proceeds earmarked for sustainable dairy packaging projects.
-
Q2 2024: Amcor launched a fully recyclable dairy packaging solution in Europe, designed to comply with new EU packaging regulations.
-
2025: SIG Combibloc's new production plant in Querétaro, Mexico entered operations, aimed at expanding the company's aseptic carton capacity across North America.
Dairy Product Packaging Companies are:
-
Tetra Pak International S.A.
-
Amcor plc
-
SIG Combibloc Group AG
-
Elopak ASA
-
Greatview Aseptic Packaging Co., Ltd.
-
Sealed Air Corporation
-
Huhtamaki Oyj
-
Stora Enso Oyj
-
International Paper Company
-
Berry Global Group, Inc.
-
Nampak Ltd.
-
Mondi Group
-
Smurfit WestRock plc
-
Coveris Management GmbH
-
Winpak Ltd.
-
Constantia Flexibles Group GmbH
-
ProAmpac Holdings Inc.
-
UFlex Limited
Dairy Product Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 32.0 Billion |
| Market Size by 2035 | USD 46.0 Billion |
| CAGR | CAGR of 3.7% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material (Plastic, Paper & Paperboard, Glass, Metal & Steel, Others) • by Packaging Type (Rigid, Flexible, Semi-Rigid) • by Format (Cartons & Boxes, Bottles, Cans, Cups, Pouches, Films & Wraps, Others) • by Application (Milk, Yogurt, Cheese, Butter & Ghee, Ice Cream, Others) • by End Use (Household & Retail, Commercial & Foodservice) • by Distribution Channel (Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Tetra Pak International S.A., Amcor plc, SIG Combibloc Group AG, Elopak ASA, Greatview Aseptic Packaging Co., Ltd., Pactiv Evergreen Inc., Sealed Air Corporation, Huhtamaki Oyj, Stora Enso Oyj, International Paper Company, Berry Global Group, Inc., Nampak Ltd., Mondi Group, Smurfit WestRock plc, Ecolean AB, Coveris Management GmbH, Winpak Ltd., Constantia Flexibles Group GmbH, ProAmpac Holdings Inc., UFlex Limited |
Frequently Asked Questions
The Dairy Product Packaging Market is expected to grow at a CAGR of 3.7% from 2026 to 2035.
The Dairy Product Packaging Market was valued at USD 32.0 Billion in 2025.
Tightening sustainability regulation pushing processors toward recyclable materials, alongside rising demand for single-serve and portion-controlled dairy packaging.
Milk dominated with approximately 38.0% share in 2025, while Yogurt is the fastest growing segment with a CAGR of approximately 6.9%.
Asia Pacific dominated the Dairy Product Packaging Market in 2025 and is also the fastest-growing region.
