
Dental Bone Grafts and Substitutes Market Report Scope & Overview:
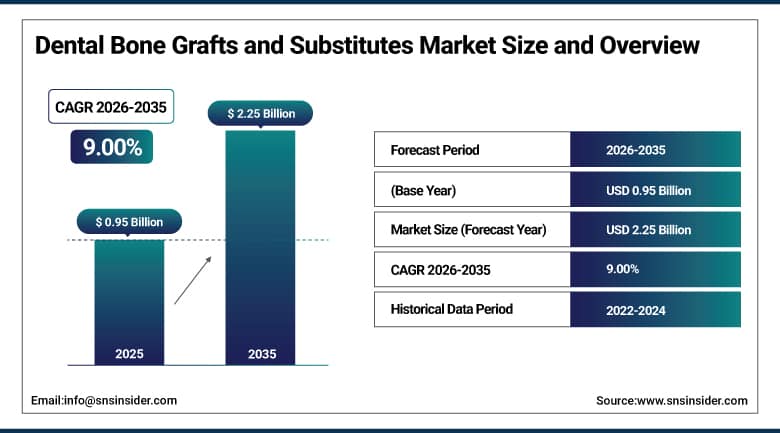
The Dental Bone Grafts and Substitutes Market was valued at USD 0.95 Billion in 2025 and is expected to reach USD 2.25 Billion by 2035, growing at a CAGR of 9.00% from 2026-2035.
Dental bone grafts and substitutes constitute an essential category within regenerative dentistry, integrating xenograft, allograft, autograft, and synthetic materials used to rebuild bone volume ahead of dental implant placement and periodontal defect repair. Rising global adoption of dental implants, increasing incidence of periodontal disease leading to bone loss, and growing patient access to regenerative dental procedures continue to broaden the clinical base requiring these materials. Oral surgeons, periodontists, and an expanding base of general dental practitioners rely on bone grafts and substitutes to restore adequate bone volume and density supporting long-term implant success and periodontal health. Sustained growth is being shaped by continued advancement in growth factor-enhanced synthetic materials, rising adoption of digital in-house workflow planning, and expanding consolidation of dental practices into larger group.
On April 3, 2024, Geistlich Pharma completed the acquisition of Bionnovation Biomedical, a Brazilian developer of innovative biomaterials for bone regeneration in dental applications. The company stated the acquisition strengthens its capabilities in regenerative dentistry, delivering advanced solutions for periodontists, oral surgeons, and clinicians specializing in implant dentistry, while expanding its manufacturing footprint across the fast-growing Latin American regenerative dentistry market.
To Get More Information On Dental Bone Graft And Substitutes Market - Request Free Sample Report
Dental Bone Grafts and Substitutes Market Trends:
-
Growing adoption of growth factor-enhanced synthetic materials improving predictability of bone regeneration.
-
Rising use of digital in-house 3-D printing enabling clinics to design grafts and guides within hours.
-
Expanding consolidation of dental practices into DSO and group practice structures driving procurement volume.
-
Increasing global implant placement volumes translating directly into higher implant regeneration demand.
-
Rising manufacturer investment in next-generation resorbable membranes with improved mechanical stability.
-
Growing preference for hybrid biomaterial designs combining synthetic polymers with natural collagen.
-
Expanding clinical evidence base supporting broader payer and practitioner confidence in synthetic alternatives.
U.S. Dental Bone Grafts and Substitutes Market Overview:
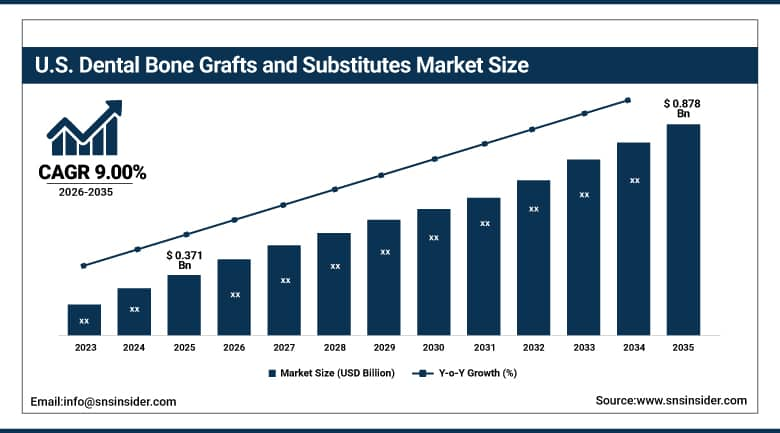
The U.S. Dental Bone Grafts and Substitutes Market was valued at USD 0.371 Billion in 2025 and is expected to reach USD 0.878 Billion by 2035, growing at a CAGR of 9.00% from 2026-2035.
Domestic demand continues to be underpinned by rising adoption of dental implants and by increasing cases of periodontal disease leading to bone loss across the country's dental patient population. Leading manufacturers continue expanding their regenerative dentistry portfolios, including bone regenerative and restorative solutions integrated within broader implant and prosthetics product categories, while continued investment in digital treatment planning software keeps strengthening domestic competitive positioning. Growing transition of dental practitioners toward group practices and dental service organizations further supports domestic market expansion as consolidated purchasing structures increasingly standardize regenerative material procurement across multi-site practice networks nationwide.
In 2024, Dentsply Sirona continued expanding its Orthodontic and Implant Solutions segment, which includes bone regenerative and restorative solutions supporting the company's broader digital workflow ecosystem for implant dentistry. The company stated its regenerative bone growth factor technology and advanced tapered immediate load screw systems continue to support comprehensive implant treatment planning for U.S. clinicians.
Dental Bone Grafts and Substitutes Market Segment Analysis:
-
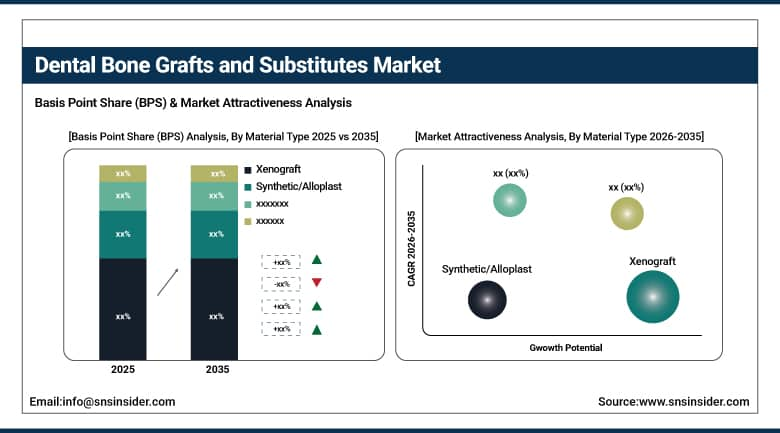
By Material Type, the Xenograft segment dominated the market with a 38.60% share in 2025, while the Synthetic/Alloplast segment is the fastest growing with a CAGR of 10.80% during 2026-2035.
-
By Mechanism, the Osteoconduction segment dominated the market with a 60.53% share in 2025, while the Osteoinduction segment is the fastest growing with a CAGR of 9.35% during 2026-2035.
-
By Application, the Socket Preservation segment dominated the market with a 26.60% share in 2025, while the Implant Bone Regeneration segment is the fastest growing with a CAGR of 12.62% during 2026-2035.
-
By End User, the Dental Clinics segment dominated the market with a 48.60% share in 2025, while the DSO/Group Practices segment is the fastest growing with a CAGR of 11.20% during 2026-2035.
By Material Type, Xenograft Dominates the Market and Synthetic/Alloplast Grows Fastest
Xenograft materials dominated the market in 2025, a position built on their proven osteoconductive scaffold properties, wide commercial availability, and decades of accumulated clinical evidence across guided bone regeneration, socket preservation, and sinus floor elevation procedures. Clinicians favour bovine and porcine-derived xenograft materials precisely because they deliver a slowly resorbing scaffold that maintains ridge volume over an extended healing period without the surgical morbidity associated with harvesting a patient's own bone, a combination that continues to make xenograft the default specification across the widest range of dental bone regeneration applications worldwide, even as synthetic alternatives continue to expand around it.
Synthetic/Alloplast materials are projected to be the fastest-growing material category over the forecast period. Rising demand for growth factor-enhanced synthetic scaffolds continues to expand the addressable application base for this material category as clinicians increasingly seek materials free from animal-derived tissue concerns while still delivering predictable bone regeneration outcomes. As manufacturers continue advancing hydroxyapatite and tricalcium phosphate formulations incorporating recombinant growth factors, synthetic and alloplast materials continue closing the gap with xenograft in overall market demand, particularly among patients and practitioners preferring fully synthetic biomaterial solutions.
By Mechanism, Osteoconduction Dominates the Market and Osteoinduction Grows Fastest
Osteoconduction dominated the market in 2025, accounting for more than three-fifths of overall global market share. This mechanism, in which the graft material serves as a passive scaffold guiding new bone growth from surrounding native bone, continues to represent the most widely used and best-understood regenerative approach across routine dental bone grafting procedures. This foundational, technically straightforward mechanism continues to sustain osteoconduction as the dominant mechanism category by a clear margin across the broader market, given its compatibility with the widest range of graft materials and clinical indications.
Osteoinduction is expected to be the fastest-growing mechanism category over the forecast period. Rising demand for materials capable of actively stimulating new bone formation through growth factor and signaling protein activity continues to expand the addressable application base for this mechanism category, particularly across complex peri-implant defects and larger ridge augmentation cases where passive scaffolding alone may prove insufficient. As implant placement volumes continue climbing and case complexity increases, osteoinductive materials continue closing the gap with conventional osteoconductive alternatives in overall market demand.
By Application, Socket Preservation Dominates the Market and Implant Bone Regeneration Grows Fastest
Socket Preservation applications dominated the market in 2025. This procedure's routine use immediately following tooth extraction to maintain ridge volume and prevent the bone resorption that naturally follows extraction continues to represent one of the single largest drivers of overall dental bone graft consumption worldwide, given how frequently extractions precede eventual implant placement. This foundational, high-frequency procedural role continues to sustain socket preservation as a leading application category by a clear margin across the broader market.
Implant Bone Regeneration applications are projected to expand fastest over the forecast period, as peri-implant deficiencies increasingly demand tailored grafting solutions matched to individual defect morphology. As global implant placement volumes continue rising, demand for bone regeneration procedures addressing insufficient ridge width or height ahead of or alongside implant placement continues to expand rapidly. As dental implant adoption continues extending into broader patient populations, implant bone regeneration applications continue closing the gap with more established application categories in overall market demand.
By End User, Dental Clinics Dominates the Market and DSO/Group Practices Grows Fastest
Dental Clinics dominated the market in 2025. The overwhelming majority of dental bone grafting and implant placement procedures continue to be performed within general and specialty dental clinic settings rather than hospital operating rooms, reflecting the routine, outpatient nature of most contemporary implant and periodontal regenerative procedures. This foundational procedural setting continues to sustain dental clinics as the leading end-user category by a clear margin across the broader market.
DSO/Group Practices are expected to be the fastest-growing end-user category over the forecast period. The rising number of dental service organization visits for dental implants, combined with the ongoing transition of independent dental practitioners toward group practice structures in developed regions, continues to expand the addressable end-user base for this category. As consolidated purchasing power increasingly shapes regenerative material procurement decisions, DSO and group practice structures continue closing the gap with traditional independent dental clinics in overall market demand.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
81.47% |
|
Asia Pacific |
China |
39.62% |
|
Europe |
Germany |
33.18% |
|
Latin America |
Brazil |
45.29% |
|
Middle East & Africa |
United Arab Emirates |
27.84% |
North America Dental Bone Grafts and Substitutes Market Insights
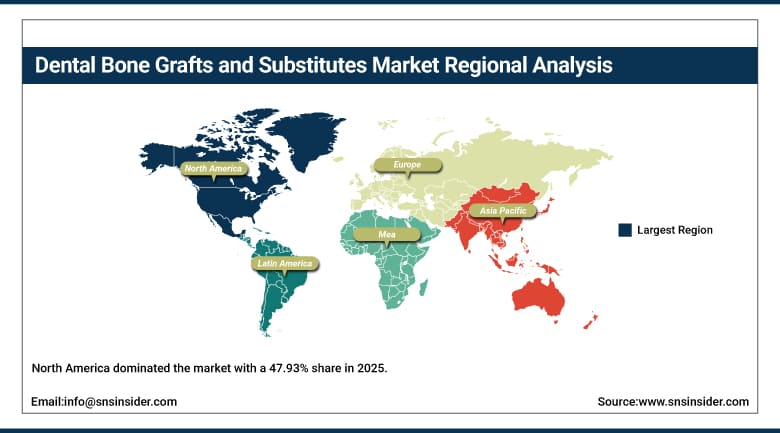
North America dominated the market with a 47.93% share in 2025. The region's substantial dental implant procedure volume, dense concentration of leading biomaterials manufacturers, and rising transition toward group dental practice structures continue to anchor this leadership position across both clinical and DSO-driven procurement channels. The United States shapes regional demand through its concentration of leading regenerative dentistry manufacturers and its role as a proving ground for growth factor-enhanced synthetic biomaterial innovation.
Canada contributes additional regional demand through its participation in North American dental biomaterials procurement and distribution networks. Continued domestic investment in digital treatment planning and growth factor-enhanced synthetic materials is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building out dental implant infrastructure from a considerably smaller existing base.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Dental Bone Grafts and Substitutes Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 10.60% during 2026-2035, supported by a large patient population, expanding access to regenerative dental procedures, and growth in private dental clinics across China, Japan, South Korea, and Australia. China continues to anchor regional demand as domestic dental clinics and hospital dental departments expand implant and regenerative procedure capability across both established coastal manufacturing hubs and rapidly developing regional facilities.
India's expanding dental care access and rising middle-class disposable income continue adding meaningful regional growth as domestic providers extend implant and bone regeneration capability into previously underserved areas. Japan and South Korea contribute further depth through established, technically advanced dental biomaterials manufacturing sectors, positioning the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Dental Bone Grafts and Substitutes Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established dental biomaterials manufacturers and continued advancement in next-generation resorbable membrane and hybrid biomaterial technology. Germany's substantial dental implant and biomaterials manufacturing base anchors regional demand, supported by a well-developed reimbursement and regulatory framework that continues to favour early adoption of next-generation regenerative dentistry technology across the country and neighbouring markets.
Switzerland's concentration of leading global biomaterials headquarters, together with the United Kingdom, France, and Italy, contribute consistent demand as regional dental practitioners continue extending advanced regenerative technology into routine clinical practice. Continued European emphasis on evidence-based, clinically validated biomaterials supports steady regional demand for premium xenograft and synthetic bone graft solutions.
MEA & Latin America Dental Bone Grafts and Substitutes Market Insights
The Latin American market sees growth through Brazil, having the presence of a fairly substantial market for production of dental biomaterials and growing numbers of implants being done that drives demand in the region. The Mexico market also adds further growth, especially as dental tourism and the use of implants increases in the region.
Strategic importance of the Middle East & Africa region increases, with demand for the product seen primarily in GCC countries such as the United Arab Emirates, where increased disposable incomes and investments in dental tourism are driving demand for high-end dental biomaterials. South Africa remains an important driver of demand in Africa because of the relatively more advanced dental infrastructure in the country.
Market Dynamics:
Growth Drivers: Rising Implant Adoption and Periodontal Disease Incidence
Rising adoption of dental implants stands as the primary growth driver, as global implant placement continues climbing and each procedure frequently requires accompanying bone grafting or regeneration to achieve adequate ridge volume and density for successful long-term implant integration. This dynamic is reinforced by increasing incidence of periodontal disease leading to bone loss, as growing patient awareness of oral health and expanding access to periodontal treatment continues to widen the pool of patients requiring regenerative bone grafting procedures.
Growing digital in-house workflow capability provides an additional significant source of demand, as 3-D printing technology increasingly empowers clinics to design custom grafts and surgical guides within hours, supporting broader diffusion of regenerative procedures into general dental practice settings. Rising global disposable income and dental tourism further support market growth as patients increasingly access premium implant and regenerative procedures across both domestic and international dental care markets. Continued clinical research validating long-term outcomes for synthetic and hybrid biomaterials further reinforces practitioner confidence, gradually expanding the pool of clinicians willing to specify newer material categories over historically dominant xenograft and allograft options.
Restraints: High Procedure Costs and Reimbursement Limitations
High cost of procedures persists as a real barrier, as the use of expensive xenografts and growth-factor enhanced synthetic materials keeps on costing a high amount per procedure which becomes hard for many patients in cost-sensitive markets to afford without proper insurance. The cost barrier is especially applicable to patients in developing countries because the cost of regenerative dentistry may go beyond what many households would be willing to pay for an elective or semi-elective dental procedure.
Another barrier comes from the restrictions in reimbursement as insurance coverages for bone grafting and regenerative dental procedures keep varying in different markets making patient access to the services and predictability of their demands difficult for both the practitioners and manufactures. The lack of insurance coverage of regenerative procedures that are not related to placement of the implants makes practitioners need to have in place mechanisms to finance and collect payments from their patients. Regenerative materials made from tissue also pose difficulty to manufacturers trying to register products in multi-markets because of cross-border regulation differences.
Opportunities: Growth Factor Innovation and Digital Workflow Integration
Continued innovation in growth factor-enhanced synthetic biomaterials offers a substantial opportunity, as manufacturers developing materials combining synthetic scaffolds with recombinant growth factors stand to capture meaningful new demand from clinicians seeking more predictable regeneration outcomes across complex defect cases. Manufacturers that can demonstrate validated, cost-competitive growth factor technology are well positioned to capture share as evidence supporting osteoinductive material performance continues to accumulate.
The continued integration of digital in-house workflow technology presents a further avenue for growth, as 3-D printing and digital treatment planning increasingly enable clinics to design custom grafts and surgical guides matched to individual patient anatomy. This technology pathway continues to open substantial new demand for manufacturers with established digital workflow integration capabilities serving both independent practices and larger DSO networks pursuing standardized, technology-enabled treatment protocols. Manufacturers that successfully bundle biomaterials with digital planning software and surgical guide services stand to capture disproportionate share as practices increasingly value integrated, single-vendor regenerative dentistry solutions over piecemeal procurement across multiple suppliers.
Recent Developments:
-
In November 2025, Geistlich introduced Geistlich Bio-Gide Forte at the American Academy of Periodontology annual meeting, expanding its collagen membrane portfolio for guided bone regeneration procedures.
-
In 2025, Straumann Group continued expanding its comprehensive implant and bone regeneration portfolio, supported by its subsidiary network spanning implants, abutments, guided surgery, and digital workflow solutions.
-
In 2025, Envista Holdings continued integrating bone graft and regenerative solutions across its Nobel Biocare and Implant Direct brands within its broader multi-tier implant strategy.
-
In 2025, RTI Surgical continued developing biologics-based bone graft solutions serving both dental and orthopedic regenerative applications across its global manufacturing network.
Dental Bone Grafts and Substitutes Market Key Players:
-
Straumann Group
-
Dentsply Sirona Inc.
-
Zimmer Biomet Holdings, Inc.
-
Geistlich Pharma AG
-
BioHorizons Implant Systems, Inc.
-
Osteogenics Biomedical, Inc.
-
Botiss Biomaterials GmbH
-
Sunstar Americas, Inc.
-
Hu-Friedy Mfg. Co., LLC
-
RTI Surgical Holdings, Inc.
-
DIO Corporation
-
Dentium Co., Ltd.
-
MegaGen Implant Co., Ltd.
-
Envista Holdings Corporation
-
Camlog Biotechnologies GmbH
-
Purgo Biologics
-
Collagen Matrix, Inc.
-
Salvin Dental Specialties, Inc.
-
ACE Surgical Supply Co., Inc.
-
Keystone Dental, Inc.
Dental Bone Grafts and Substitutes Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.95 Billion |
| Market Size by 2035 | USD 2.25 Billion |
| CAGR | CAGR of 9.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Xenograft, Allograft, Autograft, and Synthetic/Alloplast) • by Mechanism (Osteoconduction, Osteoinduction, Osteogenesis, and Osteopromotion) • by Application (Ridge Augmentation, Sinus Lift, Socket Preservation, Implant Bone Regeneration, and Periodontal Defect) • by End User (Hospitals, Dental Clinics, DSO/Group Practices, and Other End Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Straumann Group, Dentsply Sirona Inc., Zimmer Biomet Holdings, Inc., Geistlich Pharma AG, BioHorizons Implant Systems, Inc., Osteogenics Biomedical, Inc., Botiss Biomaterials GmbH, Sunstar Americas, Inc., Hu-Friedy Mfg. Co., LLC, RTI Surgical Holdings, Inc., DIO Corporation, Dentium Co., Ltd., MegaGen Implant Co., Ltd., Envista Holdings Corporation, Camlog Biotechnologies GmbH, Purgo Biologics, Collagen Matrix, Inc., Salvin Dental Specialties, Inc., ACE Surgical Supply Co., Inc., Keystone Dental, Inc. |

Frequently Asked Questions
Key players include Straumann Group, Dentsply Sirona, Zimmer Biomet, Geistlich Pharma, BioHorizons, Osteogenics Biomedical, Botiss Biomaterials, Sunstar Americas, Hu-Friedy, and RTI Surgical, among others.
Continued innovation in growth factor-enhanced synthetic biomaterials and the continued integration of digital in-house workflow technology represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by rising adoption of dental implants, combined with increasing incidence of periodontal disease leading to bone loss.
By Mechanism, Osteoconduction dominated the market with a 60.53% share in 2025, reflecting its role as the most widely used and best-understood regenerative approach in dental practice.
North America dominated the market with a 47.93% share in 2025, supported by the region's substantial dental implant procedure volume and dense concentration of leading manufacturers.
