
Diesel Particulate Filter Market Report Scope & Overview:
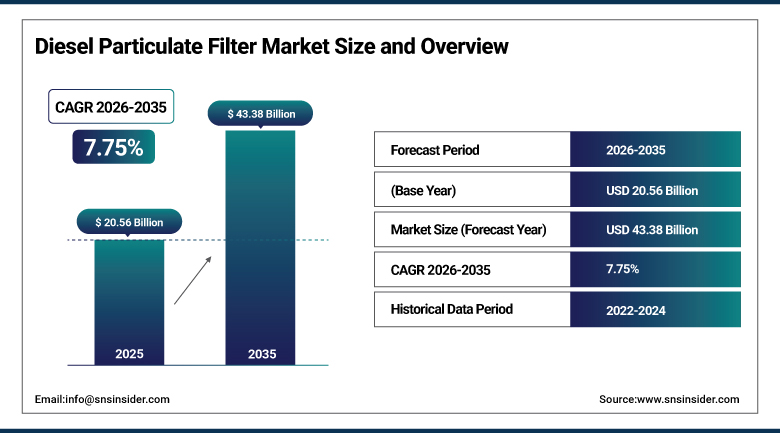
The Diesel Particulate Filter Market was valued at USD 20.56 Billion in 2025 and is expected to reach USD 43.38 Billion by 2035, growing at a CAGR of 7.75% from 2026-2035.
Diesel Particulate Filter Market is growing owing to the stringent emission standards that restrict particulate matter emissions from diesel fuelled engines in automobiles. The regulatory framework, such as Bharat VI of India and China VI, will further increase the requirements for the installation of filters in rapidly industrializing countries. The use of diesel particulate filters is an absolute necessity as it is responsible for collecting and combusting off the collected soot particles. It ensures that there is no release of particulate matter in the environment and that it meets the standards of emission. Growing diesel engine vehicle fleet in India, ASEAN region, and some parts of Africa will further add to the demand for the product despite the falling demand for passenger diesel vehicle due to the adoption of electric cars in matured markets.
In October 2024, Johnson Matthey, Eberspächer, Cummins, and BorgWarner launched integrated aftertreatment solutions combining diesel particulate filter, selective catalytic reduction, diesel oxidation catalyst, and advanced catalyst technologies with sensor-enabled diagnostics.
To Get more information Diesel Particulate Filter Market - Request Free Sample Report
Diesel Particulate Filter Market Trends
- Rapid diesel fleet expansion across India, ASEAN, and Africa driving sustained filter demand.
- Growing integration of diesel particulate filters with selective catalytic reduction and diesel oxidation catalysts.
- Continued adoption of silicon carbide substrates for superior thermal endurance during active regeneration.
- Increasing use of electric heaters to support passive regeneration during stop-start and hybrid diesel duty cycles.
- Rising regulatory convergence enabling OEMs to standardize aftertreatment architecture across multiple regions.
U.S. Diesel Particulate Filter Market Outlook
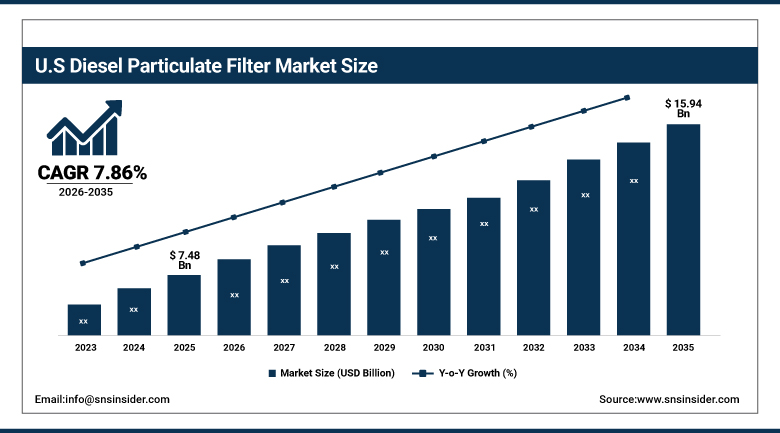
The U.S. Diesel Particulate Filter Market was valued at USD 7.48 Billion in 2025 and is expected to remain at approximately USD 15.94 Billion by 2035, reflecting a flat CAGR of 7.86% from 2026-2035.
The trend of growth in the US Diesel Particulate Filter Market can be attributed to the balance between lower demands from passenger vehicles due to continued adoption of gasoline and electric engines by automobile companies and continuing demand for heavy commercial and off-highway vehicles that still need efficient aftertreatment systems. There is also domestic demand from the presence of major emissions control providers in the region and continuous enforcement of particulate emissions standards by regulators in commercial and off-road diesel engines. The Tier 5 off-road engine standards proposed by the California Air Resources Board, which will progressively lower particulate standards from 2029 through 2034, will ensure continued demand despite the slow growth of the domestic market compared to international markets.
In February 2025, Tenneco received a strategic investment from Apollo Fund X to fast-track clean air technologies and electrification pathways. The investment reflects continued domestic capital allocation toward emissions control innovation as leading suppliers navigate the transition between sustained diesel aftertreatment demand and longer-term vehicle electrification trends.
Diesel Particulate Filter Market Segment Analysis
- By Type, the Regenerating segment dominated the Diesel Particulate Filter Market with approximately 62.40% share in 2025, and is also the fastest growing with a CAGR of approximately 8.90%.
- By Material, the Cordierite segment dominated the Diesel Particulate Filter Market with approximately 45.56% share in 2025, while the Silicon Carbide segment is the fastest growing with a CAGR of approximately 8.60%.
- By Vehicle Type, the Passenger Cars segment dominated the Diesel Particulate Filter Market with approximately 37.78% share in 2025, while the Heavy Commercial Vehicles segment is the fastest growing with a CAGR of approximately 8.90%.
- By Sales Channel, the OEM segment dominated the Diesel Particulate Filter Market with approximately 74.50% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 8.20%.
By Type, Regenerating dominates and grows fastest
Regenerating filters continue to make up the largest and fastest-growing category segment in the Diesel Particulate Filter market due to their self-cleaning nature when they operate. The regenerating filters segment continues to gain traction from the rising use of such filters in commercial trucks and buses in cities, whereby the process of thermal regeneration works well because of the high temperatures generated.
Additionally, the segment concentrates on continuous efforts by manufacturers to develop thermal resistant coatings as well as effective regeneration technology in order to continue leading other segments such as the passive filters due to tightening emission regulations. With the growing focus on durability and longer service periods from OEMs and engine manufactures, this segment will be able to retain its leadership.
By Material, Cordierite dominates and Silicon Carbide grows fastest
Cordierite substrates remain the dominant material segment within the Diesel Particulate Filter Market, reflecting their established manufacturing base, cost efficiency, and proven thermal and mechanical properties suited to conventional diesel exhaust temperature ranges. This segment benefits from decades of accumulated ceramic substrate engineering expertise that continues to support broad specification across mainstream passenger and light commercial vehicle applications.
Silicon Carbide substrates are emerging as the fastest-growing material segment, driven by their superior thermal endurance above 1,000 degrees Celsius, which minimizes cracking during active regeneration cycles in demanding heavy-duty and high-temperature applications. This segment focuses on materials capable of withstanding repeated thermal stress without structural degradation, positioning silicon carbide substrates to capture growing demand as heavy commercial vehicle and off-highway applications continue to require more robust filtration technology.
By Vehicle Type, Passenger Cars dominates and Heavy Commercial Vehicles grows fastest
Passenger Cars account for the largest share among the vehicle types in the Diesel Particulate Filter Market due to the historical dominance of diesel passenger vehicles in the automotive industry in major markets around the world, especially in Europe and certain Asian regions. Passenger Car filters benefit from ongoing diesel passenger car manufacturing in places where diesels enjoy cost and efficiency advantages over gas and electric vehicles.
The Heavy Commercial Vehicles market is expected to witness the fastest growth among the various vehicle type segments, due to increasing numbers of diesel fleet deployments in India, ASEAN countries, and Africa, along with stringent regulations governing commercial trucking fleets in advanced economies.
By Sales Channel, OEM dominates and Aftermarket grows fastest
Sales through OEMs continue to dominate the market for Diesel Particulate Filters because of the incorporation of diesel particulate filters directly into the aftertreatment system of the exhaust in new cars. The growth and stability of sales in the OEM segment is supported by long-term supply contracts between the manufacturers of filters and those of vehicles and engines that ensure regular and high demand in connection with the production of diesel cars worldwide.
The Aftermarket segment is becoming the leading growth segment because of the increased demand for replacement of the filter due to aging of diesel vehicles and equipment after the end of the warranty period. This segment requires increasing the network of distribution and diagnostics.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
52.60% |
|
North America |
United States |
85.50% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
44.90% |
|
Middle East & Africa |
United Arab Emirates |
28.60% |
Asia Pacific Diesel Particulate Filter Market Insights
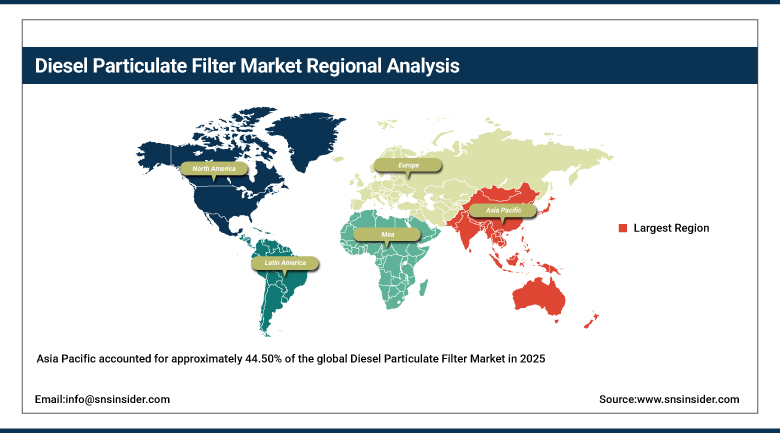
Asia Pacific accounted for approximately 44.50% of the global Diesel Particulate Filter Market in 2025 and is also projected to expand at the fastest CAGR of approximately 8.50% during the 2026-2035 forecast period, driven by expanding diesel fleets under Bharat VI and China VI emission rules. China represents the largest single contributor within the region, supported by its extensive commercial vehicle production base and continued enforcement of stringent diesel emission standards.
India contributes substantial additional regional demand, supported by rapid diesel commercial vehicle fleet expansion and continued enforcement of Bharat VI emission standards across the country's large trucking sector. Japan and South Korea's established automotive component manufacturing expertise further reinforces the region's overall filtration technology supply chain depth, supporting Asia Pacific's position as both the largest and fastest-growing global market for diesel particulate filters.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Diesel Particulate Filter Market Insights
North America represents a significant regional market for diesel particulate filters, anchored by the United States' large heavy commercial vehicle and off-highway diesel fleet requiring continued exhaust aftertreatment equipment. The United States accounts for the substantial majority of regional demand, reflecting both its commercial trucking fleet scale and its concentration of leading emissions control suppliers.
Canada and Mexico contribute additional regional volume through cross-border commercial vehicle fleet operations. Continued regulatory enforcement of particulate emission standards for commercial and off-road diesel engines, including forthcoming stricter off-road engine standards, further supports steady regional demand for advanced diesel particulate filter technology.
Europe Diesel Particulate Filter Market Insights
Europe is a large regional market for diesel particulate filters due to the extensive auto industry manufacturing operations in Germany along with a high number of premium car manufacturers and diesel particulate filters in this region. The presence of Germany in the European market is also attributed to the extensive use of diesel passenger cars in the country along with major emission control systems manufacturers in Germany.
France and the UK also provide some regional demand, with established automotive manufacturing industries and regulation of emissions by the European Union. With continuous emphasis on particulate emissions by the European Union, especially through Euro 7 regulations, there will be consistent regional demand for diesel particulate filters.
MEA & Latin America Diesel Particulate Filter Market Insights
Latin America's Diesel Particulate Filter Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic commercial vehicle assembly base and its role as a regional export hub for automakers operating in the region. Gradual tightening of regional emission standards continues to support steady regional demand growth.
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where rising commercial vehicle imports and growing industrial diesel equipment demand are gradually increasing component demand. South Africa continues to anchor filter-related demand on the African continent, supported by its comparatively more developed commercial vehicle and industrial equipment base.
Market Dynamics
Growth Drivers: Tightening Emission Standards and Diesel Fleet Expansion
Increasing emissions regulation regarding particulate matter emissions from diesel engines is one of the key factors driving the growth in the Diesel Particulate Filter Market owing to increasing regulation of emission standards like Bharat VI and China VI, leading to a growing number of diesel fleet requirements in industrializing countries. The rising demand for diesel fleets in countries like India, ASEAN countries, and some African countries has been driving the demand, despite the stagnating demand from passenger diesel vehicles in developed countries.
Another important factor driving the growth in the market is increased integration of diesel particulate filters with the selective catalytic reduction systems and diesel oxidation catalyst systems. Increasing demand from the heavy commercial vehicle fleet and off-road diesel fleets despite decreasing demand from passenger diesel vehicles in developed countries has been contributing to the growth in the market.
Restraints: Vehicle Electrification and Passenger Diesel Decline
The global shift away from diesel-powered passenger vehicles toward electrification and alternative fuels represents a significant restraint on the Diesel Particulate Filter Market, particularly in mature markets where passenger diesel vehicle production continues to decline in favor of gasoline and battery electric alternatives. This dynamic requires filter manufacturers to increasingly rely on commercial and off-highway diesel applications to offset declining passenger vehicle demand in markets pursuing rapid electrification.
Hybrid diesel platforms idling under 250 degrees Celsius jeopardize passive filter oxidation, requiring manufacturers to integrate electric heaters and high-activity catalyst layers to maintain regeneration performance during electric-assist operating phases. Continued raw material cost volatility for specialized ceramic substrate materials adds further uncertainty to long-term manufacturing cost planning across the industry.
Opportunities: Emerging Market Fleet Growth and Integrated Aftertreatment Systems
Growing and quick expansion of diesel fleet in India, ASEAN countries and Africa provides great opportunity for Diesel Particulate Filter Market due to the implementation of more stringent emission norms requiring advanced aftertreatment technologies. Companies capable of offering highly cost-effective and reliable filtration devices appropriate for local conditions are likely to gain market share from growing numbers of fleets.
Growing demand for comprehensive and multifunctional aftertreatment systems featuring diesel particulate filters and combined with selective catalytic reduction systems and diesel oxidation catalysts represents a long-term opportunity for companies to increase value generated by each vehicle platform. Growing trend towards regulatory convergence and consequently increasing platform standardization across regions provide great opportunity for companies with well-developed integrated systems design to take disproportionate advantage of this trend.
Recent Developments:
- 2024: Continental expanded its aftertreatment manufacturing operations with new high-volume production lines featuring integrated selective catalytic reduction, diesel particulate filter, and diesel oxidation catalyst modules with electronic control unit optimization.
- 2025: FORVIA (Faurecia) expanded its integrated exhaust module offerings targeting Euro 7-compliant passenger and light commercial vehicles, reflecting continued investment in regulation-ready aftertreatment architecture.
Diesel Particulate Filter Market Key Players are:
- Tenneco Inc.
- Faurecia SE (FORVIA)
- Johnson Matthey plc
- Continental AG
- Denso Corporation
- Eberspächer Gruppe GmbH & Co. KG
- Friedrich Boysen GmbH & Co. KG
- BOSAL International N.V.
- Corning Incorporated
- CDTi Advanced Materials, Inc.
- Cummins Inc.
- Donaldson Company, Inc.
- NGK Insulators, Ltd.
- BorgWarner Inc.
- Freudenberg Filtration Technologies
- Robert Bosch GmbH
- Mann+Hummel Holding GmbH
- MAHLE GmbH
- Umicore N.V.
- Ibiden Co., Ltd.
Diesel Particulate Filter Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 20.56 Billion |
| Market Size by 2035 | USD 43.38 Billion |
| CAGR | CAGR of 7.75% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Regenerating and Disposable) • By Material (Cordierite, Silicon Carbide, Ceramic Fiber, Other Substrate) • By Vehicle Type (Passenger Cars, Light Commercial Vehicles, and Heavy Commercial Vehicles) • By Sales Channel (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tenneco Inc.; Faurecia SE (FORVIA); Johnson Matthey plc; Continental AG; Denso Corporation; Eberspächer Gruppe GmbH & Co. KG; Friedrich Boysen GmbH & Co. KG; BOSAL International N.V.; Corning Incorporated; CDTi Advanced Materials, Inc.; Cummins Inc.; Donaldson Company, Inc.; NGK Insulators, Ltd.; BorgWarner Inc.; Freudenberg Filtration Technologies; Robert Bosch GmbH; Mann+Hummel Holding GmbH; MAHLE GmbH; Umicore N.V.; Ibiden Co., Ltd |
Frequently Asked Questions
Leading companies in the Diesel Particulate Filter Market include Tenneco, Faurecia (FORVIA), Johnson Matthey, Continental, and Denso, among others.
Key opportunities include continued rapid diesel fleet expansion across India, ASEAN, and Africa, and rising demand for integrated, multi-function aftertreatment architectures combining filtration with catalytic systems.
Tightening emissions regulations governing particulate matter output from diesel-powered vehicles, combined with rapid diesel fleet expansion across emerging economies, is the major factor driving market growth.
The Passenger Cars segment dominated the Diesel Particulate Filter Market with approximately 37.78% share in 2025.
Asia Pacific dominated the Diesel Particulate Filter Market in 2025 with approximately 44.50% share, driven by expanding diesel fleets under Bharat VI and China VI emission rules, led by China.
