
Digital Risk Protection Platform Market Report Scope & Overview:
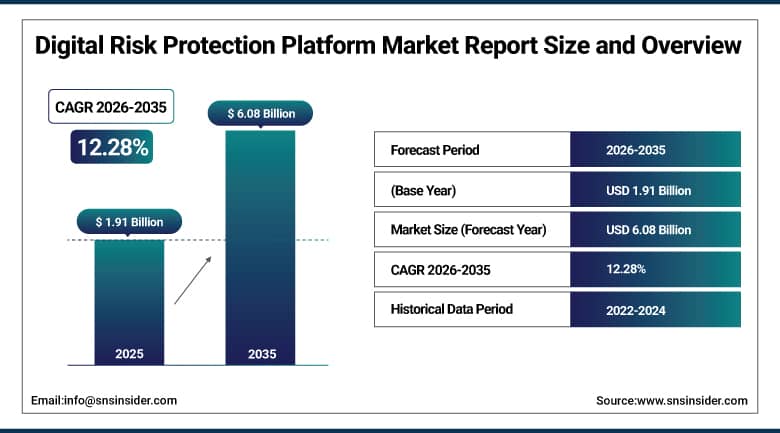
The Digital Risk Protection Platform Market was valued at USD 1.91 Billion in 2025 and is expected to reach USD 6.08 Billion by 2035, growing at a CAGR of 12.28% from 2026-2035.
The Digital Risk Protection Platform Market is witnessing a growth owing to the rising number of cyberattacks, advanced digital attacks, and online presence. Companies are using preventive approaches to detect external threats, secure their digital properties, and prevent impersonation and risk associated with their brands, domains, and data. The increase in cloud-based systems and remote workers has expanded the attack surface area, thereby, making it necessary to keep track of their digital risks continuously. Furthermore, strict laws related to data privacy and cybersecurity have compelled companies to implement robust risk management policies. Adoption of artificial intelligence and machine learning in detecting threats and automating responses and prioritization of risks is increasing.
In 2024, Mastercard completed its acquisition of Recorded Future for approximately USD 2.65 billion, a strategic move bringing advanced threat intelligence capabilities into Mastercard's broader payment security and fraud prevention operations. The acquisition reflects continued strategic interest from outside the traditional cybersecurity industry in digital risk and threat intelligence platform capabilities.
To Get More Information On Digital Risk Protection Platform Market - Request Free Sample Report
Digital Risk Protection Platform Market Trends
-
Growing integration of artificial intelligence and machine learning into automated threat detection and response.
-
Rising native support for zero-trust policies automatically enforcing permission and authentication controls.
-
Expanding consolidation of standalone digital risk protection vendors into broader security operations platforms.
-
Increasing adoption of managed takedown services reducing reliance on in-house analyst capacity.
-
Rising demand for coverage spanning physical security, reputation, legal, and geopolitical risk domains.
U.S. Digital Risk Protection Platform Market Overview
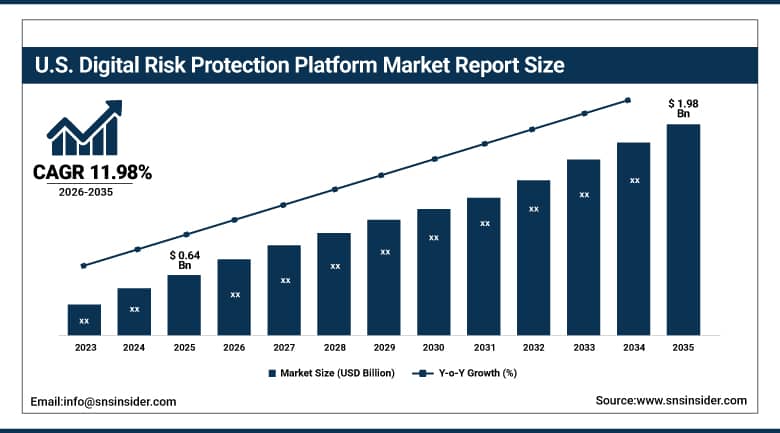
The U.S. Digital Risk Protection Platform Market was valued at USD 0.64 Billion in 2025 and is expected to reach USD 1.98 Billion by 2035, growing at a CAGR of 11.98% from 2026-2035.
Domestic demand continues to be underpinned by mature cybersecurity infrastructure, rapid corporate adoption, and a vibrant vendor landscape spanning both established cybersecurity leaders and specialized digital risk protection providers. Leading vendors continue integrating digital risk protection capabilities directly into broader security operations platforms, including automated response playbooks and managed takedown services, while continued private equity and strategic acquisition activity keeps reshaping the competitive landscape. Growing regulatory mandates, including CCPA and HIPAA compliance requirements, further support domestic market expansion, positioning U.S. enterprises to access an increasingly consolidated range of digital risk protection capabilities nationwide.
In May 2024, Haveli Investments completed its acquisition of ZeroFox for approximately USD 350 million, taking the company private less than two years after its public listing via a special purpose acquisition company. The transaction reflects the broader wave of private equity consolidation reshaping ownership structures across the domestic digital risk protection vendor landscape.
Digital Risk Protection Platform Market Segment Analysis
-
By Component, Solutions segment dominated the Digital Risk Protection Platform Market in 2025 with 69% share; Services segment is the fastest growing segment.
-
By Deployment Mode, Cloud-Based segment dominated the Digital Risk Protection Platform Market in 2025 with 64% share; Cloud-Based segment is also the fastest growing segment.
-
By Organization Size, Large Enterprises segment dominated the Digital Risk Protection Platform Market in 2025 with 57% share; Small & Medium-Sized Enterprises segment is the fastest growing segment.
-
By End-Use Industry, BFSI segment dominated the Digital Risk Protection Platform Market in 2025 with 31% share; IT & ITeS segment is the fastest growing segment.
By Component, Solutions Dominate Digital Risk Protection Platform Market; Services to Register Fastest Growt
Solutions dominate the Digital Risk Protection Platform Market since businesses need integrated solutions that provide continuous monitoring, detection, and mitigation of external digital threats. Solutions include the integration of threat intelligence, attack surface management, brand protection, phishing detection, and social media risk detection in the same platform. Large enterprises are particularly interested in solutions since they have very complex digital environments, a large online presence, and increased vulnerability to impersonation and credential-based attacks. Rising cybersecurity spending and increasing automation in risk detection are adding to the success of this segment.
Services are expected to register the fastest growth driven by the rising number of organizations seeking the services of experts to improve their digital risk protection capabilities without having to hire cybersecurity professionals. Managed services, consulting, implementation, integration, and continuous monitoring allow businesses to manage changing threats, configure platforms effectively, and react quickly to changing digital risks. The scarcity of qualified cybersecurity professionals, high complexity of external attack surfaces, and widespread use of digital risk protection services by companies without sufficient internal capabilities are promoting this trend.
By Deployment Mode, Cloud-Based Dominates Digital Risk Protection Platform Market; Cloud-Based to Register Fastest Growth
The Digital Risk Protection Platform Market is dominated by cloud-based deployment since organizations can monitor the digital assets, threats, domains, social media channels, and other activities using cloud-based and accessible infrastructure. Cloud-based deployment allows organizations to reduce hardware deployment while offering quick deployment, centralized access, automatic updates, and scalable resources. Organizations are preferring cloud-based cybersecurity platforms as their digital ecosystem continues to grow in distributed environments.
Cloud-based deployment will continue to be the fastest-growing segment since organizations are adopting cloud computing at a much faster pace and need cybersecurity platforms that can protect their distributed digital environment. These platforms allow organizations to scale up or down based on their needs while allowing quick deployment within different geographical locations. The ability to constantly update software and integrate it with the cloud security ecosystem increases its adaptability to any threat. Remote operations, growing digital footprint, and flexible cybersecurity expenditure models will drive the shift to cloud-based digital risk protection platforms.
By Organization Size, Large Enterprises Dominate Digital Risk Protection Platform Market; Small & Medium-Sized Enterprises to Register Fastest Growth
Large enterprises dominate the Digital Risk Protection Platform Market due to the fact that they have significant digital footprints that include sites, domains, social media, applications, users, and third-party ecosystems. The higher exposure of these organizations to various types of threats including impersonation, phishing, brand abuse, data leaks, etc. makes the need for constant digital risk protection more acute. Large companies also have more security budgets and dedicated teams which make them capable of implementing more sophisticated protection platforms. Regulations, reputational issues, and technical complexity contribute to the demand in large organizations.
Small & medium-sized enterprises are expected to register the fastest growth due to the fact that cybercriminals will target organizations having smaller security teams and lower level of protection. The rising recognition of digital risks forces SMEs to use automated systems that would detect various external threats such as phishing, impersonation, leaks of credentials, fraudulent domains, etc. without spending much money. Cloud-based subscription services are making the process more affordable. The digitalization and increasing number of online transactions and communications also drives the demand in SMEs.
By End-Use Industry, BFSI Dominates Digital Risk Protection Platform Market; IT & ITeS to Register Fastest Growth
BFSI dominates the Digital Risk Protection Platform Market since BFSI companies handle sensitive information pertaining to their customers, finances, digital identity, and transactions. This makes BFSI companies susceptible to phishing, impersonation, fraud, and brand abuse. Financial institutions have robust online and mobile presence which increases the susceptibility to threats across websites, social media, applications, and third-party channels. Stringent regulatory framework and importance of gaining customer trust drives the external threat monitoring among BFSI companies. Increase in the number of users who conduct digital banking transactions also demands more digital risk protection.
IT & ITeS is expected to register the fastest growth since technology companies have complex digital ecosystems with extensive cloud infrastructures, applications, online platforms, intellectual property and employee identities. Dependence of IT & ITeS companies on digital channels increases their vulnerability towards phishing attacks, impersonation, credential theft, domain abuse, and data leakage. Adoption of cloud, increase in the remote workforce, and increased usage of third-party technologies have been increasing external attack surface of IT & ITeS companies.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|
North America |
United States |
83.60% |
|
Europe |
Germany |
30.60% |
|
Asia Pacific |
China |
41.60% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
United Arab Emirates |
32.60% |
North America Digital Risk Protection Platform Market Insights
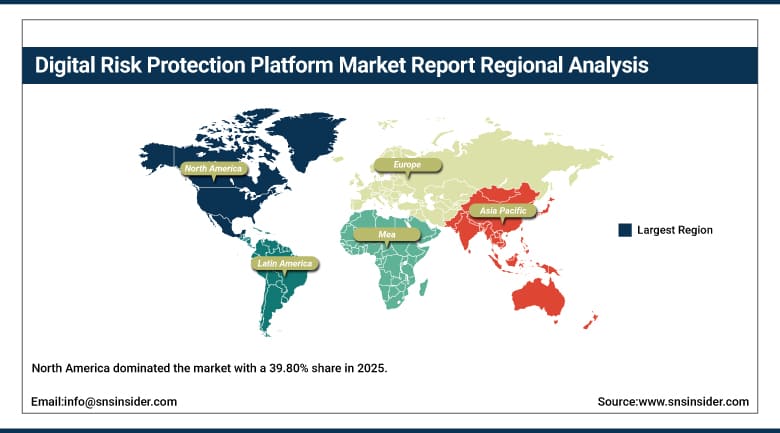
North America dominated the market with a 39.80% share in 2025. Mature cybersecurity infrastructure, rapid corporate adoption, and a vibrant vendor landscape continue to anchor this leadership position across financial services, government, and healthcare deployment contexts. The United States shapes regional demand through its concentration of leading cybersecurity vendors and strict regulatory mandates, including CCPA and HIPAA, that continue to drive enterprise adoption.
Canada contributes additional regional demand through its participation in North American cybersecurity infrastructure investment. Continued domestic consolidation among leading vendors is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building out cybersecurity infrastructure from a considerably smaller existing base.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Digital Risk Protection Platform Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 20.40% during 2026-2035, supported by rapid digitization, escalating cyber threats, and increasing corporate focus on cybersecurity measures across the region. China continues to anchor regional demand as domestic enterprises expand digital risk monitoring capability across both established financial centers and rapidly developing technology hubs.
India's expanding IT and financial services sectors continue to add meaningful regional growth as domestic demand for external threat monitoring accelerates. Japan and South Korea contribute further depth through established, technically advanced enterprise cybersecurity sectors, positioning the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Digital Risk Protection Platform Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established cybersecurity vendors and continued advancement in threat intelligence technology developed for financial services and government applications. Germany's substantial financial and industrial base anchors regional demand, supported by strong enterprise adoption of digital risk monitoring across the country and neighbouring markets, while the United Kingdom continues to record particularly rapid country-level growth within the region.
France and other major European markets contribute consistent demand as regional enterprises continue extending advanced threat intelligence technology into routine security operations practice. Continued European regulatory emphasis on data privacy supports steady regional demand for digital risk protection platforms.
MEA & Latin America Digital Risk Protection Platform Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand on the strength of its growing financial services and technology sector. Gradual growth in domestic cybersecurity investment continues to support steady regional market development.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding financial services and government digitization investment is increasingly driving demand for external threat monitoring capability. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed financial services infrastructure.
Market Dynamics
Growth Drivers: Escalating Cyber Threats and Cloud Attack Surface Expansion
Escalating cyber threats and an increased focus on cybersecurity measures represent the primary growth driver, as swift digitization across industries continues to expand the external attack surface organizations must monitor and defend. This dynamic is reinforced by stringent data privacy regulations and the increasing attack surface of cloud providers, which continue to drive enterprise investment in continuous external threat monitoring capability.
Rising native support for zero-trust security policies provides an additional significant source of demand, as digital risk protection technologies increasingly automatically enforce permission, authentication, and micro-segmentation controls across social media platforms, mobile apps, and brand domains. Growing corporate recognition of digital risk protection as a top strategic security investment further supports market growth across enterprise organizations worldwide.
Restraints: Vendor Consolidation Uncertainty and In-House Expertise Gaps
Vendor consolidation uncertainty remains a genuine restraint on market growth, as ongoing private equity and strategic acquisition activity continues to create ambiguity around product roadmaps and long-term platform independence for enterprise customers evaluating vendor relationships. This uncertainty particularly affects customers of recently acquired platforms, where renewal decisions increasingly hinge on whether acquiring owners will continue investing in product development or prioritize cost optimization.
Lack of in-house cyber expertise presents a further restraint, as many organizations continue to struggle to effectively operationalize raw threat intelligence feeds without dedicated analyst capacity. This requires vendors to sustain substantial ongoing investment in managed service capability and customer support infrastructure to help customers translate digital risk data into actionable protective measures.
Opportunities: AI-Driven Automation and Expanded Risk Domain Coverage
Continued integration of artificial intelligence and machine learning into digital risk protection platforms offers a substantial opportunity, as vendors developing increasingly automated threat detection and predictive intelligence capability stand to capture meaningful new demand from enterprises seeking to reduce manual analyst workload. Vendors increasingly view AI-driven automation not as a novelty feature but as a genuine competitive necessity for scaling threat monitoring across expanding digital footprints.
The continued expansion of risk domain coverage beyond conventional social media monitoring and brand protection presents a further avenue for growth, as platforms increasingly classify physical security, reputation, legal, environmental, societal, and geopolitical risk domains. This broader coverage pathway continues to open substantial new demand for vendors capable of addressing a wider threat surface than the original digital risk protection definition allowed.
Recent Developments:
-
As of June 2025, ReliaQuest built digital risk protection capability directly into its GreyMatter security operations platform user interface, including central alert triage, automated response playbooks, and managed takedown services.
-
In 2024, Check Point Software Technologies acquired Cyberint, an Israeli threat intelligence and external attack surface management vendor, expanding its digital risk protection portfolio.
-
During 2025 and into 2026, Securitas advanced its acquisition of Liferaft, a Canadian open-source intelligence platform, integrating the technology into its broader physical security services portfolio.
-
In 2025, ZeroFox continued expanding its artificial intelligence capabilities with the launch of ZeroFox Sentinel, an AI-powered predictive threat intelligence engine.
Digital Risk Protection Platform Market Key Players
-
ZeroFox Holdings, Inc.
-
ReliaQuest (Digital Shadows)
-
Trellix
-
Proofpoint, Inc.
-
RSA Security LLC
-
Kaspersky Lab
-
CrowdStrike Holdings, Inc.
-
Rapid7, Inc.
-
CybelAngel
-
Recorded Future, Inc.
-
Group-IB
-
Cyberint (Check Point Software)
-
Bolster, Inc.
-
BrandShield Ltd.
-
Mimecast Limited
-
Palo Alto Networks, Inc.
-
IBM Corporation
-
Cisco Systems, Inc.
-
Trend Micro Incorporated
-
Constella Intelligence
Digital Risk Protection Platform Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.91 Billion |
| Market Size by 2035 | USD 6.08 Billion |
| CAGR | CAGR of 12.28% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions, Services) • By Deployment Mode (Cloud-Based, On-Premises) • By Organization Size (Large Enterprises, Small & Medium-Sized Enterprises) • By End-Use Industry (BFSI, Government, IT & ITeS, Healthcare, Retail & E-Commerce, Media & Entertainment, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ZeroFox Holdings, Inc., ReliaQuest (Digital Shadows), Trellix, Proofpoint, Inc., RSA Security LLC, Kaspersky Lab, CrowdStrike Holdings, Inc., Rapid7, Inc., CybelAngel, Recorded Future, Inc., Group-IB, Cyberint (Check Point Software), Bolster, Inc., BrandShield Ltd., Mimecast Limited, Palo Alto Networks, Inc., IBM Corporation, Cisco Systems, Inc., Trend Micro Incorporated, Constella Intelligence |
Frequently Asked Questions
Key players include ZeroFox, ReliaQuest, Trellix, Proofpoint, RSA Security, Kaspersky, CrowdStrike, Rapid7, CybelAngel, and Recorded Future, among others.
AI and machine learning integration in threat detection, alongside broader risk-domain coverage beyond traditional brand protection, creates significant growth opportunities.
Escalating cyber threats, stronger cybersecurity priorities, stringent data privacy regulations, and expanding cloud attack surfaces are accelerating market growth.
By Organization Size, Large Enterprises dominated the market in 2025, reflecting complex digital footprints and stringent compliance needs.
North America dominated the market with a 39.80% share in 2025, supported by mature cybersecurity infrastructure and rapid corporate adoption, led by the United States.
