
Direct-to-Consumer Genetic Testing Market Report Scope & Overview:
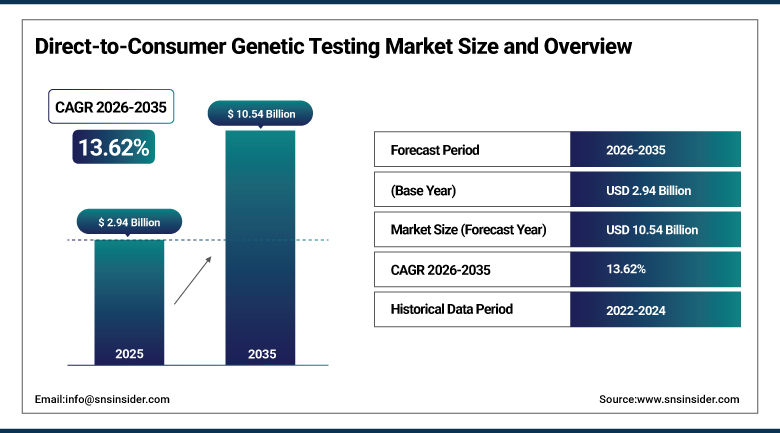
The Direct-to-Consumer (DTC) Genetic Testing Market was valued at USD 2.94 Billion in 2025 and is expected to reach USD 10.54 Billion by 2035, growing at a CAGR of 13.62% from 2026-2035.
The Direct-to-Consumer Genetic Testing Market covers genetic tests that people order for themselves, usually online, by sending a saliva or blood sample to a laboratory without a doctor's involvement. Results cover ancestry, family relationships, inherited health risks, carrier status, drug response, nutrition and fitness. Growth is supported by falling sequencing costs, curiosity about health and heritage, and wider online ordering, while data privacy, regulation and the reliability of results shape consumer trust and company strategies.
⮞In July, 2025, TTAM Research Institute, a nonprofit public benefit corporation founded and led by 23andMe co-founder Anne Wojcicki, completed the acquisition of 23andMe's assets under Section 363 of the U.S. Bankruptcy Code. The assets include the Personal Genome Service and Research Services business lines, and 23andMe continues to offer DNA testing under TTAM.
To Get more information Direct-to-Consumer Genetic Testing Market - Request Free Sample Report
Direct-to-Consumer Genetic Testing Market Trends
- Shift from ancestry reports to health risk, pharmacogenomics and wellness insights
- Falling cost of whole genome sequencing and SNP chips
- Growth of genetic counseling and clinician access bundled with consumer tests
- Greater focus on data privacy, consent and ownership of genetic information
- Partnerships between laboratories, pharmaceutical firms and consumer genetics brands
- Introduction of international standards for consumer genetic data analysis
U.S. Direct-to-Consumer Genetic Testing Market Outlook
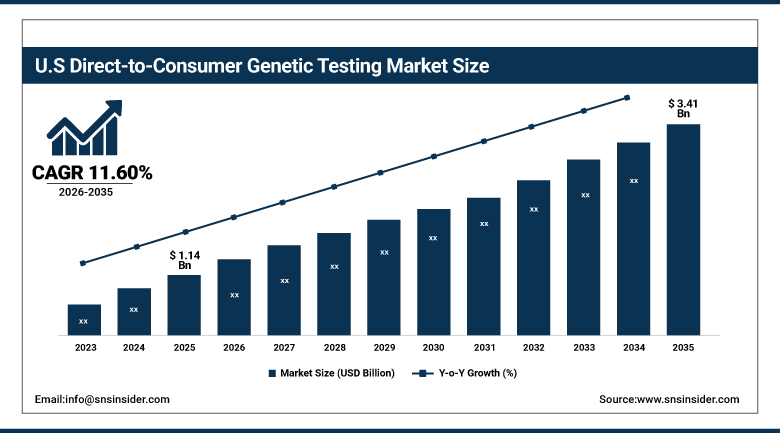
The U.S. Direct-to-Consumer Genetic Testing Market was valued at USD 1.14 Billion in 2025 and is expected to reach USD 3.41 Billion by 2035, growing at a CAGR of 11.60% from 2026-2035.
The U.S. Direct-to-Consumer Genetic Testing Market is the largest national market, supported by early adoption of ancestry kits, strong online retail, large laboratory networks and high interest in preventive health. The Food and Drug Administration clears some health risk reports, and state privacy laws are tightening rules on genetic data. Growth is moderated by privacy concerns after high-profile company failures, test fatigue among earlier buyers and limited insurance coverage.
⮞In July, 2026, Labcorp announced the Marker by Labcorp Genetic Health Panel, available from August 3, 2026 through Labcorp OnDemand. The blood-based test analyzes 163 genes linked to more than 100 hereditary conditions, includes genetic counselors and returns results in the MyLabcorp app.
Direct-to-Consumer Genetic Testing Market Segment Analysis
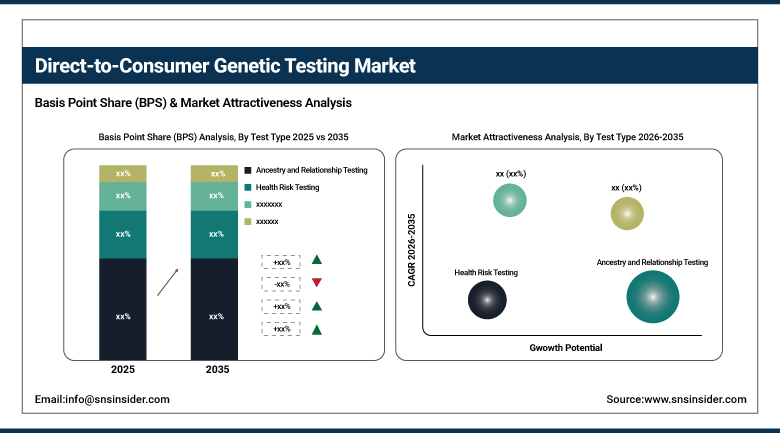
- By Test Type, ancestry and relationship testing segment dominated the Direct-to-Consumer Genetic Testing Market in 2025 with an estimated 36.00% share; nutrigenomics and wellness segment is the fastest-growing segment, with an estimated CAGR of 18.20% during 2026–2035.
- By Technology, SNP chips segment dominated the Direct-to-Consumer Genetic Testing Market in 2025 with an estimated 48.00% share; whole genome sequencing segment is the fastest-growing segment, with an estimated CAGR of 19.50% during 2026–2035.
- By Sample Type, saliva segment dominated the Direct-to-Consumer Genetic Testing Market in 2025 with an estimated 78.00% share; blood segment is the fastest-growing segment, with an estimated CAGR of 14.80% during 2026–2035.
- By Distribution Channel, online platforms segment dominated the Direct-to-Consumer Genetic Testing Market in 2025 with an estimated 74.00% share; over-the-counter segment is the fastest-growing segment, with an estimated CAGR of 15.00% during 2026–2035.
By Test Type, Ancestry and Relationship Testing Dominates DTC Genetic Testing Market; Nutrigenomics and Wellness to Register Fastest Growth.
Ancestry and relationship testing dominates the Direct-to-Consumer Genetic Testing Market because it was the first widely marketed consumer use and still attracts the largest number of buyers. Kits are inexpensive, easy to give as gifts and supported by large family tree databases. Matching relatives and tracing origins keeps people engaged, and users often buy additional tests for family members. Genealogy societies, family reunions and holiday gifting events help keep new customers arriving. Many buyers return to upgrade, download raw data or add family members, which adds value for companies.
Nutrigenomics and wellness is projected to register the fastest growth as consumers look for guidance on diet, fitness, sleep and weight management. Companies pair genetic results with apps, coaching and supplements, and interest in personalized health is rising. Connections to wearable data and new tests linked to weight-loss drug response are broadening the offer. Reports that now link to meal plans, exercise advice and supplement suggestions encourage repeated app use, and partnerships with fitness and nutrition brands are expanding the audience beyond first-time buyers.
By Technology, SNP Chips Dominates DTC Genetic Testing Market; Whole Genome Sequencing to Register Fastest Growth.
SNP chips dominate the Direct-to-Consumer Genetic Testing Market because they read hundreds of thousands of common variants at a low cost per sample, which suits ancestry and basic health reports. Laboratories have large chip-processing lines and well-tested analysis tools. Low prices allow companies to sell kits at attractive consumer prices and still earn margins on volume. Companies have also invested in imputation methods that fill in missing variants, which lets chip data support many health and trait reports. This efficiency keeps chip-based kits priced well below sequencing. Chips also offer reliable genotype calls, which gives companies consistent quality control.
Whole genome sequencing is projected to register the fastest growth as sequencing prices fall and consumers seek more complete results, including rare variants. New platforms from sequencing makers are lowering costs, and companies are adding genome reports for health risk and drug response. Data from whole genomes also supports research partnerships and longer-term subscription services. Cloud analysis and artificial intelligence tools are making it easier to interpret large genomes quickly, and subscription models let customers receive new findings as research advances without paying for a new test.
By Sample Type, Saliva Dominates DTC Genetic Testing Market; Blood to Register Fastest Growth.
Saliva dominates the Direct-to-Consumer Genetic Testing Market because collection is painless, can be done at home and requires no trained staff. Kits can be mailed in a simple tube, which keeps costs low and returns high. DNA yield from saliva is adequate for chips and most sequencing methods, making it the standard for ancestry and wellness tests. Simple instructions, stabilizing liquids that protect the sample during mail transit and low shipping cost further support the dominance of saliva kits for large consumer volumes. Households with several members often order kits together, which spreads shipping and marketing costs.
Blood is projected to register the fastest growth as laboratories and clinical brands launch consumer panels that need high-quality DNA and pair a draw at a patient service center with genetic counseling. Health-focused tests for hereditary conditions and drug response favor blood because it supports more reliable clinical-grade results, and laboratories already operate large collection networks. Regulators and physicians also trust blood-based results more readily, which helps brands that want to position their products as clinical-grade while still selling directly to consumers online.
By Distribution Channel, Online Platforms Dominates DTC Genetic Testing Market; Over-the-Counter to Register Fastest Growth.
Online platforms dominate the Direct-to-Consumer Genetic Testing Market because most buyers order through company websites and large e-commerce marketplaces, then receive kits by mail and view results in an app. Online sales give companies direct contact with customers, richer data and control over pricing. Promotions during gift seasons produce large spikes in sales. Subscription features, membership programs and cross-selling of additional reports lift revenue per customer, and detailed customer data helps companies target marketing more efficiently than through retail partners.
Over-the-counter sales are projected to register the fastest growth as retailers and pharmacies stock kits next to other health products, which reaches shoppers who do not normally buy online. Retail placement builds trust and lets buyers ask pharmacists about tests. Wider shelf presence in emerging markets also supports growth for suppliers. Pharmacy chains and big-box retailers also offer gift cards and instant activation, which helps shoppers buy at the moment of interest. Partnerships with health insurers and employers may widen this channel further. Online campaigns around holidays, such as National DNA Day and family gatherings, also support seasonal growth across markets.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
88.00 |
|
Europe |
United Kingdom |
26.00 |
|
Asia Pacific |
China |
38.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
United Arab Emirates |
25.00 |
North America DTC Genetic Testing Market Insights
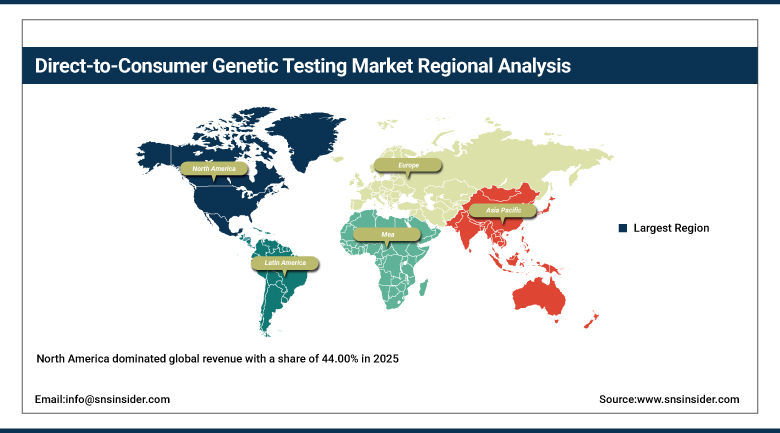
North America dominated revenue with a share of 44.00% in 2025. The United States accounts for major share of regional demand, with Canada adding volume. 23andMe, Ancestry, Labcorp, Color Health, Helix, Myriad Genetics, Nebula Genomics and Nucleus Genomics serve consumers in the region. Companies in the region also use large research databases built from consenting customers to partner with drug developers, which funds lower consumer prices and new product development.
Leadership rests on early adoption, a large base of existing customers, wide online retail and strong interest in preventive health. Health systems and laboratories are launching clinician-supported tests, and pharmacogenomics is gaining attention. Privacy worries, state regulation, limited insurance coverage and test fatigue among earlier buyers moderate growth, though new product types and lower prices help renew demand. Telehealth firms, primary care groups and genetic counselors are building services around test results, and employers and health plans are testing programs that offer pharmacogenomic reports to members.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe DTC Genetic Testing Market Insights
The United Kingdom, Germany, France, Italy and Spain lead regional demand. MyHeritage, Living DNA, Ovation.io, Karmagenes and Easy DNA are among the companies serving customers, and local laboratories support ancestry and wellness testing. Strong demand for tracing family roots across Europe, where many people have relatives overseas, supports ancestry tests, and Israeli and British firms have long histories in this field. Cross-border shipping inside Europe and the strength of university genetics programs also support steady demand from curious consumers.
Consumers value ancestry and family history tests, and wellness interest is growing. Strict data protection rules under European law push companies to build strong consent and storage systems, while some countries limit health-related tests sold without a doctor. Regulatory differences between countries, privacy concerns and lower awareness of health risk reports moderate growth. Research funding and public biobanks in the United Kingdom and Nordic countries raise public awareness of genetics, which supports interest in consumer tests and in clinically supervised offers.
⮞On April 15, 2026, Ovation.io, based in Oxford, England and Portland, Maine, and PrecisionLife announced a collaboration to commercialize analysis of Ovation's GLP-1 dataset. They plan a consumer DNA test on likely safety, efficacy and tolerability of GLP-1 drugs, with launch targeted for the second half of 2026.
Asia Pacific DTC Genetic Testing Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 17.60% during 2026-2035. China leads regional demand, followed by Japan, India, South Korea and Australia, supported by rising incomes, interest in health and large online platforms. BGI Genomics, Mapmygenome, WeGene and other regional companies offer ancestry, wellness and health risk tests. Large online marketplaces and social media platforms in the region allow genetic test brands to reach millions of buyers, and partnerships with hospitals add credibility for health-related reports.
Large populations, growing middle classes and strong e-commerce ecosystems provide a wide base for kits. Several governments are developing national genomics programs, and local laboratories are lowering prices. Regulation of genetic data, restrictions on sample export and uneven consumer awareness moderate growth, though interest in preventive health continues to rise. Japan, South Korea and Australia have the most developed consumer markets and clearer rules, while China and India provide scale. Local laboratories are keeping prices low, which widens the base of buyers.
⮞On April 7, 2026, BGI Group reported that BGI-Research co-led development of ISO/TS 20738:2026 with the China National Institute of Standardization. The standard, published on March 5, 2026, sets requirements for analyzing genetic data from consumer-initiated tests without the involvement of a health care provider.
MEA & Latin America DTC Genetic Testing Market Insights
Brazil is leading in the Latin American region, followed by Mexico, Argentina, Colombia and Chile. The ancestry market interest is high due to the multiracial population and the expansion of online retailing. High cost, importation of kits and data privacy regulations affect the adoption rate. Brazil has the biggest consumer base and a growing number of laboratories offering ancestry and health kits, while Mexico has the advantage of cross-border e-commerce and youth interested in their heritage. Increased usage of smartphones and social media for the sharing of results is aiding the growth in interest among the younger population.
The UAE, Saudi Arabia, South Africa, Egypt and Qatar lead the market demand in the Middle East and Africa region. National genome projects and wellness clinics in the Gulf region are fueling the market interest, while low awareness and affordability issues are limiting its growth in the other countries. The wealthy consumers in the Gulf region are attracted by preventive health clinics and national genome projects, which increase the awareness, while South Africa has an established laboratory base and research institutions.
Market Dynamics
Growth Drivers: Falling Sequencing Costs, Health Interest and Online Access
Lower costs for chips and sequencing let companies sell richer reports at consumer prices. Interest in preventive health, fitness and personalized nutrition pulls new buyers. Social media sharing of results and celebrity endorsements also raise awareness and help new brands acquire customers at lower cost. Declining prices for kits make it easier for new buyers to try a test for the first time, which expands the customer base each year.
Online ordering, mobile apps and mail-in kits make testing simple, and pairing tests with counseling builds confidence in results. Wider acceptance of telehealth makes it easier for consumers to discuss results with a clinician and act on them. Greater public understanding of genetics, driven by news coverage of new medicines and screening programs, supports continued interest in personal testing.
Restraints: Data Privacy, Regulation and Test Fatigue
Uncertainties about how genetic information may be kept, sold or distributed could affect confidence, particularly after the selling of a major business through bankruptcy. Lawsuits, hacking, and investigations by the government of data management practices could make customers terminate their accounts. Some countries even regulate the export of genetic samples, making the lab model for international operations more difficult.
Regulation varies between different countries, with most customers testing just once, meaning that there is less recurring revenue. Exclusions by insurance providers and questions over the clinical value of some tests could hinder the adoption of recurring revenue. Reports of false positives from health risks could make physicians wary of direct-to-consumer results.
Opportunities: Pharmacogenomics, Clinical Partnerships and Emerging Markets
Tests on drug response, including weight-loss medicines, and links to physicians turn consumer interest into health services. Partnerships with drug developers can fund large datasets and speed the development of new consumer tests. Hospitals and fertility clinics are also adding consumer-facing genetic services, which opens another path to customers who value physician guidance.
Large laboratories, pharmaceutical firms and regional companies can reach new customers in Asia Pacific, Latin America and the Middle East with local pricing. Localized pricing and language support also help brands reach customers who are not served well today. Subscription services that update reports as science advances can add recurring revenue.
Recent Developments:
- In August 2026, Labcorp made its Marker by Labcorp Genetic Health Panel, analyzing 163 genes, available through Labcorp OnDemand.
- In April 2026, PrecisionLife and Ovation.io announced a collaboration targeting a consumer GLP-1 response DNA test in the second half of 2026.
- In April 2026, BGI Group reported its role in developing ISO/TS 20738:2026, a standard for analyzing data from consumer genetic tests.
- In July 2025, TTAM Research Institute completed the acquisition of 23andMe's Personal Genome Service and Research Services assets.
Direct-to-Consumer Genetic Testing Market Key Players are:
- 23andMe
- Ancestry
- MyHeritage Ltd.
- FamilyTreeDNA (Gene By Gene)
- Helix OpCo, LLC
- Color Health, Inc.
- Living DNA Ltd.
- Mapmygenome India Ltd.
- Nebula Genomics, Inc.
- Nucleus Genomics, Inc.
- Laboratory Corporation of America Holdings (Labcorp)
- Myriad Genetics, Inc.
- Easy DNA
- Identigene, LLC
- Full Genome Corporation
- Karmagenes
- Pathway Genomics Corporation
- BGI Genomics Co., Ltd.
- Genesis Healthcare, Inc.
- WeGene
Direct-to-Consumer Genetic Testing Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.94 Billion |
| Market Size by 2035 | USD 10.54 Billion |
| CAGR | CAGR of 13.62% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Test Type (Ancestry and Relationship Testing, Health Risk Testing, Nutrigenomics and Wellness, Carrier Screening, and Pharmacogenomics) • By Technology (SNP Chips, Whole Genome Sequencing, and Targeted Analysis) • By Sample Type (Saliva, Blood, and Others) • By Distribution Channel (Online Platforms and Over-the-Counter) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | 23andMe; Ancestry; MyHeritage Ltd.; FamilyTreeDNA (Gene By Gene); Helix OpCo, LLC; Color Health, Inc.; Living DNA Ltd.; Mapmygenome India Ltd.; Nebula Genomics, Inc.; Nucleus Genomics, Inc.; Laboratory Corporation of America Holdings (Labcorp); Myriad Genetics, Inc.; Easy DNA; Identigene, LLC; Full Genome Corporation; Karmagenes; Pathway Genomics Corporation; BGI Genomics Co., Ltd.; Genesis Healthcare, Inc.; WeGene |

Frequently Asked Questions
Key players include 23andMe, Ancestry, MyHeritage Ltd., FamilyTreeDNA (Gene By Gene), Helix OpCo, LLC, Color Health, Inc., Living DNA Ltd. and Mapmygenome India Ltd.
Key opportunities include pharmacogenomics, clinical and laboratory partnerships, and expansion into emerging markets in Asia Pacific, Latin America and the Middle East.
The major growth factor is the falling cost of genotyping and sequencing, which allows companies to sell richer reports at consumer prices.
By Test Type, the Ancestry and Relationship Testing segment dominated the market in 2025 with an estimated 36.00% share, supported by low prices and large family databases.
North America dominated the market with a share of 44.00% in 2025, driven by early adoption, online retail and interest in preventive health.
