
E-Prescribing Market Report Scope & Overview:
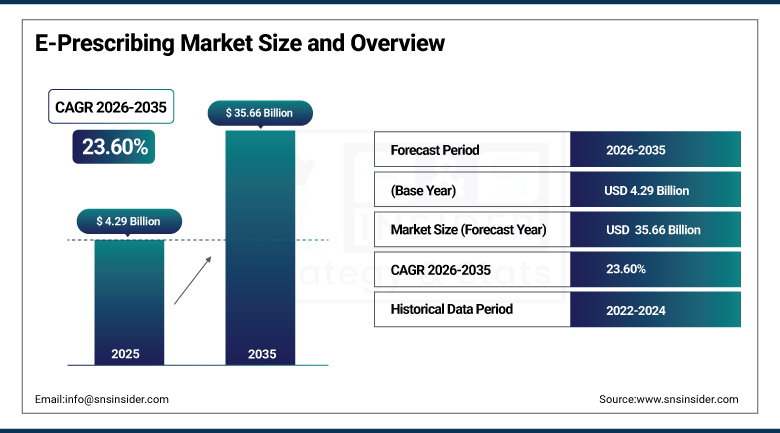
The E-Prescribing Market was valued at USD 4.29 Billion in 2025 and is expected to reach USD 35.66 Billion by 2035, growing at a CAGR of 23.60% from 2026-2035.
E-prescribing belongs to one of the essential categories of digital health IT infrastructures, involving software platforms that facilitate the process of creating and managing medication prescriptions in electronic format instead of handwriting or verbal prescription ordering processes. The ever-growing governmental demand for electronic prescription transmission for controlled substances, an increasing focus on minimizing errors in medication management, and the increasing integration of EHR systems are constantly enlarging the pool of providers who need such software.
Continuous market expansion will be driven by further evolution of mobile-first e-prescribing apps, greater acceptance of cloud solutions, and development of more sophisticated regulation systems that connect national health identification with electronic prescriptions, consolidating the market status as a long-lasting and technology-driven segment of the overall healthcare IT industry. The increasing convergence of E-prescribing and telehealth solutions highlights its importance as a central node of a digitized care delivery model.
In 2025, Surescripts continued expanding its nationwide e-prescribing network connecting prescribers, pharmacies, and health plans, emphasizing real-time prescription benefit and medication history data supporting more informed prescribing decisions.
To Get more information On E-Prescribing Market - Request Free Sample Report
E-Prescribing Market Trends
- Growing adoption of mobile-first prescribing applications enabling clinicians to prescribe from any location.
- Rising regulatory mandates requiring electronic transmission of controlled-substance prescriptions.
- Expanding integration between e-prescribing platforms and broader electronic health record ecosystems.
- Increasing adoption of cloud-based deployment models reducing on-premise infrastructure requirements.
- Rising demand for real-time prescription benefit checking improving cost transparency at the point of care.
- Growing national digital health identification programs linking citizen records to electronic prescriptions.
U.S. E-Prescribing Market Overview
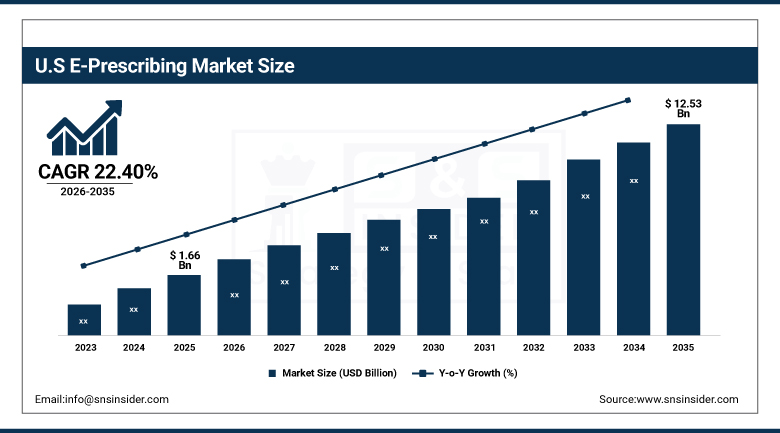
The U.S. E-Prescribing Market was valued at USD 1.66 Billion in 2025 and is expected to reach USD 12.53 Billion by 2035, growing at a CAGR of 22.40% from 2026-2035.
The demand in the United States remains supported by both federal and state legislation mandating electronic prescriptions for controlled substances in addition to ongoing development of interoperable electronic health records technology throughout hospital and physician office networks in the country. The leading companies remain focused on enhancing their connectivity networks between prescribers and pharmacies as well as meeting increasing demands for the delivery of real-time information regarding the prescription drug history and the prescription benefit information. Telemedicine is increasingly contributing to the growth of the market across the U.S. due to the necessity of the reliable electronic prescription transmission system throughout the country.f
In 2025, DrFirst continued expanding its electronic prior authorization and medication management platform, integrating real-time benefit verification directly into clinician prescribing workflows. The company stated the continued investment addresses growing provider demand for reducing administrative burden associated with prescription-related insurance approvals, a persistent source of clinician frustration and delayed patient access to prescribed therapies.
E-Prescribing Market Segment Analysis
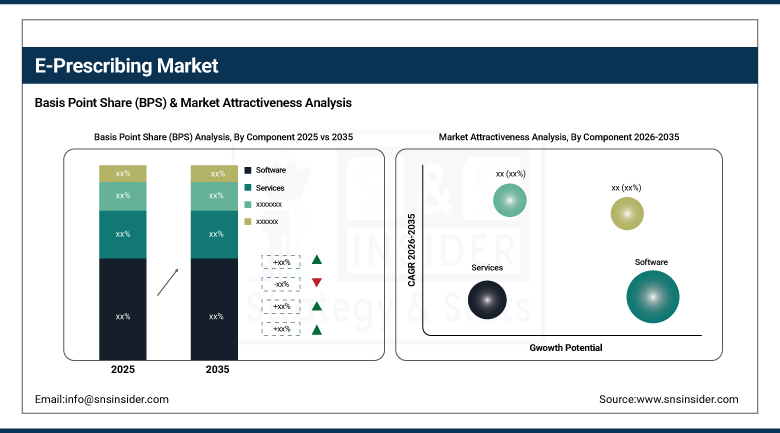
- By Component, the Software segment dominated the market with a 65.45% share in 2025, while the Services segment is the fastest growing with a CAGR of 26.45% during 2026-2035.
- By Delivery Mode, the Cloud-Based segment dominated the market with a 54.34% share in 2025, while the Mobile-Based segment is the fastest growing with a CAGR of 26.56% during 2026-2035.
- By Prescription Type, the Controlled Substances segment dominated the market with a 38.54% share in 2025, while the Non-Controlled Substances segment is the fastest growing with a CAGR of 25.67% during 2026-2035.
- By End User, Hospitals held the largest market share in 2025 with around 48.74%, while Pharmacies are expected to register the fastest growth with around 22.12% CAGR during the forecast period.
By Component, Software Dominates the E-Prescribing Market and Services Grows Fastest
The software segment continues to hold the highest share among all the component segments in the E-Prescribing Market owing to the need for licenses from the underlying platforms for creating, sending and linking prescriptions electronically. The reason why healthcare organizations are choosing to invest in this component category is that software is a fundamental technical necessity and no process of e-prescribing can take place without it and hence is responsible for recurring licensing and subscription revenue for most vendors. The fact that software is a critical necessity in itself keeps on ensuring its relevance as the first choice component category as new categories of services keep coming up.
The services segment is now turning out to be the fastest-growing component segment in the market due to the importance of services related to onboarding, compliance and optimization in addition to software licensing. As e-prescribing platforms get increasingly complex in terms of their functionalities such as control-substance compliance and integration with EHRs, the healthcare organizations are now looking to have help from the vendors themselves in terms of delivery and support of such services.
By Delivery Mode, Cloud-Based Dominates the E-Prescribing Market and Mobile-Based Grows Fastest
Cloud-Based delivery continues to lead the market, reflecting healthcare organizations' growing preference for reduced on-premise infrastructure investment, simplified maintenance, and more rapid deployment relative to traditional on-premise installations. This delivery mode's scalability and lower upfront capital requirements continue to make it the default choice for both large health systems and smaller independent practices seeking to modernize prescribing workflows. Vendors offering cloud-native architectures continue to benefit from faster implementation timelines relative to legacy on-premise competitors still transitioning their platforms, particularly as multi-site health systems increasingly demand centralized configuration management across dozens or hundreds of individual locations.
Mobile-Based delivery is expanding at the fastest pace among delivery mode categories, as clinicians increasingly demand the ability to prescribe medications from any location without requiring access to a fixed workstation. As smartphone-based clinical workflows continue to mature across both hospital and ambulatory care settings, mobile-first prescribing applications continue to close the gap with traditional cloud and on-premise deployments in overall market demand. Growing adoption of secure biometric authentication on mobile devices further addresses earlier security concerns that had previously slowed clinician acceptance of mobile prescribing tools, particularly for controlled-substance transactions requiring heightened identity verification standards.
By Prescription Type, Controlled Substances Dominates the E-Prescribing Market and Non-Controlled Substances Grows Fastest
Controlled Substances represent the largest prescription type category, reflecting the substantial regulatory push across major markets to digitize prescribing of opioids, stimulants, and other regulated medications in order to reduce diversion and improve prescription monitoring capability. Government mandates requiring electronic transmission of these prescriptions continue to anchor this category's leading position across the broader market, with penalties for non-compliance continuing to reinforce near-universal provider adoption for this prescription class specifically, a dynamic that has effectively eliminated paper-based prescribing for regulated substances across most major healthcare markets.
Non-Controlled Substances are recording the fastest growth among prescription type categories, as broader adoption of electronic prescribing continues to extend beyond regulatory-mandated controlled substance categories into routine, everyday medication management. As providers increasingly standardize fully electronic prescribing workflows across their entire patient population rather than maintaining separate paper-based processes for non-regulated medications, this category continues to expand its share of overall transaction volume, driven by administrative efficiency gains from eliminating dual paper-and-electronic workflows entirely. Practices that once maintained parallel paper and electronic systems for different medication classes increasingly recognize the operational cost of that duplication and are consolidating onto fully digital workflows.
By End User, Hospitals Dominate the E-Prescribing Market and Pharmacies Grow Fastest
Hospitals are the biggest group of end-users in the E-Prescribing Market, due to their large volume of prescriptions, the presence of extensive networks of physicians and growing adoption of the integrated electronic health records (EHR) and e-prescribing solutions. The increasing focus on medication safety, the integration of clinical workflows, improved prescription accuracy, and regulatory compliance remains the main drivers of adoption in this market segment. Integration of e-prescribing solution with the hospital information system and electronic medical records allows the provider to optimize the prescription workflows, decrease the number of medication errors, enhance access to the history of medications of the patients and to provide better coordinated care.
Pharmacies are showing the fastest growth in the segment of end-users of the E-prescribing market, driven by the continuous growth in volumes of electronic prescriptions and increased participation of pharmacies in digital healthcare ecosystem. Since the prescriptions are sent to the pharmacies electronically from the providers, the digital workflows allow decreasing the amount of manual data input, speeding up the process of prescribing and improving the communication between the prescribers and dispensing organizations.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|
North America |
United States |
85.60% |
|
Asia Pacific |
China |
41.83% |
|
Europe |
Germany |
33.62% |
|
Latin America |
Brazil |
45.94% |
|
Middle East & Africa |
United Arab Emirates |
28.17% |
North America E-Prescribing Market Insights
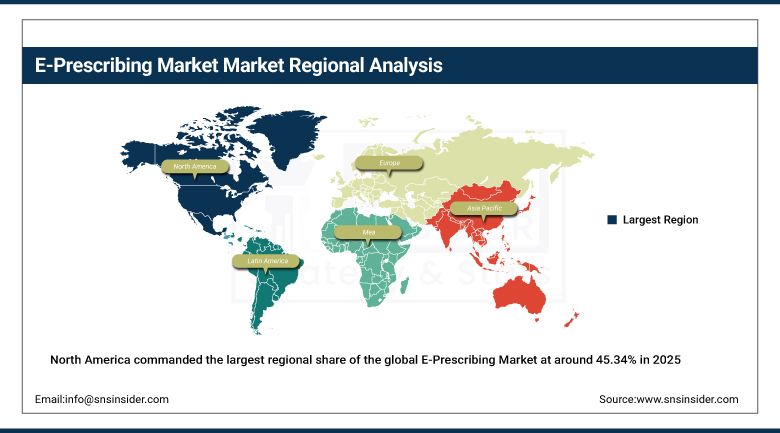
North America commanded the largest regional share of the global E-Prescribing Market at around 45.34% in 2025, a position underpinned by comprehensive federal and state electronic prescribing mandates and a mature, highly interoperable health information technology infrastructure. The United States shapes regional demand through its concentration of leading e-prescribing network operators and its extensive, federally incentivized electronic health record adoption base. Decades of accumulated federal meaningful-use incentive programs continue to sustain a well-established, deeply embedded electronic prescribing culture across virtually every care setting nationwide, from large academic medical centers down to solo rural practices.
Canada contributes additional regional demand through its participation in North American healthcare technology procurement and interoperability frameworks. Continued regulatory expansion around controlled-substance electronic prescribing is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building out digital health infrastructure from a considerably smaller existing base. Mexico's gradually modernizing healthcare technology sector further contributes incremental demand across the broader North American market.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific E-Prescribing Market Insights
Asia Pacific stands out as the fastest-growing region expanding at a projected CAGR of 25.45%, propelled by Japan's medical digital transformation program linking national identification cards to electronic prescriptions and China's integrated care, insurance, and pharmaceutical supply chain reforms. China continues to anchor regional demand as national health information platforms expand electronic prescribing connectivity across both public and private healthcare providers, supported by sustained government investment in unifying fragmented regional health data systems into a single, nationally coherent digital health infrastructure.
Japan's rapidly maturing digital health identification infrastructure continues to accelerate electronic prescribing adoption nationwide, while South Korea and India contribute further depth through expanding hospital digitization programs. Continued government investment in interoperable health information systems is expected to position the wider region to sustain the fastest percentage growth of any global market through 2035, as governments increasingly view unified digital prescribing infrastructure as central to broader universal healthcare coverage ambitions.
Europe E-Prescribing Market Insights
Europe commands a significant portion of the global market through the implementation of national digital health policies and the ongoing interoperability efforts to facilitate electronic prescriptions across all member states. The strong presence of health IT facilities in Germany is bolstered by national efforts to upgrade their health records system, as well as an increasing number of e-prescription software providers that service the public as well as private insurance programs.
The UK and France, among other larger countries in Europe, provide consistent demand for the product as their health care organizations expand the use of electronic prescriptions in practice. Ongoing cross-border efforts between EU member states to exchange health care data will further support this long-term demand projection.
MEA & Latin America E-Prescribing Market Insights
Latin America's market is anchored by Brazil, where a sizeable domestic healthcare technology sector sustains steady platform demand across both public and private provider networks. Mexico contributes further incremental growth as digital health infrastructure investment continues to expand across the broader region, supported by growing government interest in reducing prescription fraud and improving medication safety oversight.
The Middle East & Africa region continues to grow gradually, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where national digital health strategies are increasingly incorporating electronic prescribing as a standard component. South Africa continues to anchor demand on the African continent, supported by a comparatively more developed private healthcare technology sector relative to neighbouring markets.
Market Dynamics
Growth Drivers: Regulatory Mandates and Medication Error Reduction
Increasing focus on reducing errors represents another major growth driver, considering that the adoption of electronic prescribing solutions is continuously demonstrating a higher level of effectiveness in terms of avoiding transcription errors, illegible handwriting problems, as well as potential hazards linked to the interaction between medicines, compared to paper prescribing solutions. This trend is fueled by the growing governmental regulations concerning the use of electronic solutions for transmitting controlled substance prescriptions, with regulators in key markets increasingly making allowances and imposing obligations for accelerating adoption of electronic platforms. Higher risk associated with prescribing errors and malpractice liability considerations represent additional drivers for increased adoption of more reliable electronic solutions than paper-based ones, particularly as insurance companies start to factor technology adoption into malpractice premium costs.
Increased integration with electronic health records ecosystems represents another major driver of growth, with healthcare organizations increasingly seeking integrated digital solutions from documentation to prescribing medicines. The growing adoption of telemedicine practices combined with increasing need for prescription benefits and medication history data represent key trends driving continuous expansion of the market not only in established Western health care systems but also in developing markets.
Restraints: Interoperability Challenges and Provider Workflow Disruption
Interoperability challenges remain a genuine restraint on market growth, as fragmented health information technology ecosystems across differing regions and even individual health systems continue to complicate seamless electronic prescription transmission between disparate platforms. This complexity particularly affects smaller, independent practices lacking the technical resources to manage integration across multiple vendor systems simultaneously, often resulting in delayed or incomplete platform adoption relative to larger, better-resourced health systems that can afford dedicated integration engineering staff.
Provider workflow disruption during implementation presents a further restraint, as transitioning from paper-based or legacy electronic systems to new platforms can temporarily reduce clinical efficiency and require substantial staff retraining investment. This transition friction can meaningfully delay full-scale platform adoption, particularly among smaller practices with limited administrative capacity to manage complex system migrations, sometimes prompting providers to defer upgrades until regulatory deadlines force action, at which point compressed implementation timelines can further heighten operational risk.
Opportunities: Mobile Prescribing Expansion and AI-Enabled Clinical Decision Support
Continued expansion of mobile-first prescribing applications offers a substantial opportunity, as vendors developing platforms enabling clinicians to prescribe securely from any location stand to capture meaningful new demand from increasingly mobile, distributed care delivery models. Providers increasingly view mobile prescribing capability not as a convenience feature but as a genuine operational necessity supporting on-call coverage, home visits, and telehealth consultations across expanding care delivery footprints, particularly as staffing models increasingly rely on rotating and remote clinical coverage arrangements.
The continued integration of artificial intelligence-enabled clinical decision support presents a further avenue for growth, as platforms increasingly flag potential drug interactions, dosing errors, and formulary alternatives in real time, positioning vendors with advanced analytics capability to differentiate from basic transmission-only competitors. This innovation pathway continues to open substantial new demand for vendors capable of embedding intelligent, contextual guidance directly into everyday prescribing workflows without adding friction to the clinician experience, a balance that continues to separate market-leading platforms from lower-cost, feature-limited alternatives.
Recent Developments:
- 2025: Epic Systems continued expanding its integrated e-prescribing capability within its broader electronic health record platform, supporting seamless prescription workflows for hospital and health system customers.
- 2025: Oracle Health continued developing electronic prescribing functionality within its Cerner-based clinical platform, emphasizing controlled-substance compliance and medication reconciliation capability.
- 2025: Veradigm continued expanding its e-prescribing network connectivity, supporting independent physician practices and specialty clinics with real-time prescription benefit verification.
E-Prescribing Market Key Players are:
- Surescripts, LLC
- Veradigm Inc. (Allscripts)
- Epic Systems Corporation
- Oracle Health (Cerner Corporation)
- DrFirst, Inc.
- RxNT
- athenahealth, Inc.
- NewCrop, LLC
- eClinicalWorks LLC
- Change Healthcare (UnitedHealth Group)
- MEDITECH
- CoverMyMeds LLC (McKesson)
- iPatientCare, Inc.
- Practice Fusion, Inc. (Veradigm)
- NextGen Healthcare, Inc.
- Greenway Health, LLC
- Kareo, Inc. (Tebra)
- ModMed (Modernizing Medicine)
- Nabla
- Truepill, Inc.
E-Prescribing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.29 Billion |
| Market Size by 2035 | USD 35.66 Billion |
| CAGR | CAGR of 23.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Services) • By Delivery Mode (Cloud-Based, On-Premise, and Mobile-Based) • By Prescription Type (Controlled Substances and Non-Controlled Substances) • By End User (Hospitals, Physician Offices, and Pharmacies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Surescripts, LLC; Veradigm Inc. (Allscripts); Epic Systems Corporation; Oracle Health (Cerner Corporation); DrFirst, Inc.; RxNT; athenahealth, Inc.; NewCrop, LLC; eClinicalWorks LLC; Change Healthcare (UnitedHealth Group); MEDITECH; CoverMyMeds LLC (McKesson); iPatientCare, Inc.; Practice Fusion, Inc. (Veradigm); NextGen Healthcare, Inc.; Greenway Health, LLC; Kareo, Inc. (Tebra); ModMed (Modernizing Medicine); Nabla; Truepill, Inc. |

Frequently Asked Questions
Key players include Surescripts, Veradigm, Epic Systems, Oracle Health, DrFirst, RxNT, athenahealth, NewCrop, eClinicalWorks, and Change Healthcare, among others.
Continued expansion of mobile-first prescribing applications and the continued integration of artificial intelligence-enabled clinical decision support represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by growing emphasis on medication error reduction, combined with expanding government mandates requiring electronic transmission of controlled-substance prescriptions.
By Component, Software dominated the market with a 65.45% share in 2025, reflecting core licensing demand across hospitals and physician practices.
North America commanded the largest share at 45.34% in 2025, underpinned by comprehensive federal and state electronic prescribing mandates.
