
Healthcare Analytical Testing Services Market Report Scope & Overview:
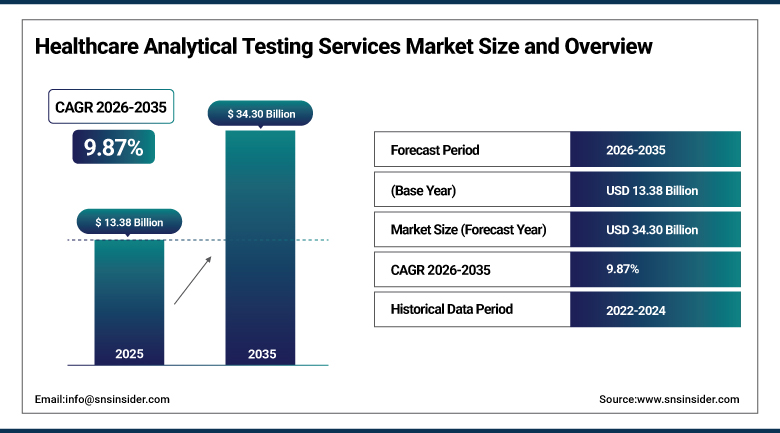
The Healthcare Analytical Testing Services Market was valued at USD 13.38 Billion in 2025 and is expected to reach USD 34.30 Billion by 2035, growing at a CAGR of 9.87% from 2026-2035.
The Healthcare Analytical Testing Services Market is expanding as drug and device makers outsource more laboratory work to specialist providers. Biologics, biosimilars and cell and gene therapies require complex tests that many sponsors cannot run in house. Regulators expect validated methods and strong data integrity records. Impurity rules for nitrosamines, extractables and leachables have widened the scope of testing. Contract laboratories are adding capacity in the United States, Europe and Asia. Mass spectrometry and cell-based assays are becoming standard tools. Shortages of trained scientists and high equipment cost limit expansion for smaller laboratories. Pricing pressure from large sponsors also affects margins. The market is expected to grow as development pipelines and quality requirements increase.
⮞In March 2024, the U.S. Food and Drug Administration issued the final ICH Q2(R2) guidance on validation of analytical procedures, replacing the 2022 draft. The guidance raises expectations for method validation across pharmaceutical testing laboratories.
To Get more information Healthcare Analytical Testing Services Market - Request Free Sample Report
Healthcare Analytical Testing Services Market Trends:
-
Rising outsourcing of bioanalytical and release testing for biologics and biosimilars
-
Growth of testing for cell and gene therapies, including viral vector characterization
-
Wider use of mass spectrometry and cell-based bioassays for complex molecules
-
Stricter impurity controls, including nitrosamines and extractables and leachables
-
Acquisitions that expand laboratory networks and medical device testing capacity
U.S. Healthcare Analytical Testing Services Market Outlook:
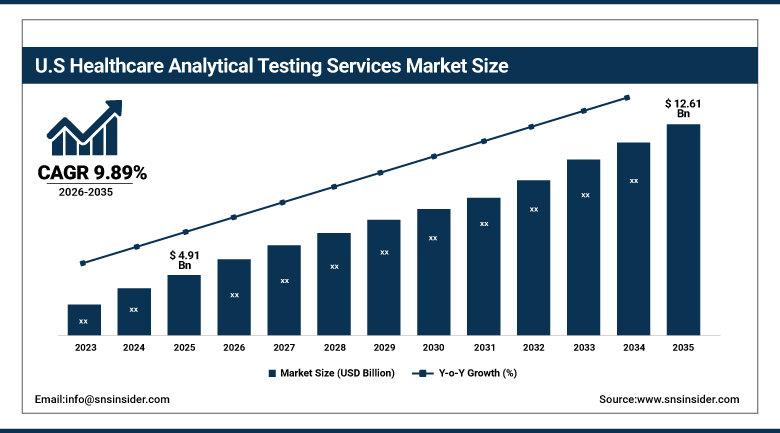
The U.S. Healthcare Analytical Testing Services Market was valued at USD 4.91 Billion in 2025 and is expected to reach USD 12.61 Billion by 2035, growing at a CAGR of 9.89% from 2026-2035.
The U.S. Healthcare Analytical Testing Services Market is the largest national market and is supported by a deep drug development pipeline and strict FDA expectations. Biotechnology clusters in Massachusetts, North Carolina and California generate steady demand for outsourced testing. Sponsors rely on contract laboratories for bioanalytical, release and stability studies. Medical device makers need biocompatibility and chemical characterization data for submissions. Laboratory acquisitions continue to reshape the provider landscape. Labor costs and a limited supply of analytical scientists raise operating expense. Compliance with data integrity rules adds work for every study. Demand is therefore expected to rise with new biologics and advanced therapies.
⮞In October 2025, Alcami announced a 20,000-square-foot laboratory expansion at its Durham, North Carolina facility to meet growing demand in biologics. The expansion shows how U.S. providers are adding capacity for complex molecule testing.
Healthcare Analytical Testing Services Market Segment Analysis:
-
By Service Type, the Bioanalytical Testing segment dominated the Healthcare Analytical Testing Services Market with approximately 29.88% share in 2025, while the Extractables and Leachables Testing segment is the fastest growing with a CAGR of approximately 11.67%.
-
By End User, the Pharmaceutical and Biopharmaceutical Companies segment dominated the Healthcare Analytical Testing Services Market with approximately 52.25% share in 2025, while the CDMOs and CROs segment is the fastest growing with a CAGR of approximately 10.37%.
-
By Technology, the Chromatography-Based Testing segment dominated the Healthcare Analytical Testing Services Market with approximately 25.20% share in 2025, while the Cell-Based Bioassays segment is the fastest growing with a CAGR of approximately 11.97%.
-
By Development Phase, the Commercial and Quality Control Release segment dominated the Healthcare Analytical Testing Services Market with approximately 29.90% share in 2025, while the Preclinical and Phase I segment is the fastest growing with a CAGR of approximately 10.58%.
By Service Type, Bioanalytical Testing Dominates the Healthcare Analytical Testing Services Market and Extractables and Leachables Testing Grows Fastest
Bioanalytical testing leads because every drug candidate needs pharmacokinetic, toxicokinetic and immunogenicity data to support dosing and safety decisions. Sponsors send plasma and tissue samples to laboratories that run validated assays for small molecules, antibodies and biomarkers. The rising number of biologics has increased demand for ligand binding and mass spectrometry methods. Regulators expect study data to follow good laboratory practice, so experienced providers with audited systems attract repeat work. Long-term relationships with sponsors also give large laboratories stable revenue across development phases. Growth in clinical trial volumes and the rise of antibody drug conjugates and biosimilars further increase the number of samples that laboratories must process each year.
Extractables and leachables testing is growing fastest as regulators focus on substances that migrate from packaging, devices and single-use manufacturing systems into drug products. Prefilled syringes, inhalers, combination products and bioprocess bags all require chemical characterization before approval. Laboratories invest in high resolution mass spectrometry and toxicological assessment capabilities to meet these expectations. Medical device makers also need these data for biological evaluation submissions. As product designs become more complex, sponsors turn to specialist providers that can run studies quickly and support regulatory responses. Specialist laboratories that combine analytical chemistry with toxicology expertise are therefore winning a growing share of packaging and device characterization projects from sponsors.
⮞In July 2025, Solvias announced that its Research Triangle Park center had become cGMP-ready, with a second phase adding 30,000 square feet of laboratory space. The expansion shows investment in U.S. capacity for analytical and characterization services.
By End User, Pharmaceutical and Biopharmaceutical Companies Dominates the Healthcare Analytical Testing Services Market and CDMOs and CROs Grows Fastest
Pharmaceutical and biopharmaceutical companies account for the largest share because they hold the product portfolios and carry regulatory responsibility for quality. They outsource specialized assays, overflow work and release testing to laboratories with proven capacity. Small biotechnology companies without in-house laboratories rely on providers for almost all analytical work. Large sponsors use preferred supplier programs that consolidate testing with a few partners. This purchasing pattern gives established laboratories steady volume and encourages investment in new platforms and quality systems. Sponsors also value the regulatory knowledge that established laboratories bring, which lowers the risk of delays during inspections, audits and filings with health authorities.
Contract development and manufacturing organizations and contract research organizations are growing fastest as sponsors move whole programs to integrated partners. These firms need analytical services to support process development, stability studies and batch release, and they often subcontract specialized tests to testing laboratories. Growth in outsourced manufacturing of biologics, peptides and advanced therapies increases the volume of in-process and release samples. Some providers combine laboratory and manufacturing offers, which allows them to capture work from early development to commercial supply. Integrated providers that bundle testing with manufacturing therefore gain a structural advantage over stand-alone laboratories when they compete for large multi-year programs.
⮞In August 2026, WuXi AppTec reported first-half total revenue of RMB 28.90 billion. The result shows the scale of integrated outsourcing providers serving drug developers.
By Technology, Chromatography-Based Testing Dominates the Healthcare Analytical Testing Services Market and Cell-Based Bioassays Grows Fastest
Chromatography-based testing leads because liquid and gas chromatography remain the workhorses for assay, impurity, dissolution and stability work. Methods are well understood by regulators and are written into pharmacopeial monographs. Laboratories operate large fleets of instruments that handle high sample volumes with automated sample preparation. The same platforms support small molecule drugs, excipients and packaging studies. Coupling chromatography with mass detectors further widens its use, which keeps this technology at the center of most laboratory service portfolios. High throughput autosamplers and validated software platforms keep unit costs low, which supports the continued use of this technology for routine testing across product types.
Cell-based bioassays are growing fastest because biologics and advanced therapies need functional proof of potency, not only chemical identity. Regulators ask for relevant potency assays for monoclonal antibodies, vaccines and cell and gene therapies, and these assays are time consuming to develop and validate. Providers are investing in automation, cell culture capacity and flow cytometry to serve these needs. Demand is also rising for viral vector characterization and biosafety testing. The complexity and cost of in-house development push sponsors toward specialist laboratories. Automation of cell handling and standardized reference materials are gradually improving assay reproducibility and shortening validation timelines for providers that serve biologic developers.
⮞In September 2026, TÜV SÜD opened a Frankfurt laboratory for biological safety, reusable device and lot release testing, equipped with GC-MS and QTOF-LC/MS instruments. The laboratory shows investment in advanced analytical platforms.
By Development Phase, Commercial and Quality Control Release Dominates the Healthcare Analytical Testing Services Market and Preclinical and Phase I Grows Fastest
Commercial and quality control release testing leads because every marketed batch must pass identity, assay, impurity and sterility checks before shipment. Products remain on the market for many years, so testing volumes recur and grow with sales. Stability programs follow each product through its shelf life and require repeated sampling. Regulatory changes, such as new impurity limits, trigger retesting of existing products. Contract laboratories gain long-term contracts from this work, which provides predictable revenue and supports investment in capacity. Regulators also expect continued process verification, which keeps sampling plans active throughout the commercial life of every approved product and supports recurring volumes.
Preclinical and Phase I testing is growing fastest as venture funding supports a large number of early programs, many of them biologics and novel modalities. Early studies need method development, bioanalysis, formulation characterization and toxicology support in a short time. Small sponsors without laboratories outsource the entire package. Rapid growth of Chinese and Indian biotechnology firms is adding to early stage demand. Providers that can move quickly from method design to validated assays gain a strong position, and they often keep the customer into later phases. Providers that offer flexible capacity and rapid method development can therefore win early stage work and retain the sponsor as its programs move into later development phases.
⮞In March 2026, the DIA Global Forum reported that China's National Medical Products Administration approved 120 new drugs in 2025, the first time the total passed 100. The record shows the pipeline that Chinese testing providers support.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
90.07 |
|
Europe |
Germany |
25.54 |
|
Asia Pacific |
Japan |
29.19 |
|
Latin America |
Brazil |
41.96 |
|
Middle East & Africa |
Saudi Arabia |
33.27 |
North America Healthcare Analytical Testing Services Market Insights
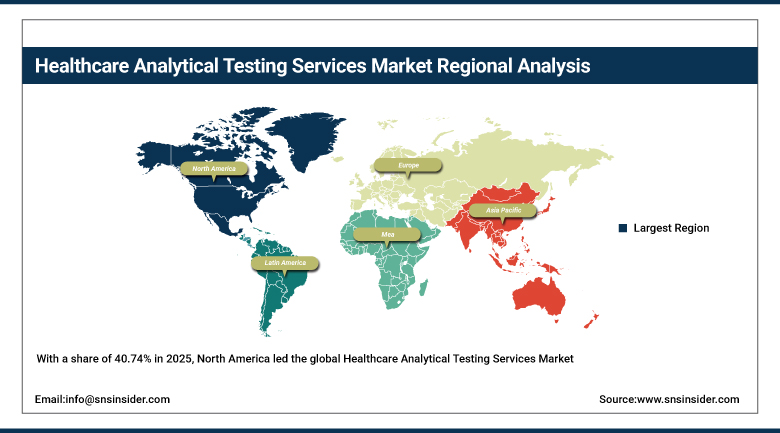
With a share of 40.74% in 2025, North America led the global Healthcare Analytical Testing Services Market. The United States contributes most regional demand through a large number of drug candidates, a mature contract laboratory sector and strict FDA expectations. Canada adds activity through biotechnology clusters in Ontario, Quebec and British Columbia. Leading providers such as Charles River, Labcorp, Thermo Fisher Scientific, Pace Life Sciences, Frontage and Nelson Labs operate large laboratory networks. Sponsors value proximity to regulators and the ability to obtain quick turnaround for submissions. Proximity to regulators and a deep pool of experienced scientists also encourage sponsors to keep critical development work within the region.
Consolidation is a defining feature of the regional market. Laboratory acquisitions, such as the purchase of medical device testing units and bioanalytical laboratories, give buyers broader service menus. Private equity investment in testing providers continues. Compliance with data integrity rules and the Drug Supply Chain Security Act adds work for manufacturers. Medical device testing for biocompatibility and sterilization validation is growing with device approvals. Competition for experienced scientists is intense, and laboratories offer training and retention programs to keep staff. Demand for medical device testing is also supported by the large installed base of manufacturers in Minnesota, Ohio and California that need rapid, repeatable studies.
⮞In August 2026, Sotera Health reported that Nelson Labs delivered second quarter revenue of USD 61.00 million. The result shows steady demand for medical device and pharmaceutical testing.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Healthcare Analytical Testing Services Market Insights
Europe is the second largest region, led by Germany, the United Kingdom, Switzerland, France and Italy. Switzerland and Germany host major pharmaceutical groups that outsource specialized testing, and the United Kingdom has a strong contract research and laboratory base. Eurofins, SGS, TÜV SÜD and Solvias are among the large providers headquartered in the region. European Medicines Agency guidelines and pharmacopeial standards shape method requirements, and laboratories invest in accreditations that satisfy several regulators at the same time. Demand is steady across biologics, generics and medical devices. Germany also benefits from a dense network of accredited laboratories that serve both pharmaceutical groups and medical technology companies across the continent.
The Medical Device Regulation increases the volume of biological evaluation and chemical characterization studies, which benefits laboratories with notified body relationships. Brexit adds testing needs for products moving between markets. Sponsors in Europe increasingly look for providers with sites in several countries to support global filings. Sustainability goals influence laboratory design, and providers invest in energy efficient instruments. Mergers among laboratories continue as large groups seek to expand life science service portfolios and add capacity near manufacturing clusters. Regulatory harmonization through ICH guidelines helps laboratories use common methods across several countries, which lowers cost and supports cross-border service models.
⮞In June 2024, the European Medicines Agency made the ICH Q14 guideline on analytical procedure development effective. The guideline encourages a structured approach to method development in European laboratories.
Asia Pacific Healthcare Analytical Testing Services Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 11.49% during 2026-2035. China, India, Japan, South Korea and Australia lead regional demand. China has a large base of contract research and testing organizations, and domestic biotechnology firms are bringing more drugs to clinical trials. India offers a large generic drug industry that needs release and stability testing to meet regulatory requirements in export markets. Japan has strict quality standards and a large pharmaceutical sector that uses outsourced services for specialized assays. Rising healthcare spending and strong government backing for biopharmaceutical research further encourage sponsors to localize analytical work near manufacturing sites.
Government programs support the growth of the sector. India has updated Schedule M good manufacturing practice rules, which require manufacturers to upgrade quality systems and testing. China has accelerated drug review and approval, increasing the number of products requiring testing. Western sponsors are placing work with Asian laboratories to reduce cost and gain access to talent. Providers such as WuXi AppTec and Pharmaron have expanded laboratory capacity, while global groups add sites in the region to serve local sponsors and multinational customers. Lower operating cost and a large pool of trained chemists also help regional providers win overflow work from sponsors in North America and Europe.
⮞In February 2025, India's Ministry of Health and Family Welfare extended the revised Schedule M compliance deadline to December 31, 2025 for manufacturers with annual turnover of Rs 250 crore or less. The rule requires smaller manufacturers to upgrade quality systems and testing.
MEA & Latin America Healthcare Analytical Testing Services Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Brazil's health regulator operates a network of accredited laboratories and requires bioequivalence studies for generic medicines, which creates steady demand for bioanalytical and quality control services. Local pharmaceutical groups and multinational manufacturers send samples to regional laboratories to meet registration requirements. Currency volatility and import dependence affect equipment costs. International providers enter through acquisitions and partnerships with local laboratories. Growth is supported by regulatory reforms that encourage local bioequivalence work and by multinational sponsors that seek regional laboratories for registration studies.
In the Middle East and Africa, Saudi Arabia and the United Arab Emirates lead demand as national health programs promote local pharmaceutical manufacturing and clinical research. The Saudi Food and Drug Authority is strengthening quality control and approval requirements, which supports growth for accredited laboratories. South Africa has an established laboratory sector serving local and regional manufacturers. Limited skilled staff and uneven regulation constrain growth in other African countries, although international donors and regulators are supporting laboratory capacity building. Investment in pharmacopeial standards and laboratory accreditation across the Gulf states is expected to improve confidence in locally generated analytical data over the forecast period.
⮞In October 2025, the Saudi Food and Drug Authority launched the Saudi Pharmacopoeia, an official reference for quality specifications and analytical methods for medicines and vaccines. The reference supports local manufacturers and raises demand for accredited testing in the region.
Market Dynamics:
Growth Drivers: Biologics Complexity and Outsourcing Demand
The growing complexity of biologics, biosimilars and advanced therapies is the main driver of the market. These products need extensive characterization, potency testing and comparability studies that require advanced instruments and specialized expertise. Sponsors find it more efficient to use external laboratories than to build capacity for each technology. Large pipelines of monoclonal antibodies, antibody drug conjugates and cell and gene therapies create steady demand for method development, validation and release testing across the entire product life cycle. Regulators also encourage earlier and deeper characterization of every molecule, which adds tests to each program and lifts average spending per drug candidate over time.
Outsourcing trends reinforce this demand. Biotechnology companies rely on external partners because they lack in-house laboratories, and large pharmaceutical groups outsource peaks of work to maintain flexibility. Regulatory expectations for validated methods and data integrity favor providers with strong quality systems. Growth in clinical trial activity increases sample volumes, and the expansion of personalized medicine adds demand for biomarker assays. Together these factors support double-digit growth for many providers and encourage investment in new laboratory capacity. Many mid-sized sponsors now prefer variable-cost outsourcing to fixed laboratory investment, which protects their capital for clinical development and commercial launch.
⮞In July 2026, Medpace reported a backlog of USD 3.01 billion as of June 30, 2026. The backlog shows the strength of clinical development activity that drives outsourced testing.
Restraints: Compliance Burden and Shortage of Skilled Scientists
Regulatory compliance imposes heavy cost and complexity on laboratories. Good laboratory practice, good manufacturing practice and data integrity rules require audited systems, validated software and extensive documentation. Regulators have expanded their expectations for impurities, including nitrosamines, which require sensitive methods and frequent reviews of product risk. Each new guideline demands method changes and retesting. Smaller laboratories struggle to meet these requirements and may lose business to larger providers. Frequent revisions of pharmacopeial chapters and agency guidance also force laboratories to revalidate methods, which interrupts schedules and adds unplanned cost.
A shortage of skilled scientists is a second restraint. Mass spectrometry, cell biology and regulatory experts are in short supply, and wages are rising. Laboratories must invest in training and retention to keep quality high. High capital cost for next-generation instruments also limits expansion, particularly for regional providers. Intellectual property disputes in outsourced studies and pricing pressure from large sponsors further reduce margins. These constraints can slow capacity growth even when demand is strong. Utilization risk adds to these pressures because laboratories must invest ahead of demand, and a delay in client programs can leave expensive instruments underused for months.
⮞In September 2024, the U.S. Food and Drug Administration issued Revision 2 of its guidance on control of nitrosamine impurities in human drugs, as summarized by Element Materials Technology. The guidance shows the growing regulatory workload for testing laboratories.
Opportunities: Cell and Gene Therapy Testing and Medical Device Characterization
Cell and gene therapy testing offers a significant opportunity. These products require viral vector characterization, potency assays, sterility and mycoplasma testing, and genomic analysis, and many sponsors lack the specialized facilities. Laboratories that build dedicated capacity can secure long-term relationships with developers. Regulators have approved a growing number of advanced therapies, and clinical pipelines continue to expand. Demand is also rising for rapid release methods because many therapies have short shelf lives. Sponsors that develop gene-edited and viral vector products often look for partners that can also support process characterization, which adds to the available project value.
Medical device characterization is a second opportunity. Device makers must provide chemical characterization, biological evaluation and extractables data under updated international standards. Combination products that join a drug and a device require both sets of data. Laboratories with expertise in both areas can offer integrated programs. Consolidation among providers is creating broader service networks, and sponsors prefer partners that can deliver testing across several product categories under one contract. Digital laboratory systems and automated workflows can also help providers lower turnaround time, and sponsors increasingly pay a premium for faster and more transparent data delivery.
⮞In July 2026, Thermo Fisher Scientific reported second quarter revenue of USD 6.69 billion in its Laboratory Products and Biopharma Services segment. The scale of the segment shows the breadth of services available to drug developers.
Recent Developments:
-
In July 2026, SGS announced the acquisition of Keystone Bioanalytical, a U.S. provider of bioanalytical testing for pharmaceutical and biotech clients, with a focus on small molecule and biomarker projects. The acquisition strengthens SGS's life science services in a key outsourced testing category.
-
In July 2026, Eurofins agreed to buy Element Materials Technology's North American life sciences testing business for an enterprise value of USD 400 million. The business operates 27 laboratories and facilities with about 750 employees, and closing is expected in the fourth quarter of 2026.
-
In March 2026, Frontage Laboratories completed the acquisition of Teddy Clinical Research Laboratory in Shanghai. The laboratory has supported more than 1,500 clinical trials and expands Frontage's central laboratory capacity in China.
-
In January 2026, NAMSA completed its acquisition of select assets of Labcorp's Early Development medical device testing business. The deal enlarges NAMSA's U.S. footprint, and the company serves more than 3,000 medical technology firms.
Healthcare Analytical Testing Services Market Key Players:
-
Eurofins Scientific SE
-
SGS SA
-
Charles River Laboratories International, Inc.
-
Labcorp Holdings Inc.
-
WuXi AppTec Co., Ltd.
-
Thermo Fisher Scientific Inc.
-
Pace Life Sciences (Pace Analytical Services)
-
Frontage Laboratories, Inc.
-
Pharmaron Beijing Co., Ltd.
-
NAMSA
-
Nelson Labs (Sotera Health Company)
-
ALS Limited
-
TÜV SÜD AG
-
Solvias AG
-
Alcami Corporation
Healthcare Analytical Testing Services Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.38 Billion |
| Market Size by 2035 | USD 34.30 Billion |
| CAGR | CAGR of 9.87% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Bioanalytical Testing, Method Development and Validation, Stability Testing, Raw Material Testing, Microbial Testing, Extractables and Leachables Testing, and Other Services) • By End User (Pharmaceutical and Biopharmaceutical Companies, CDMOs and CROs, Medical Device Companies, and Academic and Research Institutes) • By Technology (Chromatography-Based Testing, Mass Spectrometry, Molecular and Immunoassay Testing, Spectroscopy, Cell-Based Bioassays, and Other Technologies) • By Development Phase (Preclinical and Phase I, Phase II, Phase III, and Commercial and Quality Control Release) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Eurofins Scientific SE, SGS SA, Charles River Laboratories International, Inc., Labcorp Holdings Inc., WuXi AppTec Co., Ltd., Thermo Fisher Scientific Inc., Pace Life Sciences (Pace Analytical Services), Frontage Laboratories, Inc., Pharmaron Beijing Co., Ltd., NAMSA, Nelson Labs (Sotera Health Company), ALS Limited, TÜV SÜD AG, Solvias AG, Alcami Corporation |

Frequently Asked Questions
Key players include Eurofins Scientific, SGS, Charles River Laboratories, Labcorp, WuXi AppTec, Thermo Fisher Scientific, Pace Life Sciences, Frontage Laboratories, Pharmaron, NAMSA, Nelson Labs, ALS Limited, TÜV SÜD, Solvias and Alcami.
Key opportunities include cell and gene therapy testing, medical device chemical characterization, extractables and leachables studies and expansion of capacity in Asia Pacific.
The growing complexity of biologics and advanced therapies, together with outsourcing by drug developers, is the main growth factor.
By Service Type, the Bioanalytical Testing segment dominated the market in 2025 with an estimated 29.88% share, supported by pharmacokinetic and immunogenicity studies for new drugs.
North America dominated the market with a share of 40.74% in 2025, driven by a large drug development pipeline, a mature laboratory sector and strict regulatory standards.
