
Electric Vehicle Battery Recycling Market Report Scope & Overview:
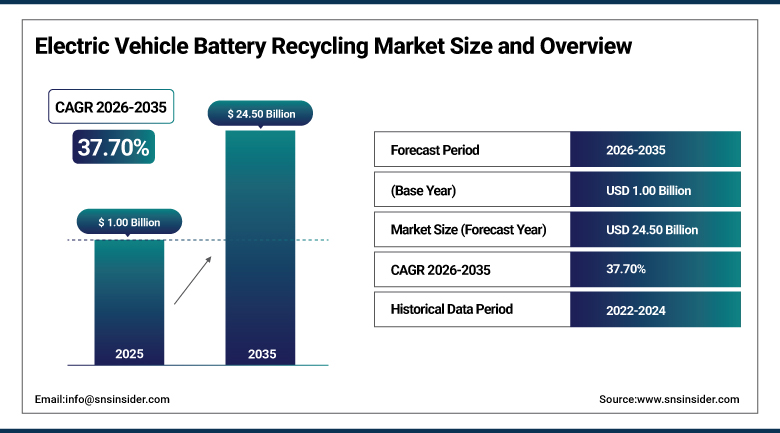
The Electric Vehicle Battery Recycling Market was valued at USD 1.00 Billion in 2025 and is expected to reach USD 24.50 Billion by 2035, growing at a CAGR of 37.70% from 2026–2035.
Electric vehicle battery recycling is the systematic recovery of critical minerals, including lithium, cobalt, nickel, and manganese, from spent lithium-ion traction batteries, transforming end-of-life liabilities into circular resource streams rather than letting them sit as waste. Advanced recycling processes can now recover up to 95% of these valuable metals, dramatically reducing the environmental impact associated with traditional raw material extraction while giving automakers a genuine alternative to newly mined critical minerals. The industry is entering a decisive commercialization phase, unlocking substantial opportunities for automakers, energy providers, and investors focused on critical material security, as the first large wave of EVs sold roughly a decade ago finally begins reaching end-of-life in meaningful volume.
Glencore acquired Li-Cycle in August 2025, a deal the mining giant itself called “game-changing,” combining Li-Cycle's proven North American and European hydrometallurgical technology with Glencore's global refining network and capital base. Two months later, Redwood Materials closed a $350 million Series E funding round that included an investment from NVIDIA's venture arm, NVentures, a genuinely unusual pairing that reflects how battery recycling has quietly become adjacent to the AI boom: retired EV batteries recovered rather than recycled outright are increasingly finding a second life powering the grid-scale energy storage that data centers now depend on.
To Get more information Electric Vehicle Battery Recycling Market - Request Free Sample Report
Electric Vehicle Battery Recycling Market Trends
-
Battery recycling passports embedded in each pack, recording chemistry, cycle count, and disassembly instructions, continue accelerating sorting efficiency for recyclers
-
Second-life energy storage applications continue expanding, as retired EV batteries retaining more than half their original capacity find new use in grid-scale storage before eventual material recovery
-
Hydrometallurgical processing continues gaining share over traditional pyrometallurgical methods, driven by the need to extract a wider range of materials while lowering energy consumption and environmental impact
-
Standardized battery removal points in new EV designs continue reducing dismantling labor and improving recycling economics across the industry
-
Industry consolidation continues accelerating as mining and resource companies acquire specialized battery recyclers to secure long-term critical mineral supply chains
-
Growing automaker partnerships with recyclers continue integrating battery recovery directly into vehicle supply chains rather than treating recycling as an external, third-party service
U.S. Electric Vehicle Battery Recycling Market Outlook
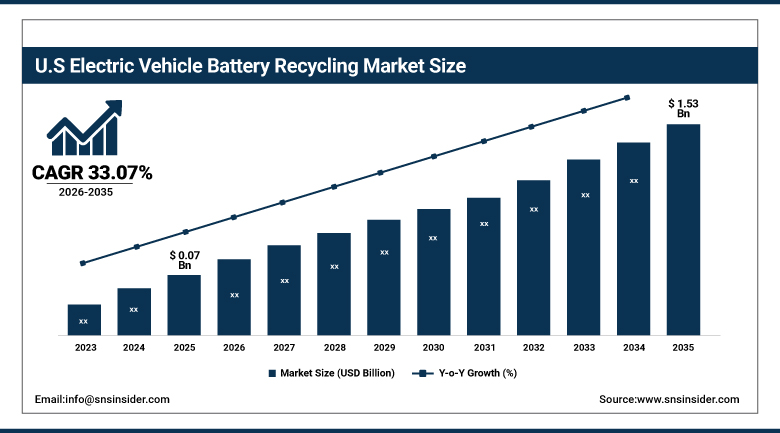
The U.S. Electric Vehicle Battery Recycling Market was valued at approximately USD 0.07 Billion in 2025 and is expected to reach approximately USD 1.53 Billion by 2035, growing at a CAGR of approximately 33.07%.
The U.S. market remains at an early stage relative to Asia Pacific, though it is accelerating quickly as the first large cohorts of EVs sold roughly a decade ago begin reaching end-of-life in meaningful volume. In the United States, where just a small share of raw and component materials for EV batteries are currently produced domestically, recyclers believe they can meet the moment by recovering critical minerals directly from retired batteries rather than depending entirely on imported or newly mined material. Major automotive manufacturers, including Ford, Toyota, Volkswagen, BMW, and General Motors, have partnered directly with domestic recyclers to integrate battery recovery into their own supply chains, reflecting growing industry recognition that circular material sourcing is becoming a genuine strategic priority rather than a purely environmental gesture.
Redwood Materials launched Redwood Energy in June 2025, a new business line that repurposes retired EV batteries retaining more than half their original capacity into grid-scale energy storage systems serving AI data centers, industrial facilities, and grid-balancing applications rather than immediately shredding them for raw materials. Major automakers including Ford, Toyota, Volkswagen, BMW, and General Motors have already partnered with the American company, illustrating how U.S. battery recycling firms are increasingly capturing value at two separate stages of a battery's life, first through second-use energy storage, then through eventual material recovery, rather than treating recycling as a single, one-time event.
Electric Vehicle Battery Recycling Market Segment Analysis
-
By Battery Chemistry, the Lithium-ion segment dominated the Electric Vehicle Battery Recycling Market with approximately 60.00% share in 2025, while the Others (including LFP-specific and emerging chemistries) segment is the fastest growing with a CAGR of approximately 42.60%.
-
By Source, the Production Scrap segment dominated the Electric Vehicle Battery Recycling Market with approximately 58.60% share in 2025, while the End-of-Life segment is the fastest growing with a CAGR of approximately 44.20%.
-
By Process, the Pyrometallurgical segment dominated the Electric Vehicle Battery Recycling Market with approximately 54.20% share in 2025, while the Hydrometallurgical segment is the fastest growing with a CAGR of approximately 43.80%.
-
By Application, the Passenger Cars segment dominated the Electric Vehicle Battery Recycling Market with approximately 68.40% share in 2025, while the Energy Storage Systems segment is the fastest growing with a CAGR of approximately 39.30%.
By Battery Chemistry, Lithium-ion dominates, emerging chemistries grow fastest
Lithium-ion held the large majority of the battery-chemistry segment in 2025, reflecting the chemistry's overwhelming dominance across the global electric vehicle fleet currently reaching end-of-life or generating production scrap during manufacturing. That fleet-wide dominance keeps lithium-ion the anchor chemistry across the broader recycling market, since the overwhelming majority of batteries entering the recycling stream today are lithium-ion regardless of specific cathode formulation.
Emerging and other chemistries, including lithium iron phosphate formulations, are growing fastest as increasing adoption of LFP batteries in EVs, due to their cost-effectiveness, safety, and longer life cycle than other lithium-based chemistries, continues expanding the need for efficient and sustainable recycling solutions tailored to this specific chemistry. Recyclers are actively developing scaling processes to recover lithium, iron, and phosphate from used LFP batteries, reinforcing this above-average growth trajectory as LFP-powered EV adoption continues rising.
By Source, Production Scrap dominates, End of Life grows fastest
Production scrap held the largest share of the source segment in 2025, reflecting the reality that most electric vehicles currently on the road remain relatively young and haven't yet reached end-of-life, while manufacturing defects and rejected cells during battery production generate a steady, more immediately available recycling feedstock. That production-stage availability keeps production scrap the dominant source category across the current market, even as the broader industry anticipates a coming shift.
End of life battery volume is growing fastest as millions of electric vehicles reach end-of-life globally, with industry estimates suggesting that beginning around 2025, hundreds of thousands of tons of batteries will begin aging out of EV applications annually, several times the volume aging out just a few years earlier. That structural shift toward genuine end-of-life volume continues reinforcing this above-average growth trajectory relative to the broader, production-scrap-dominated source mix.
By Process, Pyrometallurgical dominates, Hydrometallurgical grows fastest
Pyrometallurgical processing held the largest share of the process segment in 2025, remaining the more established, historically proven smelting-based recovery method that many of the industry's largest and longest-operating recyclers built their original processing capacity around. That established infrastructure and processing track record keeps pyrometallurgical methods the dominant process category across the broader market, particularly among vertically integrated mining and metals companies.
Hydrometallurgical processing is growing fastest due to the increasing need to extract a wider range of materials, including copper, lithium, silver, nickel, and zinc, from EV batteries, alongside the growing need to lower energy consumption, reduce waste, and minimize the environmental impact of recycling processes. That combination of broader material recovery and lower environmental footprint continues reinforcing this above-average growth trajectory relative to the broader, pyrometallurgical-dominated process mix.
By Application, Passenger Cars dominates, Energy Storage Systems grows fastest
Passenger cars held the largest share of the application segment in 2025, as millions of passengers EVs reached end-of-life globally, dwarfing commercial and stationary battery sources by sheer volume given how much larger the global passenger EV fleet is relative to electric buses, vans, and stationary storage installations. That fleet-scale dominance keeps passenger cars the anchor application across the broader electric vehicle battery recycling market.
Energy storage systems are growing fastest as retired EV batteries increasingly find a genuine second life in grid-scale storage applications before eventual material recovery, rather than being immediately shredded and processed for raw materials. Growing demand for grid-balancing and AI data center power infrastructure continues reinforcing this above-average growth trajectory relative to the broader, passenger-car-dominated application mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
47.60% |
|
North America |
United States |
78.40% |
|
Europe |
Germany |
26.20% |
|
Latin America |
Brazil |
34.80% |
|
Middle East & Africa |
UAE |
28.60% |
Asia Pacific Electric Vehicle Battery Recycling Market Insights
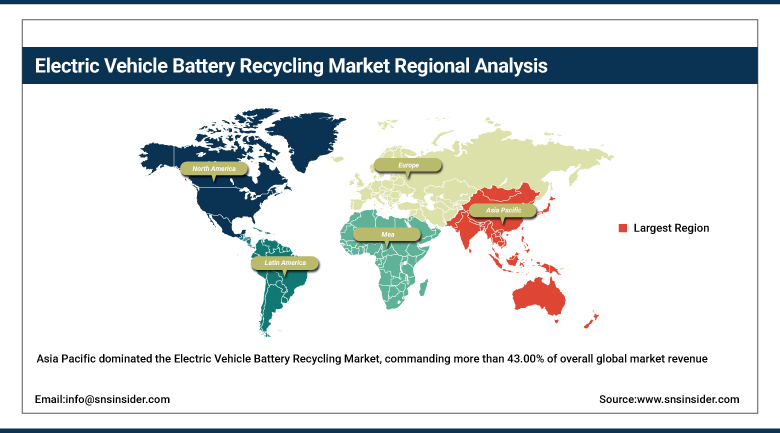
Asia Pacific dominated the Electric Vehicle Battery Recycling Market, commanding more than 43.00% of overall global market revenue, and is also expected to register the fastest regional growth through 2035. The region's massive electric vehicle manufacturing base, expansive domestic EV fleet, and rapidly maturing recycling infrastructure across China, Japan, and South Korea all continue reinforcing this leading and accelerating position.
China's dominant position in global EV manufacturing and its correspondingly large and fast-aging domestic EV fleet give the region substantial baseline demand, with domestic recyclers like GEM Co., Ltd. and Contemporary Amperex Technology scaling processing capacity rapidly to keep pace. Japan and South Korea represent more mature, technology-forward markets with established recycling infrastructure, while Southeast Asian markets continue following a similar EV-fleet-driven growth trajectory as regional electric vehicle adoption expands.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Electric Vehicle Battery Recycling Market Insights
North America represents an early-stage but rapidly accelerating electric vehicle battery recycling market, with the United States accounting for the large majority of regional demand as domestic recyclers race to build processing capacity ahead of the coming wave of end-of-life battery volume. Major automotive manufacturer partnerships with domestic recyclers continue integrating battery recovery directly into vehicle supply chains across the region.
Canada contributes additional demand through its own growing EV adoption and mining sector interest in battery material recovery, while Mexico's market remains largely nascent, dependent on recycling infrastructure and technology sourced from its northern neighbor. Cross-border supply relationships tie much of North American demand together, with major U.S.-based recyclers typically serving the broader region through expanding facility networks.
Europe Electric Vehicle Battery Recycling Market Insights
Europe is an established market for electric vehicles' battery recycling characterized by EU battery regulations requiring minimum recycled content and collections throughout the most significant economies within the region. Germany leads regional demand because it has a considerable automotive manufacturing industry along with advanced battery recycling facilities operated by Umicore.
The UK and France also represent regions that provide significant volumes of batteries. Both countries have growing fleets of EVs along with growing investments in domestic battery recycling capacity. The innovation introduced by Umicore in the form of pyro-hydro process for recovery of copper, cobalt, nickel, and lithium into battery-grade materials is continuously cementing its technological leadership within the global market.
MEA & Latin America Electric Vehicle Battery Recycling Market Insights
The Middle East and Africa represent a smaller but strategically developing electric vehicle battery recycling market, with the UAE driving demand through growing EV adoption and broader economic diversification investment tied to sustainable mobility goals. Growth elsewhere in the region remains tied closely to the pace of broader EV fleet expansion and recycling infrastructure development.
Latin America is a growing market led by Brazil, where expanding EV adoption and substantial domestic mining sector interest in battery material recovery continue driving early-stage recycling infrastructure investment. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing EV fleets and mining industry involvement in critical mineral recovery.
Market Dynamics
Growth Drivers: Surging EV adoption and end-of-life battery volume fueling demand
Surging electric vehicle adoption and expanding volume of end-of-life batteries are one of the clearest forces behind rising electric vehicle battery recycling demand, as the rapid growth in global EV manufacturing continues generating both production scrap and, increasingly, genuine end-of-life battery volume that requires processing. Rise in demand for zero-emission vehicles continues reinforcing this demand base, since every additional EV sold today represents a future recycling feedstock unit.
The active role of government in the electric vehicle industry adds a second major driver, as regulatory bodies worldwide implement recycled-content mandates, collection targets, and critical mineral security policies that directly reinforce battery recycling infrastructure investment. Growing need to address the shortage of critical raw materials, combined with the substantial cost and environmental footprint of newly mined lithium, cobalt, and nickel, continues reinforcing this demand base across nearly every major EV manufacturing market.
Restraints: Immature collection infrastructure and processing cost challenges limiting broader scale
Immature battery collection infrastructure remains a genuine restraint, since a smaller share of end-of-life batteries currently undergo formal recycling relative to the total volume reaching end-of-life globally, reflecting gaps in collection logistics and consumer awareness about proper battery disposal channels. That collection gap limits how quickly recyclers can secure the feedstock volume needed to justify continued capacity expansion.
High processing costs and technical complexity add a further restraint, since safely dismantling, discharging, and processing lithium-ion battery packs requires specialized equipment and expertise that smaller operators may struggle to develop at commercially viable scale. Variability in battery chemistry, form factor, and condition across different automaker designs continues complicating standardized, cost-efficient processing across the broader industry.
Opportunities: Second-life energy storage and vertical integration widening addressable demand
Second-life energy storage applications present a significant growth opportunity, as retired EV batteries retaining substantial remaining capacity increasingly find genuine value repurposed into grid-scale storage for data centers and industrial facilities before eventual material recovery, capturing value at two distinct stages of a battery's life rather than one. Companies that build strong second-life battery repurposing capability are positioned to capture additional revenue streams beyond pure material recycling.
Vertical integration between mining and resource companies and specialized battery recyclers presents a second significant opportunity, as combining upstream refining capability with downstream recycling technology creates a more complete, capital-efficient critical mineral supply chain. Companies that successfully integrate recycling technology with existing refining infrastructure are positioned to capture disproportionate growth as automakers increasingly prioritize secure, traceable critical mineral sourcing.
Recent Developments:
-
In August 2025, Glencore completed its acquisition of Li-Cycle Holdings Corp., combining Li-Cycle's hydrometallurgical recycling technology with Glencore's global refining network.
-
In October 2025, Redwood Materials closed a $350 million Series E funding round, with participation from NVIDIA's venture investment arm, NVentures.
-
In November 2025, Redwood Materials began recovering critical battery materials at its South Carolina facility, claiming a 95% recovery rate for materials it processes.
-
In 2025, Li-Cycle continued expanding its “Spoke and Hub” recycling network across North America and Europe, targeting 81,000 tonnes of annual processing capacity.
Electric Vehicle Battery Recycling Market Key Players
-
Umicore NV/SA
-
Li-Cycle Holdings Corp. (Glencore)
-
Redwood Materials, Inc.
-
American Battery Technology Company
-
Neometals Ltd.
-
Recyclico Battery Materials Inc.
-
Accurec Recycling GmbH
-
Contemporary Amperex Technology Co., Limited (CATL)
-
Ecobat
-
Eramet
-
Fortum Corporation
-
GEM Co., Ltd.
-
Glencore plc
-
Battery Solutions LLC
-
East Penn Manufacturing Company
-
Retriev Technologies LLC
-
Call2Recycle, Inc.
-
Exide Technologies
-
Gravita India Ltd.
-
Cirba Solutions
Electric Vehicle Battery Recycling Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.00 Billion |
| Market Size by 2035 | USD 24.50 Billion |
| CAGR | CAGR of 37.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Battery Chemistry (Lithium-ion, Lead Acid, Nickel, Others), • by Source (Production Scrap, End of Life) • by Process (Pyrometallurgical, Hydrometallurgical, Others) • by Application (Passenger Cars, Electric Buses, Energy Storage Systems, Vans, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Umicore NV/SA, Li-Cycle Holdings Corp. (Glencore), Redwood Materials, Inc., American Battery Technology Company, Neometals Ltd., Recyclico Battery Materials Inc., Accurec Recycling GmbH, Contemporary Amperex Technology Co., Limited (CATL), Ecobat, Eramet, Fortum Corporation, GEM Co., Ltd., Glencore plc, Battery Solutions LLC, East Penn Manufacturing Company, Retriev Technologies LLC, Call2Recycle, Inc., Exide Technologies, Gravita India Ltd., Cirba Solutions |
Frequently Asked Questions
Opportunities include second-life energy storage applications capturing value across two stages of a battery's life and vertical integration between mining companies and specialized battery recyclers building complete critical mineral supply chains.
Growth is driven by surging electric vehicle adoption and expanding volume of end-of-life batteries, the active role of government in the electric vehicle industry, and the growing need to address critical raw material shortages.
Lithium-ion dominates by battery chemistry with approximately 60.00% share, Production Scrap dominates by source with roughly 58.60% share, Pyrometallurgical dominates by process with about 54.20% share, and Passenger Cars dominates by application with approximately 68.40% share; emerging chemistries, End of Life source, Hydrometallurgical process, and Energy Storage Systems are the fastest-growing segments within their respective categories.
Asia Pacific is the largest regional market with more than 43.00% share, led by China, and is also the fastest-growing region through 2035.
