
Automotive Brake Linings Market Report Scope & Overview:
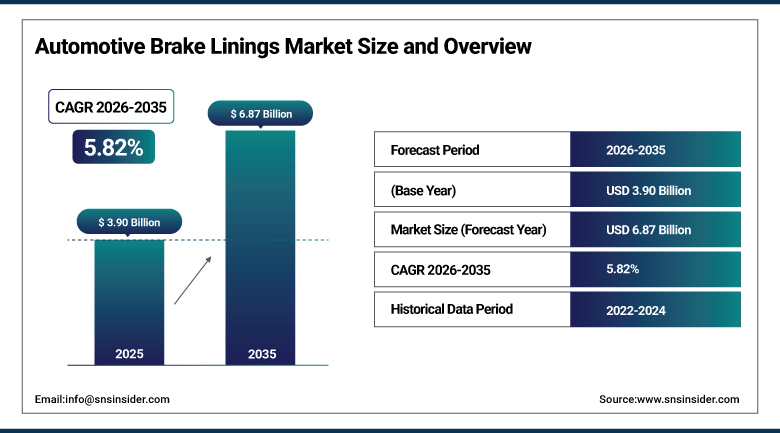
The Automotive Brake Linings Market was valued at USD 3.90 Billion in 2025 and is expected to reach USD 6.87 Billion by 2035, growing at a CAGR of 5.82% from 2026-2035.
Automotive brake linings are the friction component used on brake pads or brake shoes for converting kinetic energy of automobiles into heat energy by coming in contact with the rotors and drums respectively. They are among the most important safety components of any vehicle. The market keeps shifting its focus toward development of non-asbestos organic and ceramic friction materials rather than asbestos and semi-metallic friction materials because of increasing health and environmental regulation issues. Factors such as increasing automobile production, regular and advancements in friction materials technology that provide optimum results in terms of efficiency, performance, and longevity drive this market. Growth of electric vehicles reduces demand for friction linings due to their regeneration capability while they are being developed for electric automobiles.
In November 2025, Brembo launched its XTRA Ceramic Severe Duty brake pads in AAPEX. The brake pads were meant for pickups, SUVs, commercial fleet, and police cars in North America. The brake pads do not have any copper and will be available in North America in early 2026. They are expected to have better stopping power, heat resistance, noise reduction, and more durability compared to other brake pads. The product launch has expanded Brembo’s braking products in the aftermarket.
To Get more information Automotive Brake Linings Market - Request Free Sample Report
Automotive Brake Linings Market Trends
- Rising adoption of ceramic friction materials offering lower noise, dust, and improved durability.
- Growing development of copper-free brake linings meeting tightening environmental water quality regulations.
- Expanding demand for corrosion-resistant, low-dust linings engineered specifically for electric vehicles.
- Increasing OEM and aftermarket collaboration on brake dust emissions reduction technology.
- Rising premiumisation of aftermarket brake pad lines targeting expanded late-model vehicle coverage.
- Growing industry consolidation as leading manufacturers acquire regional friction material producers.
U.S. Automotive Brake Linings Market Overview
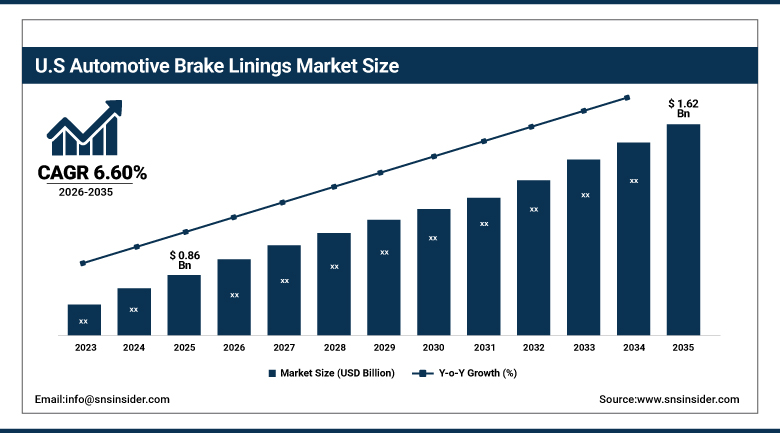
The U.S. Automotive Brake Linings Market was valued at USD 0.86 Billion in 2025 and is expected to reach USD 1.62 Billion by 2035, growing at a CAGR of 6.60% from 2026-2035.
The U.S. Automotive Brake Linings Market benefits from strong aftermarket replacement demand and expanding commercial fleet activity that continues to drive brake lining consumption across original equipment and replacement channels. Leading manufacturers maintain extensive research and development and manufacturing footprints within the country, continuously expanding ultra-premium ceramic brake pad coverage to serve broad range of late-model passenger, luxury, and commercial vehicles. Regulatory pressure to reduce copper and heavy metals in brake friction material continues to push manufacturers toward reformulated, environmentally compliant linings, while rising electric vehicle adoption is creating demand for corrosion-resistant, low-dust products suited to regenerative braking systems. Continued growth in vehicle miles travelled and fleet utilisation is expected to sustain steady replacement demand through the forecast period.
In May 2025, Akebono Brake Corporation expanded its Ultra-Premium Disc Brake Pad portfolio by introducing new part numbers across its ProACT, EURO, and Severe Duty product lines. The expansion increased application coverage for more than 7 million additional vehicles, strengthening product availability across passenger, luxury, and commercial vehicle segments. The broader portfolio enhances aftermarket compatibility and provides repair professionals with additional replacement options designed for diverse braking requirements. The development reinforces Akebono’s focus on expanding coverage within the North American automotive aftermarket.
Automotive Brake Linings Market Segment Analysis
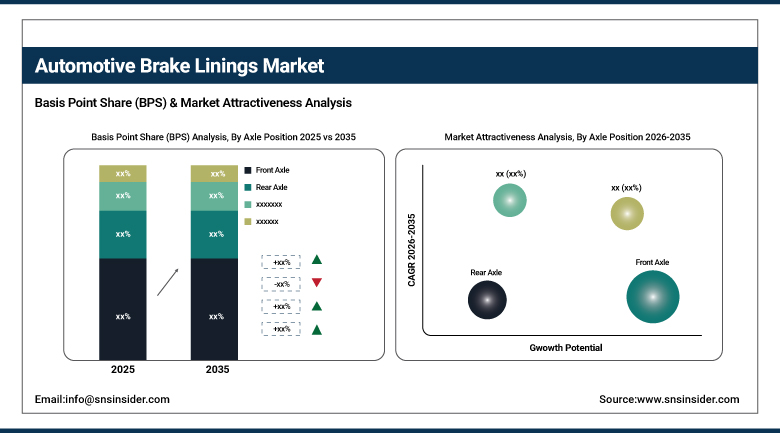
- By Axle Position, the Front-Axle segment dominated the market with a 56.60% share in 2025, while the Rear-Axle segment is the fastest growing with a CAGR of 6.60% during 2026-2035.
- By Material, the Non-Asbestos Organic segment dominated the market with a 47.60% share in 2025, while the Ceramic segment is the fastest growing with a CAGR of 7.20% during 2026-2035.
- By Vehicle Type, the Passenger Cars segment dominated the market with a 57.60% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of 6.40% during 2026-2035.
- By Brake Type, the Disc Brakes segment dominated the market with a 62.60% share in 2025, while the Disc Brakes segment is the fastest growing with a CAGR of 6.80% during 2026-2035.
By Axle Position, Front-Axle Dominates the Market and Rear-Axle Grows Fastest
Front-axle linings dominated the market in 2025. Front brakes handle the majority of a vehicle's stopping force during deceleration due to weight transfer under braking, causing front linings to wear faster and require more frequent replacement than rear components, sustaining front-axle's position as the largest axle position category across the broader brake linings market.
Rear-axle linings are projected to be the fastest-growing axle position over the forecast period. Rising adoption of four-wheel disc brake systems across a broader range of vehicle segments, combined with growing use of electronic parking brake systems that integrate directly with rear caliper assemblies, continues to expand replacement demand for rear-axle linings relative to the broader front-axle-dominated axle position mix.
By Material, Non-Asbestos Organic Dominates the Market and Ceramic Grows Fastest
Non-asbestos organic materials dominated the market in 2025. These formulations continue to eliminate the carcinogenic fibres that defined legacy asbestos linings while delivering reliable, cost-effective braking performance suited to the majority of everyday passenger and light commercial vehicle applications, sustaining non-asbestos organic's position as the largest material category across the broader market.
Ceramic materials are projected to be the fastest-growing material type over the forecast period. Growing consumer taste for luxury cars with high-end brake systems is expected to fuel the uptake of ceramic pads because they have better thermal resistance and quieter operations as well as longevity compared to the traditional organic and semi-metallic pads, hence enabling ceramic pads to experience above-market growth going forward.
By Vehicle Type, Passenger Cars Dominates the Market and Commercial Vehicles Grows Fastest
Passenger cars dominated the market in 2025. The sheer global production and ownership volume of passenger vehicles continues to anchor this vehicle type as the largest source of brake lining demand, reinforced by sustained replacement cycles across a vehicle parc that spans both routine commuter vehicles and premium, technology-forward models.
Commercial vehicles are projected to be the fastest-growing vehicle type over the forecast period. Rising e-commerce-driven freight volumes and expanding logistics fleets continue to increase vehicle utilisation and brake wear rates, and manufacturers continue developing heavy-duty friction materials specifically engineered for the higher thermal loads and extended service intervals commercial fleet operators require.
By Brake Type, Disc Brakes Dominates the Market and Disc Brakes Grows Fastest
In 2025, disc brakes had dominated the market by brake type. This system is now the norm for braking systems of most cars and small vans due to its better cooling ability and stopping power compared to drum brakes, which explains why the category of disc brakes has remained the biggest brake type market segment.
Disc brakes are also expected to grow fastest over the forecast period. Continued phase-out of drum brakes across emerging markets, combined with rising adoption of four-wheel disc configurations in vehicle segments that previously relied on rear drum brakes, continues to reinforce disc brakes' already dominant position even further relative to the broader brake type mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
82.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Automotive Brake Linings Market Insights
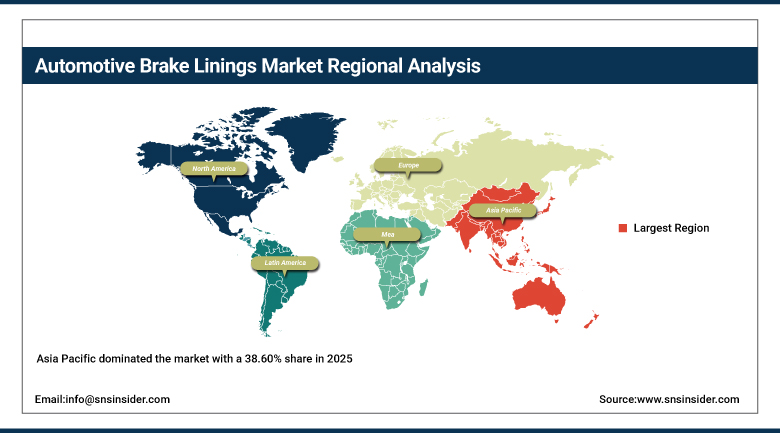
Asia Pacific dominated the market with a 38.60% share in 2025, supported by its position as the world’s largest vehicle production base and substantial friction material manufacturing capacity across China, Japan, and South Korea. The region is endowed with well-developed supply chain networks for automobiles which cater to original equipment applications as well as aftermarket applications. This demand is generated by China via its automobile manufacturing activities, consumption of automobiles, and export of automobiles. Japan provides automotive technology and component manufacturing.
South Korea strengthens regional demand through its major vehicle manufacturers and automotive component ecosystem. India is also becoming an increasingly important contributor as its expanding vehicle parc, rising vehicle ownership, and growing automotive manufacturing base support additional aftermarket demand for brake components and friction materials.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Brake Linings Market Insights
North America is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 6.60%, supported by strong aftermarket replacement demand, expanding commercial vehicle fleets, and continued introduction of premium brake pad products. The United States is the major contributor to demand within the region, due to its large vehicle parc, constant need for replacement, and rising commercial fleets activity.
Preference for better-performing, less-noisy, and long-lasting braking technologies is another factor driving the demand in the region. Canada plays an important role through its automotive aftermarket, and Mexico through vehicle manufacturing and assembly activities that are linked to the American automotive sector. Together, these factors are expected to support sustained development of the North American brake pad market throughout the forecast period.
Europe Automotive Brake Linings Market Insights
Europe holds a significant share of the global market, supported by Germany’s substantial automotive manufacturing base, advanced engineering capabilities, and high vehicle ownership rates. These factors sustain consistent demand for brake linings across original equipment and aftermarket applications. In addition to this, the UK, France, and Italy add another dimension to the regional demand owing to well-established automotive component manufacturing, sizeable fleet, and usage of friction materials.
Regulations and measures for brake emissions from Europe have also been adding impetus for development of friction materials free from copper and other emissions. The growing focus on safety, braking, and environmental concerns is driving technology development in the regional market for brake linings. Future investments in automobile parts are anticipated to drive regional demand during the forecast period.
MEA & Latin America Automotive Brake Linings Market Insights
The Middle East & Africa region is supported by growing vehicle ownership, expanding automotive aftermarket infrastructure, and increasing demand for replacement braking components across the United Arab Emirates and Saudi Arabia. Increased vehicle imports, transport operations, and automobile service growth will play an important role in determining the demand for brake lining in the region.
In Latin America, the largest demand is seen in Brazil, as the country’s large vehicle parc and established manufacturing industry along with the developing aftermarket infrastructure help drive steady demand for brake lining in the country. The additional demand is generated in the region through Mexico owing to the large vehicle manufacturing base in the country and close ties with the supply chain of automobiles.
Market Dynamics
Growth Drivers: Vehicle Production Growth and Safety Regulation
Increasing vehicle production stands as the primary growth driver, as rising global vehicle output across both passenger and commercial segments continues to expand the installed base requiring both original equipment and eventual aftermarket brake lining replacement. Growing vehicle parc size worldwide continues to sustain recurring replacement demand regardless of new vehicle production cycles.
Stringent safety regulations and advancing materials technology represent a second major driver, as regulatory emphasis on reliable stopping performance continues to require durable, high-performance brake linings across every vehicle segment. Continued innovation in ceramic and low-dust friction materials further reinforces sustained demand as manufacturers compete on noise reduction, longevity, and environmental compliance.
Restraints: Regenerative Braking Adoption and Raw Material Costs
Increased use of regenerative braking systems in electric and hybrid cars is an actual constraint, since these braking systems minimize the dependence on friction brakes for slowing down the car and therefore extend the lifespan of brake linings in electrified cars as opposed to those run on combustion engines.
Raw material cost volatility presents a further restraint, as friction material formulations depend on a range of specialty compounds and metals whose pricing can fluctuate meaningfully, adding cost pressure that manufacturers must balance against competitive aftermarket pricing expectations across price-sensitive vehicle segments.
Opportunities: Ceramic Material Innovation and Electric Vehicle-Specific Products
Further developments in ceramic and copper-free friction materials present an important avenue, given the fact that those producers who are able to offer quieter, dust free, and long-lasting products will have an edge, since more customers and fleets are ready to pay for these benefits.
Development of electric vehicle-specific brake linings offers a further avenue for growth, as manufacturers that can deliver corrosion-resistant, low-dust products engineered for the unique wear profile regenerative braking creates are positioned to capture demand from a rapidly expanding electric vehicle parc requiring genuinely differentiated friction material solutions.
Recent Developments:
- 2026: Continental AG advanced intelligent brake-system technologies supporting electrification and automated driving, including modular brake architectures and its second-generation MK C2 brake-by-wire system.
- 2026: General Motors Company expanded engineering activities for next-generation braking systems, including development, integration, supplier management, and production launch of advanced brake components for upcoming vehicle programs.
- 2026: TMD Friction introduced a new low-dust, long-life brake lining series designed for original equipment manufacturers and premium aftermarket applications, targeting cleaner, more durable braking components for urban and luxury vehicle segments.
Automotive Brake Linings Market Key Players are:
- Akebono Brake Industry Co., Ltd.
- Aisin Corporation
- Brembo S.p.A.
- Continental AG
- Tenneco Inc.
- General Motors Company
- Japan Brake Industrial Co., Ltd.
- Meritor, Inc.
- SGL Carbon SE
- TMD Friction Holdings GmbH
- Nisshinbo Holdings Inc.
- ZF Friedrichshafen AG
- Robert Bosch GmbH
- Sangsin Brake Co., Ltd.
- EBC Brakes
- Bendix Commercial Vehicle Systems LLC
- MAT Holdings, Inc.
- Fras-le S.A.
- Valeo SE
- Industrial Brake & Supply
Automotive Brake Linings Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.90 Billion |
| Market Size by 2035 | USD 6.87 Billion |
| CAGR | CAGR of 5.82% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Axle Position (Front-Axle, Rear-Axle) • By Material (Non-Asbestos Organic, Semi-Metallic, Ceramic, Others) • By Vehicle Type (Passenger Cars, Commercial Vehicles) • By Brake Type (Disc Brakes, Drum Brakes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Akebono Brake Industry Co., Ltd., Aisin Corporation, Brembo S.p.A., Continental AG, Tenneco Inc., General Motors Company, Japan Brake Industrial Co., Ltd., Meritor, Inc., SGL Carbon SE, TMD Friction Holdings GmbH, Nisshinbo Holdings Inc., ZF Friedrichshafen AG, Robert Bosch GmbH, Sangsin Brake Co., Ltd., EBC Brakes, Bendix Commercial Vehicle Systems LLC, MAT Holdings, Inc., Fras-le S.A., Valeo SE, Industrial Brake & Supply |
Frequently Asked Questions
Key players include Akebono Brake Industry Co., Ltd., Aisin Corporation, Brembo S.p.A., Continental AG, and Tenneco Inc., among other friction material manufacturers.
Continued advancement of ceramic and copper-free friction materials and development of electric vehicle-specific brake linings represent the primary opportunities.
Growth is primarily driven by increasing vehicle production, combined with stringent safety regulations and advancing friction materials technology.
By Axle Position, Front-Axle dominated the market with a 56.60% share in 2025, reflecting the greater stopping force front brakes handle during deceleration.
Asia Pacific dominated the market with a 38.60% share in 2025, supported by the region's position as the world's largest vehicle production base.
