
Military Sensors Market Report Scope & Overview:
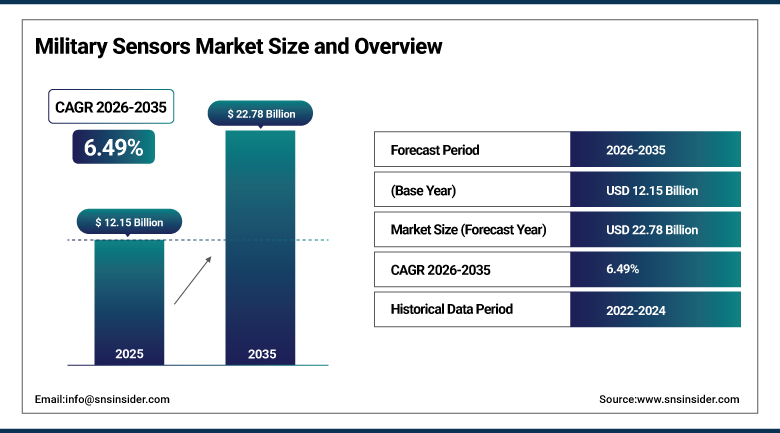
The Military Sensors Market was valued at USD 12.15 Billion in 2025 and is expected to reach USD 22.78 Billion by 2035, growing at a CAGR of 6.49% from 2026-2035.
The growth of the Military Sensors Market is fueled mainly by increasing investments in modern systems of detection, classification, and tracking. Modernization of military operations in land, air, naval, and space forces and sensing as the vital part of it plays a crucial role in the growth. The Military Sensors are indispensable elements of detecting, tracking, and analyzing the threats that allow collecting the necessary data, monitoring the battlefield, and getting intelligence for making decisions during all stages of military operations. Continuous innovations in sensor technology, including its miniaturization, increased sensitivity, and better data processing, allow creating reliable sensor systems functioning in different and difficult conditions such as low temperatures, great altitudes, and under water.
On September 23, 2025, RTX's Raytheon business was awarded a USD 1.7 billion contract by the U.S. Army to deliver the Lower Tier Air and Missile Defense Sensor, a next-generation 360-degree Active Electronically Scanned Array radar designed to replace the Patriot system's current radar while maintaining compatibility with existing launchers and interceptors. The contract includes nine radars for the U.S. Army and Poland, the first international LTAMDS customer, and follows eight successful flight tests that led the Army to validate the radar at Milestone C, officially designating it a program of record ready to support both homeland defense and expeditionary missions, reinforcing continued sustained government investment in next-generation air and missile defense sensing capability.
To Get more information Military Sensors Market - Request Free Sample Report
Military Sensors Market Trends
-
Rising integration of radiation-hardened and imaging sensors supporting spaceborne defense surveillance and tracking.
-
Growing adoption of infrared, LIDAR, and EO/IR sensors driven by electronic warfare and border security operations.
-
Expanding deployment of sensor-enabled armored vehicles and multi-domain sensor fusion capability across allied militaries.
-
Increasing miniaturization of sensor technology enabling integration across a broader range of platforms and munitions.
-
Rising demand for software-defined radar capability offering multi-mission flexibility and improved spectrum sharing.
-
Growing evolution of microelectromechanical systems reinforcing commercial-to-defense sensor technology transfer.
U.S. Military Sensors Market Outlook
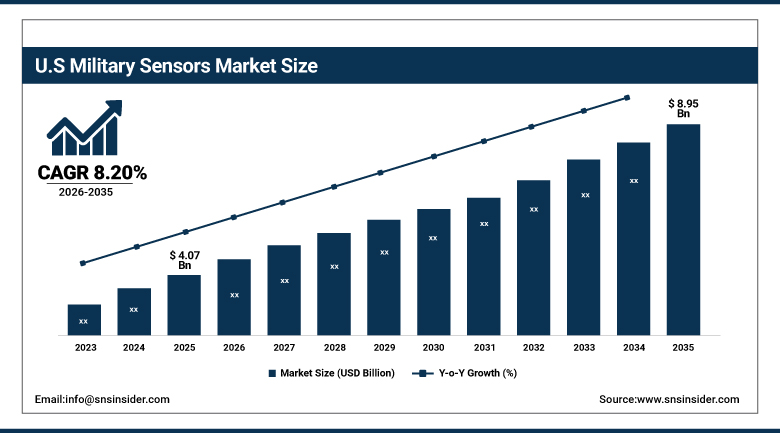
The U.S. Military Sensors Market was valued at USD 4.07 Billion in 2025 and is expected to reach USD 8.95 Billion by 2035, growing at a CAGR of 8.20% from 2026-2035.
Continued development and implementation of advanced defense systems through continued investment further drives growth of the U.S. Military Sensors Market, considering the United States as the largest market globally on account of large defense budgets, constant modernization of forces and the involvement of key domestic contractors such as Raytheon, Honeywell, and Lockheed Martin. Over the last few fiscal years, the budget of the United States Department of Defense was close to USD 850 billion, ensuring constant procurement of sensor systems such as radar, infrared, acoustic, optical and magnetic sensors across various platforms ranging from land, air, naval and space-based. Continued tension between geopolitics and modernization of allied and domestic military forces ensures continued procurement of sensors independent of economic cycles.
In January 2026, Raytheon secured a USD 1.025 billion contract modification from the U.S. Army to support Year Two production requirements for the Lower Tier Air and Missile Defense Sensor, bringing the total cumulative value of the LTAMDS contract to over that amount as the Army continues to expand its next-generation air and missile defense sensor fleet. The award reflects continued Army investment in advanced sensing capability designed to counter increasingly sophisticated ballistic and cruise missile threats, illustrating how domestic sensor manufacturers continue to secure sustained, multi-year production commitments as the U.S. military accelerates fielding of next-generation radar and missile defense sensor technology across its force structure.
Military Sensors Market Segment Analysis
-
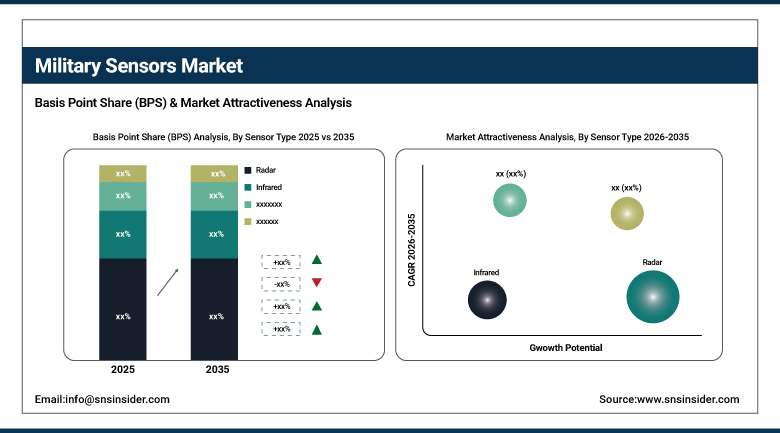
By Sensor Type, the Radar segment dominated the Military Sensors Market with approximately 35.60% share in 2025, while the Infrared segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Platform, the Land segment dominated the Military Sensors Market with approximately 29.60% share in 2025, while the Airborne segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Component, the Software segment dominated the Military Sensors Market with approximately 58.60% share in 2025, while the Hardware segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Application, the Communication & Navigation segment dominated the Military Sensors Market with approximately 41.60% share in 2025, while the Combat Operations segment is the fastest growing with a CAGR of approximately 7.90%.
By Sensor Type, Radar Dominates the Military Sensors Market and Infrared Grows Fastest
Radar sensors dominate the market because radar and imaging technology together account for the largest share of total sensor demand across land, air, naval, and space platforms, reflecting radar's foundational role in detection, tracking, and fire control across nearly every modern weapons system. Radar systems provide the long-range, all-weather detection capability that ground-based air defense, naval surface search, and airborne early warning systems fundamentally depend on, making radar procurement a consistent budget priority across allied militaries pursuing layered air and missile defense architectures. The technology's maturity, combined with continuous advancement in active electronically scanned array design offering improved sensitivity, multi-target tracking, and resistance to jamming, continues to reinforce radar's position as the largest and most strategically prioritized sensor category within global military modernization programs, particularly as missile defense and counter-drone requirements continue to expand worldwide.
Infrared sensors are the fastest-growing sensor type as rising demand for passive, non-emitting detection capability continues to expand infrared adoption across target acquisition, night vision, and missile warning applications where radar's active emissions create detectability risk. This growth is reinforced by the rise in electronic warfare and border security operations, which has accelerated procurement of infrared, LIDAR, and EO/IR sensors by approximately 32.4% between 2022 and 2024 alone, reflecting the technology's growing strategic importance. Continued miniaturization and cost reduction in infrared focal plane array manufacturing is further extending infrared sensor integration into smaller platforms, including soldier-worn systems and unmanned aerial vehicles, reinforcing this segment's above-market growth trajectory as militaries increasingly prioritize passive, low-signature sensing capability across an expanding range of tactical applications.
By Platform, Land Dominates the Military Sensors Market and Airborne Grows Fastest
Land-based platforms account for the largest share in terms of numbers of sensors being used today; these platforms include such types of platforms as armored vehicles, tanks, and tactical ground platforms which are equipped with radar, infrared, and electronics sensors. This is due to the sheer number of land force soldiers and platforms available compared to air and space or navy assets available in armed forces around the globe. The United States, China, and Russia have, together, installed more than 18,000 sensors on their land-based vehicles. The continuous requirement for ground-based troops to have situational awareness and target acquisition capability is what makes up for the dominance of land-based platforms in terms of sensors being used by them.
The airborne platforms represent the most rapidly growing platform segment, with the increasing usage of advanced sensors technology aboard aircraft, such as advanced radars, electro-optical and electronic warfare suites. It will be fueled by the growing budgets for the development of airborne intelligence, surveillance and reconnaissance capabilities, as well as the deployment of new generation fighter jets that need complex sensor fusion architectures to ensure air superiority against modern threat. The development of unmanned aerial systems for missions in combat and reconnaissance roles will also fuel the demand for airborne sensors, as it will drive demand for miniature and lightweight sensor systems capable of offering similar situational awareness as manned aircraft sensor system.
By Component, Software Dominates the Military Sensors Market and Hardware Grows Fastest
Software dominates the market as sensor data processing, fusion, and analytics algorithms increasingly determine the practical battlefield value of raw sensor output, transforming detection data into actionable targeting, tracking, and situational awareness information delivered to operators in real time. Rising integration of artificial intelligence and machine learning into sensor processing pipelines continues to expand software's role beyond basic signal processing into predictive threat classification and autonomous decision-support capability, reflecting the broader defense industry shift toward software-defined systems architecture. This transition continues to reinforce software's position as the largest component category, as defense customers increasingly recognize that sensor system value depends as much on data processing sophistication as on underlying hardware sensitivity and range performance.
Hardware is the fastest-growing component category as rising defense budgets fund replacement of legacy sensor hardware with next-generation active electronically scanned array radars, advanced electro-optical systems, and radiation-hardened space-based sensors across allied military fleets. This growth is reinforced by continued expansion of physical sensor deployment across an increasing number of platforms, including newly commissioned naval vessels, next-generation fighter aircraft, and expanding satellite constellations, each requiring substantial new hardware procurement independent of software licensing revenue. Rising defense satellite deployment, with the United States, Russia, and China collectively operating thousands of sensor-equipped defense satellites, continues to reinforce hardware's accelerating growth trajectory as space-based sensing becomes an increasingly central pillar of military modernization strategy.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
United Kingdom |
29.60% |
|
Middle East & Africa |
Israel |
32.60% |
|
Latin America |
Brazil |
26.60% |
North America Military Sensors Market Insights
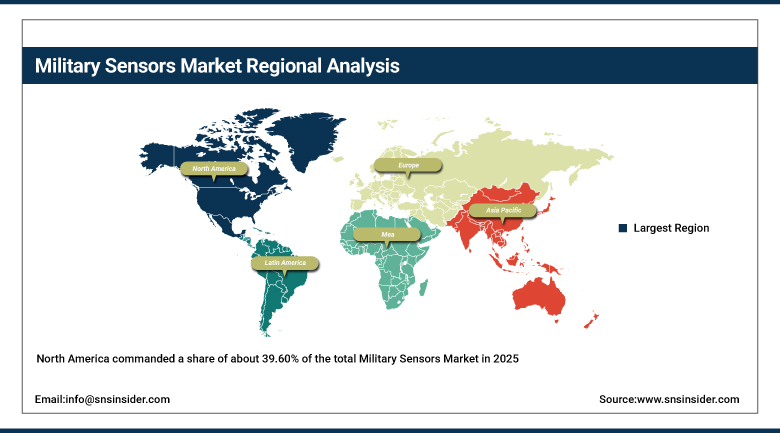
North America commanded a share of about 39.60% of the total Military Sensors Market in 2025 and represents the biggest regional market on the basis of high budget allocations for the armed forces, military modernization projects and presence of leading sensor providers like Raytheon, Honeywell and Lockheed Martin. The United States is still the biggest single nation market on the back of an estimated CAGR of about 8.2% attributed to investments made in future generation defense capabilities which include missile defense, electronic warfare and satellite-based surveillance system. The high concentration of established primes along with consistent support of congress with regards to allocation of funds for multi-year procurement programs has helped the sensor providers gain better revenue visibility as compared to those operating in the commercial technology sector.
Canada is adding to regional demand due to modernization of the armed forces' surveillance and reconnaissance capability as per NATO standard requirements. Further development of missile defense system, including the Lower Tier Air and Missile Defense Sensor and its allied procurements will ensure North America's dominance during the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Military Sensors Market Insights
The Asia Pacific region is the fastest-growing regional market, recording a CAGR of about 8.60% between 2026 and 2035, due to major investments and modernization of military forces along with extensive development of advanced sensors across China, Japan, and India. The Chinese military sensors market is recording annual growth of about 9.8%, owing to the ongoing aggressive military modernization program of the nation, which includes modernization of naval forces, airborne sensors, and deployment of defense satellites. In Japan, steady growth is being witnessed, driven by technological innovations and enhanced defense budget due to increasing regional security threats, while South Korea is focusing on enhancing domestic manufacture of sensors to reduce dependence on imported defense technologies.
Incremental growth is being provided by India as the nation is continuously undertaking military modernization programs in terms of land-based, aerial, and naval sensor acquisitions through the efforts of the government in promoting domestic defense manufacturing capability. Regional security tensions in the Indo-Pacific region have been continuously resulting in consistent government spending on surveillance, reconnaissance, and missile defense sensors in allied countries in order to combat the advancing capabilities of the adversary.
Europe Military Sensors Market Insights
Europe will hold considerable market share in the Global Military Sensors Market, owing to the presence of a large defense industrial base of the United Kingdom and increasing defense modernization investments in other NATO countries as a result of increasing geopolitical tensions due to recent regional security events. The defense contractors in the region, including BAE Systems, Thales, and Leonardo, are continuing to be the key developers of radars, electronic warfare systems, and electro-optical sensors, not only domestically but also for export purposes.
Both Germany and France will generate considerable demand in the region, as they continue to increase their domestic defense manufacturing capacities and engage in European defense modernization projects. The selection of the new generation ground-based air surveillance radar by Sweden from Lockheed Martin highlights the procurement of modern military sensors in Europe both domestically and from allied suppliers in order to improve long-range surveillance capabilities.
Continued consolidation in the defense industry of the region, along with continued investments in NATO interoperability standards, is likely to ensure the region’s significance in the global military sensors market in the coming years.
MEA & Latin America Military Sensors Market Insights
The Middle East & Africa market is anchored by Israel, whose advanced domestic defense technology sector continues to develop and export sophisticated radar, electronic warfare, and missile defense sensor systems to both regional and international customers. Rising regional security tensions continue to sustain substantial defense modernization investment across Gulf state militaries, which increasingly procure advanced sensor technology from both Western and domestic suppliers to enhance air and missile defense capability amid an increasingly contested regional security environment.
Latin America's market remains led by Brazil, where gradual defense modernization investment continues to expand sensor capability across the country's armed forces, particularly naval and airborne surveillance systems. Regional governments across the broader Latin America market continue to invest cautiously in sensor-enabled defense systems, with adoption remaining concentrated among the region's larger, better-resourced militaries. Across both regions, adoption continues to be shaped by a combination of domestic defense industrial capacity and access to allied nations' advanced sensor export programs.
Market Dynamics
Growth Drivers: Defense Modernization Programs and Real-Time Situational Awareness Demand
Increased investments in the development of advanced sensors, classification and tracking systems are considered to be the main factor driving the Military Sensors Market, because all militaries around the world are getting modernized through ground, air, naval and space technologies and robust sensors become an important part of the process. Increased demand for advanced surveillance and reconnaissance systems keeps supporting continuous investments of governments in them, because today's defense officials realize that information superiority is determined by comprehensive coverage by sensors in all domains. This trend keeps supporting stable demand for procurement of military sensors not depending on the overall economic situation, because such programs have the priority in terms of national security.
Real-time situational awareness in modern warfare is the second growth factor, because multi-domain threat environments compel militaries to detect, track and classify threats in all domains at once. Increased geopolitical tensions and modernization of the military forces in the world today keep supporting this trend, while increased electronic warfare operations and border security operations are boosting demand for advanced infrared, LIDAR and EO/IR sensors. Increased use of unmanned systems and precision-guided munitions keeps supporting the demand for advanced target acquisition and weapon guidance sensors.
Restraints: Lengthy Procurement Cycles and Export Control Complexity
Lengthy defense procurement cycles and complex government contracting processes represent a meaningful restraint on market growth, as major sensor programs typically require multi-year development, testing, and certification timelines before reaching full-rate production, constraining the pace at which manufacturers can convert technological innovation into recognized revenue. This extended timeline exposes suppliers to budget appropriation risk, as shifting government priorities or fiscal constraints can delay or reduce planned procurement volumes even after significant upfront development investment, particularly for programs still in early testing and validation phases.
Stringent export control regulations governing advanced sensor and radar technology represent a further restraint, as governments carefully regulate the international transfer of sensitive defense technology to prevent proliferation to potential adversaries, requiring manufacturers to navigate complex, often multi-year approval processes before delivering next-generation sensor systems to allied nations. This regulatory complexity can extend program timelines and constrain the pace at which advanced sensor capability can be fielded across allied military forces, particularly for technologies incorporating the most sensitive processing algorithms or detection capability.
Opportunities: Space-Based Sensing Expansion and AI-Enabled Sensor Fusion
Continued expansion of space-based defense sensing represents a substantial opportunity, as the United States, Russia, and China collectively deploy thousands of defense satellites with integrated sensors for global surveillance and communication, with radiation-hardened sensors improving data accuracy and imaging sensors enhancing orbital defense tracking capability. Suppliers that can deliver reliable, cost-competitive space-qualified sensor technology are positioned to capture sustained government investment as space domain awareness becomes an increasingly central pillar of military modernization strategy worldwide, extending beyond traditional missile warning into broader orbital surveillance and communication applications.
The continued integration of artificial intelligence-enabled sensor fusion capability offers a further avenue for growth, as militaries increasingly seek to process expanding volumes of multi-domain sensor data faster than human analysts can manage manually, transforming raw detection data into actionable, real-time decision support. Suppliers that can demonstrate reliable, combat-tested AI-enabled sensor fusion capability across radar, infrared, acoustic, and optical sensor types are well positioned to capture demand from defense ministries prioritizing information-advantage capability across increasingly contested, multi-domain operational environments.
Recent Developments:
-
In June 2025, Lockheed Martin's TPY-4 next-generation ground-based air surveillance radar was selected by the Swedish Defence Materiel Administration to enhance the country's long-range surveillance capabilities, making Sweden the third nation to adopt the fifth-generation radar system.
-
Northrop Grumman secured a USD 69.1 million modification to a previously awarded U.S. Navy contract for AN/APR-39 D(V)2 radar warning receiver and electronic warfare management systems, delivering antenna detectors, radar receivers, and conversion kits to the Navy and six allied nations.
-
The Missile Defense Agency awarded Raytheon two contracts totaling USD 966.7 million to expand AN/TPY-2 radar development and sustainment.
-
In May 2026, RTX's Raytheon business was awarded a contract to further develop next-generation software-defined radar capability, giving naval radars multi-mission flexibility and improved spectrum sharing with 5G networks.
Military Sensors Market Key Players
-
RTX Corporation
-
Honeywell International Inc.
-
BAE Systems plc
-
Lockheed Martin Corporation
-
Curtiss-Wright Corporation
-
General Electric Company
-
Northrop Grumman Corporation
-
Thales Group
-
Leonardo S.p.A.
-
L3Harris Technologies, Inc.
-
Elbit Systems Ltd.
-
Safran S.A.
-
Teledyne Technologies Incorporated
-
Israel Aerospace Industries Ltd.
-
Kongsberg Gruppen ASA
-
Saab AB
-
Rheinmetall AG
-
Hensoldt AG
-
Indra Sistemas, S.A.
-
Mercury Systems, Inc.
Military Sensors Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 12.15 Billion |
| Market Size by 2035 | USD 22.78 Billion |
| CAGR | CAGR of 6.49% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Sensor Type (Radar, Infrared, Acoustic, Optical, and Magnetic) • by Platform (Land, Airborne, Naval, and Space) • by Component (Hardware and Software) • by Application (Communication & Navigation, Combat Operations, Electronic Warfare, ISR/Surveillance, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | RTX Corporation, Honeywell International Inc., BAE Systems plc, Lockheed Martin Corporation, Curtiss-Wright Corporation, General Electric Company, Northrop Grumman Corporation, Thales Group, Leonardo S.p.A., L3Harris Technologies, Inc., Elbit Systems Ltd., Safran S.A., Teledyne Technologies Incorporated, Israel Aerospace Industries Ltd., Kongsberg Gruppen ASA, Saab AB, Rheinmetall AG, Hensoldt AG, Indra Sistemas, S.A., Mercury Systems, Inc. |

Frequently Asked Questions
Key players include RTX Corporation, Honeywell International Inc., BAE Systems plc, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, and Leonardo S.p.A., among other global defense contractors.
Continued expansion of space-based defense sensing and continued integration of AI-enabled sensor fusion capability represent the primary opportunities.
Growth is primarily driven by heightened investments in advanced detection, classification, and tracking systems combined with the growing need for real-time situational awareness in modern warfare.
By Sensor Type, Radar dominated the market with approximately 35.60% share in 2025, reflecting its foundational role in detection, tracking, and fire control across modern weapons systems.
North America dominated the market with approximately 39.60% share in 2025, driven by substantial defense budgets and ongoing modernization programs.
