
Fire Truck Market Report Scope & Overview:
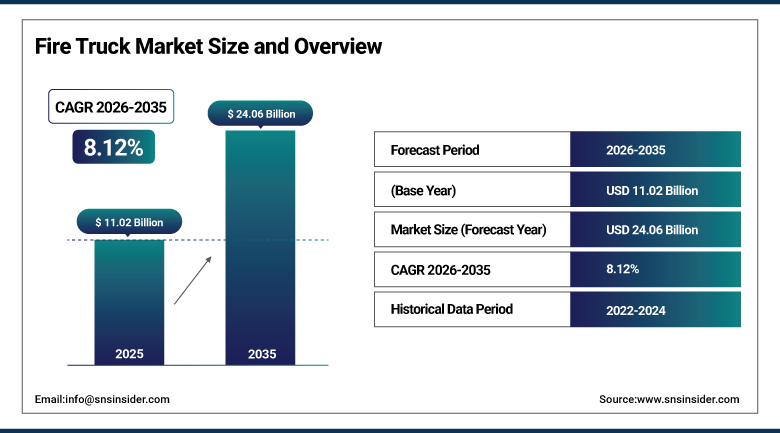
The Fire Truck Market was valued at USD 11.02 Billion in 2025 and is expected to reach USD 24.06 Billion by 2035, growing at a CAGR of 8.12% from 2026-2035.
The Fire Truck Market sits at an inflection point where fleet age, regulation, and propulsion technology are converging to reshape municipal and industrial procurement decisions simultaneously. A large tranche of apparatus purchased in the mid-1990s is now reaching or exceeding its typical 20-to-30-year service life, forcing fire departments into replacement cycles that many delayed budgets can no longer postpone. FEMA's Assistance to Firefighters Grant program has directed roughly USD 324 million per funding cycle toward apparatus and equipment awards, while European low-emission zone procurement rules are increasingly excluding diesel-only municipal purchases from public tenders. Mechanically governed diesel pumpers are giving way to CAN bus-managed drivetrains, telematics-linked pump controls, and battery platforms capable of running scene operations silently for up to two hours.
In January 2025, Pierce Manufacturing, an Oshkosh Corporation business, showcased its Volterra electric fire truck at CES 2025, appearing alongside Oshkosh in the Las Vegas Convention Center's West Hall to highlight advances in electrification, safety systems, and connected firefighting technology. The showcase followed growing municipal interest in zero-emission apparatus, with electric orders in states carrying Green Fleet mandates climbing to roughly 6% of total procurement in 2025 from just 1% in 2022, and it signals how the largest North American manufacturers are positioning battery-electric platforms as a mainstream option rather than a demonstration project, even as most departments continue specifying conventional diesel apparatus for the bulk of their fleets.
To Get more information Fire Truck Market - Request Free Sample Report
Fire Truck Market Trends
- Accelerating replacement demand as apparatus purchased in the mid-1990s reaches the end of its service life.
- Growing municipal specification of battery-electric fire trucks under state-level Green Fleet procurement mandates.
- Rising deployment of CAN bus-managed drivetrains and telematics-linked pump performance monitoring.
- Expanding orders for Type 3 wildland-urban interface engines amid rising Western wildfire activity.
- Continued industry consolidation as the largest manufacturers acquire independent regional apparatus builders.
U.S. Fire Truck Market Outlook
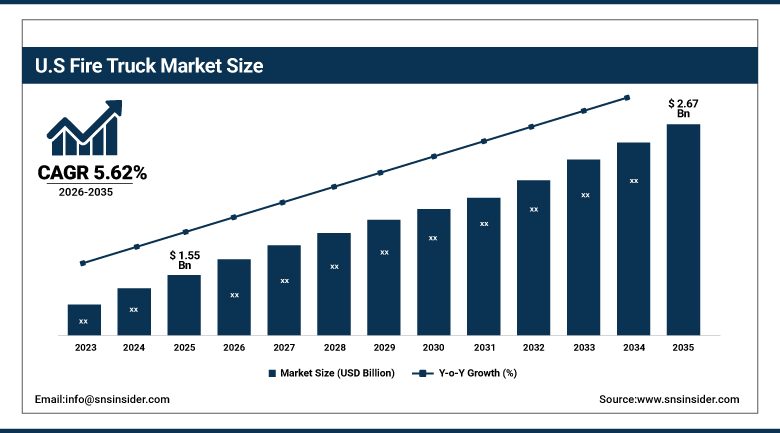
The U.S. Fire Truck Market was valued at USD 1.55 Billion in 2025 and is expected to reach USD 2.67 Billion by 2035, growing at a CAGR of 5.62% from 2026-2035.
The U.S. Fire Truck Market is contending with a supply and pricing environment that federal antitrust litigation filed in 2025 has placed under direct scrutiny, as multiple municipalities allege that consolidation among the three largest domestic manufacturers has extended delivery timelines to roughly two years and pushed the price of a standard engine from around USD 640,000 in 2020 to more than USD 1.1 million by 2026. Fire departments across the country continue to place orders well in advance of anticipated delivery, and municipal budget offices are increasingly redirecting capital planning cycles to absorb both the longer lead times and the higher per-unit apparatus cost that has accompanied them.
In 2025, the Los Angeles County Fire Department took delivery of new Rosenbauer America tractor-drawn aerial quints, adding high-reach aerial capability suited to the county's dense urban and high-rise firefighting requirements. Rosenbauer separately expanded its domestic dealer network by extending territory coverage into South Carolina through an agreement with regional distributor C.W. Williams, broadening the manufacturer's reach into a Southeastern market where municipal fleet replacement demand continues to build. Together these moves illustrate how domestic manufacturers are pursuing both large flagship municipal contracts and incremental dealer network expansion to capture demand across differently sized fire departments.
Fire Truck Market Segment Analysis
- By Vehicle Type, the Pumpers segment dominated the Fire Truck Market with approximately 43.00% share in 2025, while the Aerial Ladder Trucks segment is the fastest growing with a CAGR of approximately 6.85%.
- By Powertrain, the Internal Combustion Engine segment dominated the Fire Truck Market with approximately 82.70% share in 2025, while the Battery-Electric segment is the fastest growing with a CAGR of approximately 8.25%.
- By Application, the Residential & Commercial Firefighting segment dominated the Fire Truck Market with approximately 35.80% share in 2025, while the Wildland & Urban Interface Firefighting segment is the fastest growing with a CAGR of approximately 10.20%.
- By End-User, the Municipal Fire Departments segment dominated the Fire Truck Market with approximately 64.60% share in 2025, while the Airport Authorities segment is the fastest growing with a CAGR of approximately 8.11%.
- By Capacity, the 250 to 500 Gallons segment dominated the Fire Truck Market with approximately 38.00% share in 2025, while the Above 500 Gallons segment is the fastest growing with a CAGR of approximately 5.40%.
By Vehicle Type, Pumpers dominate, and Aerial Ladder Trucks grow fastest
Pumper dominated the vehicle type segment in the Fire Truck Market. Higher-capacity pumps, more efficient engines, and improved maneuverability have kept pumpers at the center of urban firefighting fleets, where quick water delivery to a structure fire remains the single most common response scenario a department plans around. Smart sensors and telematics now built into pump panels give crews real-time visibility into water flow and system performance, a capability that has become close to standard on new orders rather than a premium add-on.
Aerial Ladder Trucks are expected to grow at the fastest pace in the Fire Truck Market. Longer-reaching ladders, lightweight structural materials, and hybrid or electric drive options are pulling aerial ladder trucks ahead of the broader market's growth rate, particularly as departments serving high-rise and dense urban districts replace aging platforms with units offering greater reach and improved control precision. Fleet planners in growing metropolitan areas increasingly treat aerial apparatus as a distinct budget line rather than an occasional specialty purchase, reflecting the vehicle's expanding role beyond fire suppression into technical rescue operations.
By Powertrain, Internal Combustion Engine dominates, and Battery-Electric grows fastest
Internal Combustion Engine dominated the powertrain segment in 2025. An established parts supply chain, decades of maintenance familiarity among municipal fleet technicians, and proven reliability under sustained pump operation keep internal combustion engines the default specification for the overwhelming majority of new apparatus orders placed worldwide. Departments operating in regions without extensive charging infrastructure have few practical alternatives to diesel power for apparatus expected to remain in service for two to three decades.
Battery-Electric powertrain is expected to grow rapidly during the forecast period. Fleet electrification targets written into several state-level Green Fleet mandates, combined with tightening emissions requirements in European low-emission zones, are driving battery-electric apparatus orders upward even from a still-modest base. Manufacturers including Oshkosh's Pierce division have moved electric platforms from concept demonstrations into production-ready models marketed directly to departments seeking to meet sustainability commitments without sacrificing pumping performance during extended incident response.
By Application, Residential & Commercial Firefighting dominate, and Wildland & Urban Interface Firefighting grow fastest
The Residential & Commercial Firefighting segment accounted for the largest share of the Fire Truck Market in 2025, supported by consistent demand from municipal fire departments, commercial facilities, residential communities, and emergency response organizations. Increasing urbanization, expansion of residential and commercial infrastructure, and stricter fire-safety requirements continue to drive procurement of modern firefighting vehicles. Growing replacement of aging fleets with advanced pumpers and multifunctional fire trucks equipped with improved water delivery, communication, and safety systems further supports segment demand across developed and emerging markets.
The Wildland & Urban Interface Firefighting segment is expected to register the fastest growth in the Fire Truck Market, driven by increasing wildfire frequency, expanding urban development near forested areas, and rising requirements for specialized emergency response capabilities. Fire departments and government agencies are investing in vehicles designed for challenging terrain, rapid deployment, high water capacity, and improved crew protection. Growing climate-related fire risks and increasing public spending on wildfire preparedness, prevention, and response are expected to accelerate procurement of specialized wildland and urban-interface firefighting vehicles during the forecast period.
By End-User, Municipal Fire Departments dominate, and Airport Authorities grow fastest
Municipal Fire Departments end use accounted for the largest share of the Fire Truck Market in 2025. Recurring fleet replacement cycles, binding public safety staffing and equipment requirements, and dedicated municipal procurement budgets sustain the largest single block of global fire truck demand within city and county fire departments. Nearly every unit of local government maintaining its own fire service represents a recurring, multi-decade customer relationship for apparatus manufacturers rather than a one-time transaction.
Airport authorities are expanding rescue and firefighting fleets at a pace that outstrips municipal procurement, propelled by growing air traffic volumes, new terminal and runway construction, and stricter aircraft rescue and firefighting standards set under NFPA 414 and ICAO guidelines. Specialized ARFF vehicles carrying several thousand gallons of water and foam concentrate command a materially higher price point than standard municipal pumpers, giving this smaller end-user category outsized revenue significance relative to its unit volume.
By Capacity, 250 to 500 Gallons dominates, and Above 500 Gallons grows fastest
Units in the 250-to-500-gallon range strike the balance most municipal departments look for between maneuverability, onboard storage, and firefighting capability, making them the workhorse specification for quick-response engines and mini pumpers operating across mixed urban and suburban terrain. Manufacturers continue refining tank geometry and pump configuration within this band to shave vehicle weight without sacrificing the water volume a first-arriving engine need.
Demand for tankers and pumpers carrying more than 500 gallons is expanding fastest as wildland-urban interface response and rural departments lacking dense hydrant networks specify larger onboard water supplies capable of sustaining operations before a secondary water source arrives. Western U.S. and Canadian departments in particular have increased orders for Type 3 engines built around 1,000-gallon tanks paired with central tire inflation systems suited to rough, unimproved terrain.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.60 |
|
Europe |
Germany |
27.40 |
|
Asia Pacific |
China |
36.90 |
|
Middle East & Africa |
Saudi Arabia |
32.80 |
|
Latin America |
Brazil |
44.15 |
Europe Fire Truck Market Insights
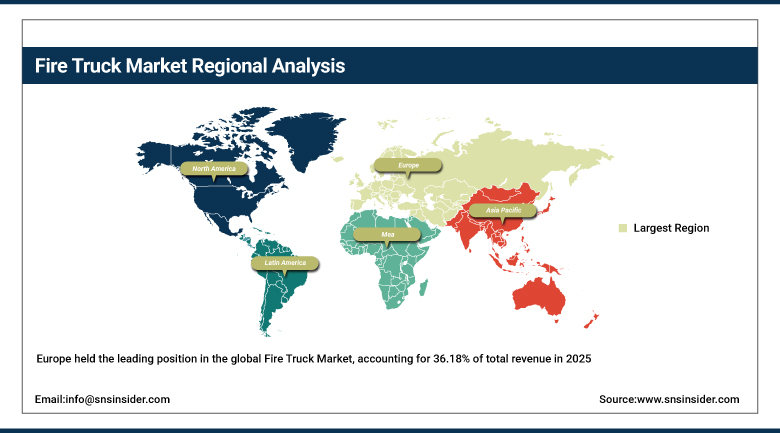
Europe held the leading position in the global Fire Truck Market, accounting for 36.18% of total revenue in 2025, a position built on the region's dense patchwork of national fire safety codes and a wave of low-emission zone rules that are increasingly excluding diesel-only apparatus from public procurement tenders in cities including several in Germany and the Netherlands. Germany anchors regional demand, home to Magirus and a concentration of chassis and aerial-platform suppliers that serve both domestic departments and export orders across the continent.
France and the United Kingdom add substantial regional volume through their own national fire and rescue service procurement programs, while the EU's broader clean-fleet policy direction continues to push municipal buyers toward hybrid and battery-electric apparatus specifications well ahead of similar mandates in most other regions. This regulatory environment gives European manufacturers an early proving base for electrified platforms that are increasingly exported to North American and Asian markets pursuing comparable sustainability commitments.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Fire Truck Market Insights
China is set to lead Asia Pacific's expansion at a forecast CAGR of 5.60% through 2035, a pace tied directly to rapid urbanization and fire-safety regulations that are prompting bulk municipal purchases of modern firefighting fleets across the country's fastest-growing cities. Smart city development programs are layering telematics and centralized fleet-monitoring requirements onto new apparatus specifications, pushing domestic manufacturers including Weihai Guangtai and Xuzhou Handler toward more technologically sophisticated product lines.
Japan is projected to grow during the forecast period, with urban population growth and elevated hazard risk prompting metropolitan fire departments to prioritize highly agile, low-profile trucks suited to the country's narrow streets and dense high-rise districts. Morita Holdings, Hino Motors, and Isuzu Motors continue to drive innovation in light-vehicle firefighting platforms and autonomous driving assistance features that address the specific operating constraints Japanese municipalities face.
North America Fire Truck Market Insights
North America's fire truck demand is concentrated overwhelmingly in the United States, where an aging installed base, federal antitrust litigation over apparatus pricing, and continued Assistance to Firefighters Grant funding are together shaping a replacement cycle that municipal budgets are only partially able to keep pace with. Canada contributes a smaller share of regional volume through its own provincial fire service procurement, generally sourcing from the same North American manufacturer base serving U.S. departments.
Consolidation among the three largest domestic manufacturers, now the subject of multiple municipal lawsuits alleging coordinated price increases and extended lead times, is reshaping how smaller fire districts approach apparatus procurement, with several departments reporting order backlogs extending past two years for standard pumper engines.
MEA & Latin America Fire Truck Market Insights
The Middle East & Africa market is advancing on the strength of Gulf state infrastructure investment, with Saudi Arabia's Vision 2030-linked urban development programs driving procurement of both municipal firefighting fleets and specialized airport rescue vehicles for expanding aviation hubs across the kingdom. Regional fire services in the United Arab Emirates are similarly investing in high-capacity apparatus suited to the operational demands of large-scale commercial and hospitality developments.
Latin America's growth centers on Brazil, where expanding municipal fire services in major metropolitan areas are gradually replacing older apparatus sourced from a mix of domestic assemblers and imported chassis platforms. Mexico contributes incremental regional demand tied to its own municipal fire service modernization efforts, though budget constraints continue to slow replacement cycles relative to the pace seen in Brazil's larger cities.
Market Dynamics
Growth Drivers: Aging Fleet Replacement and Regulatory Pressure
A substantial share of the global apparatus fleet purchased during the 1990s is now reaching or exceeding its 20-to-30-year design life, and departments operating these units report more frequent breakdowns and harder-to-source replacement parts, conditions that are steadily converting deferred maintenance into unavoidable new-vehicle orders. Public safety officials increasingly treat this aging cliff as a budget planning priority rather than a discretionary upgrade.
Tightening fire safety and emissions regulation is compounding the replacement cycle, as European low-emission zone rules and expanding NFPA and ICAO airport rescue standards effectively require newer apparatus specifications that older vehicles cannot be retrofitted to meet. FEMA's Assistance to Firefighters Grant program, directing roughly USD 324 million per cycle toward apparatus and equipment, gives many U.S. departments the funding mechanism needed to act on replacement rather than continuing to extend service life through repair.
Restraints: High Vehicle Costs and Extended Delivery Timelines
The price of a standard municipal engine has nearly doubled over the past several years, and several smaller fire districts have had to redirect funds originally budgeted for other public safety needs simply to complete apparatus purchases already committed to years earlier. Antitrust litigation filed by multiple U.S. municipalities in 2025 directly attributes part of this cost escalation to consolidation among the largest manufacturers.
Order-to-delivery timelines stretching to two years or longer leave some departments operating equipment well past its safe service life while awaiting replacement units, a gap that public safety officials describe as a significant risk to emergency response capability in the interim. Manufacturers cite constrained chassis and component supply chains as the primary bottleneck, though critics argue that production capacity has not scaled in proportion to order backlogs.
Opportunities: Electrification and Aftermarket Retrofit Programs
Battery-electric platforms capable of running pump and scene operations silently for up to two hours are opening a distinct product category that manufacturers can price at a premium relative to conventional diesel apparatus, particularly for departments in states carrying binding Green Fleet procurement mandates. Early production models from Pierce and other leading brands are establishing reference deployments that later adopters are likely to cite when building their own electrification business case.
Aftermarket upgrade and retrofit programs present a parallel opportunity for manufacturers and independent suppliers to extend revenue beyond the initial vehicle sale, as departments facing extended new-apparatus lead times increasingly turn to telematics retrofits, pump-control upgrades, and extended-life refurbishment programs to keep existing units operational and compliant with evolving safety standards.
Recent Developments:
- 2026: Pierce launched Phase I of its High Flow production line in Appleton, Wisconsin, modernizing custom-chassis assembly while improving production flow, quality, and operator safety.
- 2026: Rosenbauer and MAN presented the L32A-XS electric aerial ladder on MAN’s eTGM chassis, creating a fully electric ladder truck below 16 tonnes for urban and specialized applications.
- 2026: Iveco’s Magirus business continued restructuring its firefighting portfolio, developing next-generation vehicles while introducing new approaches to crew-cab design, materials, repairability, and manufacturing efficiency.
Fire Truck Market Key Players are:
- Oshkosh Corporation
- Pierce Manufacturing, Inc.
- REV Group, Inc.
- Rosenbauer International AG
- Iveco Group N.V.
- Morita Holdings Corporation
- Magirus GmbH
- Weihai Guangtai Fire Manufacturing Co., Ltd.
- Danko Emergency Equipment Co.
- Xuzhou Handler Special Vehicle Co., Ltd.
- Bronto Skylift Oy Ab
- Hino Motors, Ltd.
- Isuzu Motors Limited
- Gimaex International
- E-ONE, Inc.
- Ferrara Fire Apparatus, Inc.
- KME Fire Apparatus
- Smeal Fire Apparatus Co.
- HME Ahrens-Fox
- Terex Corporation
Fire Truck Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.02 Billion |
| Market Size by 2035 | USD 24.06 Billion |
| CAGR | CAGR of 8.12% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Vehicle Type (Pumpers, Aerial Ladder Trucks, Tankers, Rescue Trucks, Aircraft Rescue and Firefighting Vehicles, Industrial Trucks, Specialty Trucks, Others) • By Powertrain (Internal Combustion Engine, Hybrid, Battery-Electric) • By Application (Residential & Commercial Firefighting, Industrial Firefighting, Airport Firefighting / ARFF, Wildland & Urban Interface Firefighting, Rescue & Emergency Response, Military & Defense, Others) • By End-User (Municipal Fire Departments, Airport Authorities, Industrial Facilities, Others) • By Capacity (Below 250 Gallons, 250 to 500 Gallons, Above 500 Gallons) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Oshkosh Corporation, Pierce Manufacturing, Inc., REV Group, Inc., Rosenbauer International AG, Iveco Group N.V., Morita Holdings Corporation, Magirus GmbH, Weihai Guangtai Fire Manufacturing Co., Ltd., Danko Emergency Equipment Co., Xuzhou Handler Special Vehicle Co., Ltd., Bronto Skylift Oy Ab, Hino Motors, Ltd., Isuzu Motors Limited, Gimaex International, E-ONE, Inc., Ferrara Fire Apparatus, Inc., KME Fire Apparatus, Smeal Fire Apparatus Co., HME Ahrens-Fox, Terex Corporation |
Frequently Asked Questions
Key players in the Fire Truck Market include Oshkosh Corporation, Pierce Manufacturing, Inc., REV Group, Inc., Rosenbauer International AG, and Iveco Group N.V., among others.
Key opportunities lie in premium-priced battery-electric apparatus for departments under Green Fleet mandates, and in aftermarket telematics and pump-control retrofit programs that extend the service life of aging fleets.
Accelerating replacement of apparatus purchased in the 1990s that has reached the end of its service life, combined with tightening fire safety and emissions regulation, is the major growth factor.
By Vehicle Type, the Pumpers segment dominated the Fire Truck Market with approximately 43.00% share in 2025.
Europe dominated the Fire Truck Market with approximately 36.18% share in 2025, supported by low-emission zone procurement rules and a dense concentration of apparatus manufacturers.
