
Frozen Food Market Report Scope & Overview:
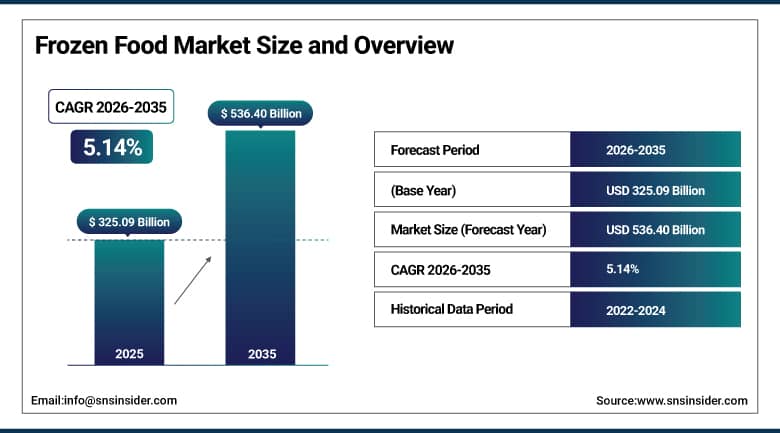
The Frozen Food Market was valued at USD 325.09 Billion in 2025 and is expected to reach USD 536.40 Billion by 2035, growing at a CAGR of 5.14% from 2026 to 2035.
The growth of the Frozen Food Market can be attributed to the increased demand among consumers for ready-to-cook food products having longer shelf lives. Urbanization and the fast-paced nature of modern-day living, combined with consumers becoming more working class, is leading to an increase in the consumption of frozen food products like meals, snacks, meat, seafood, and vegetables. Technological developments in the freezing industry and logistics are playing a significant role in improving the products, cutting down on food wastage, and enhancing the ability of distribution. Growth in the number of supermarket chains, hypermarkets, convenience stores, and even online food stores is increasing the availability of frozen food products to consumers.
Conagra Brands launched nearly 100 new frozen and grocery products in June 2026, focused on high protein, convenience, and value across brands including Banquet, Healthy Choice, Marie Callender's, Birds Eye, Gardein, and P.F. Chang's, coinciding with the company's removal from the S&P 500 into smaller-cap benchmarks, reflecting the scale of product innovation legacy frozen food manufacturers are pursuing to reposition themselves with both investors and increasingly protein-focused, value-conscious consumers.
To Get More Information On Frozen Food Market - Request Free Sample Report
Frozen Food Market Trends
-
Growing high-protein, convenience, and value-focused product innovation continues to reshape legacy frozen food brand portfolios worldwide.
-
Rising rapid urbanization, particularly across Asia Pacific, continues to expand the working urban population reliant on time-saving convenient food solutions.
-
Expanding Individual Quick Freezing technology continues improving product texture, flavor, and nutrient retention, strengthening consumer acceptance of frozen foods.
-
Increasing rising investments in cold chain infrastructure across emerging economies continue enhancing refrigerated storage, transportation, and distribution networks.
-
Growing e-commerce and temperature-controlled logistics expansion continues to improve frozen food product accessibility across online retail platforms.
U.S. Frozen Food Market Outlook
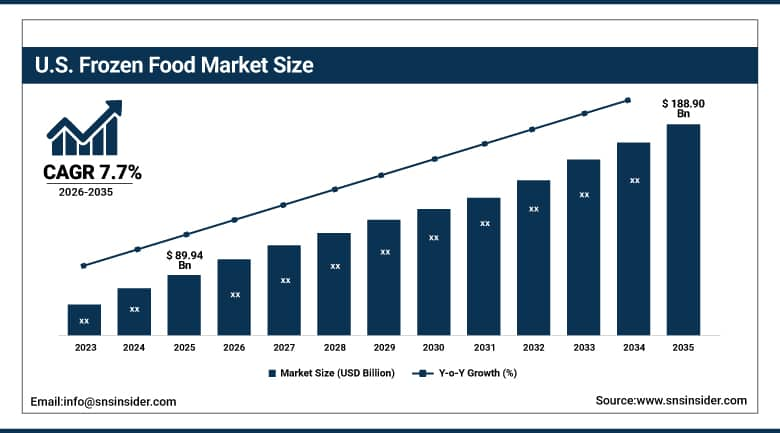
The U.S. Frozen Food Market was valued at USD 89.94 Billion in 2025 and is projected to reach USD 188.90 Billion by 2035, growing at a CAGR of 7.7% during 2026-2035.
The U.S. Frozen Foods Market is witnessing growth owing to the increasing preference of consumer’s towards convenient and ready-to-cook food owing to the busy lifestyle and increased participation in workforce of people. The demand for frozen foods such as frozen food items, frozen meat, fish, vegetables, snacks and bakery products is being fueled owing to the availability of supermarkets, hypermarkets, convenience stores and e-commerce channels. Technological advancements in the field of freezing and packaging are helping in enhancing the quality and nutritive content of these food items.
Frozen Food Market Segment Analysis
-
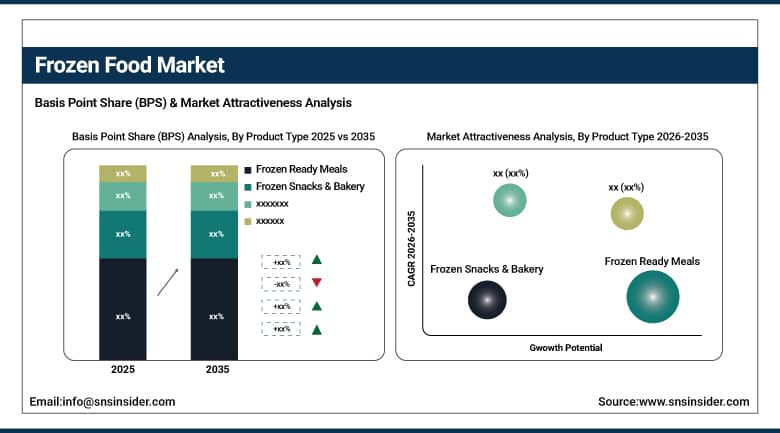
By Product Type, Frozen Ready Meals segment dominated the Frozen Food Market in 2025 with 28% share; Frozen Snacks & Bakery segment is the fastest-growing segment.
-
By Distribution Channel, Offline segment dominated the Frozen Food Market in 2025 with 82% share; Online segment is the fastest-growing segment.
-
By End-Use, Retail segment dominated the Frozen Food Market in 2025 with 68% share; Foodservice segment is the fastest-growing segment.
By Product Type, Frozen Ready Meals Dominate the Frozen Food Market While Frozen Snacks & Bakery Register the Fastest Growth
Frozen Ready Meals dominated the Frozen Food Market in 2025 with a 28% share, owing to the high demand for quick and easy meals that save time. Advances in freezing technology enable better taste and nutrition preservation, boosting demand for the product. The increased variety of products and innovations such as healthy versions, portion sizes, and multicultural cuisines have contributed to the success of this segment. High penetration of products in supermarkets, innovative packaging, longer shelf life, and increased dependence of households on convenient foods have all been instrumental.
Frozen Snacks & Bakery is the fastest-growing segment, owing to the increasing preference of consumers for food products that are convenient and indulgent to prepare. The increasing demand for frozen pizzas, pastries, bread, desserts, and snacks is attributed to the changing lifestyles and urbanization, resulting in consumption at home. The manufacturers are catering to consumers by expanding their product range to include premium, healthier, plant-based, and international variants. Improved freezing technology, long shelf-life, attractive packaging, and wide availability have fueled segment growth.
By Distribution Channel, Offline Distribution Dominates the Frozen Food Market While Online Distribution Experiences the Fastest Growth
Offline distribution dominated the Frozen Food Market in 2025 with an 82% share, because of the wide availability of supermarkets, hypermarkets, convenience stores, and traditional grocers. Customers buy frozen foods through Offline Channels because it becomes easier to inspect the product due to the presence of freezers to store such products. The wide availability of logistics and retailers also ensures that customers can find such products and maintain temperature control during transportation. Also, promotions, visibility, bulk purchases, and physical stores ensure that offline distribution channels are widely available.
Online distribution is the fastest-growing channel, because of the increase in internet connectivity, usage of smartphones, digital payments, and consumer preference for home delivery of products. With Online Distribution, customers can see their desired range of frozen food products and get to know about prices, discounts, and other things and order them from the comfort of their homes. There have been developments in logistics, insulation, and last-mile temperature control services that will make sure that the quality of delivered products increases.
By End-Use, Retail Dominates the Frozen Food Market While Foodservice Witnesses the Fastest Growth
Retail dominated the Frozen Food Market in 2025 with a 68% share, primarily because frozen foods are bought by households in huge volumes from supermarkets, hypermarkets, convenience stores, and grocery stores. Urbanization trends, hectic lives, smaller household size, and need for easy to prepare foods have been driving the growth in retail. Retailers provide extensive assortments, discounts, freezer display, and even private label options which make consumers buy frozen foods. Improved cold chain and increased availability of frozen foods in emerging markets is another reason for dominance of this segment.
Foodservice is the fastest-growing end-use segment, due to the growth of the number of restaurants, quick service outlets, cafes, catering firms, and institutional foodservice operations. Frozen ingredients and ready-to-eat food help foodservice firms save preparation time, manpower, avoid food waste and loss, and maintain uniform quality and portion size of products. Increasing demand from customers for restaurant meals, food deliveries, takeaways, and convenience-based meals is boosting the use of frozen foods. Expansion of foodservice networks, menu standardization, improved cold chain and availability of frozen meat, seafood, bakery and snack products is also driving growth.
Regional Insights
|
Region |
Country |
Regional Share (2025) |
|---|---|---|
|
Europe |
Germany |
22.80% |
|
North America |
United States |
78.00% |
|
Asia Pacific |
China |
32.60% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
24.60% |
Europe Frozen Food Market Insights
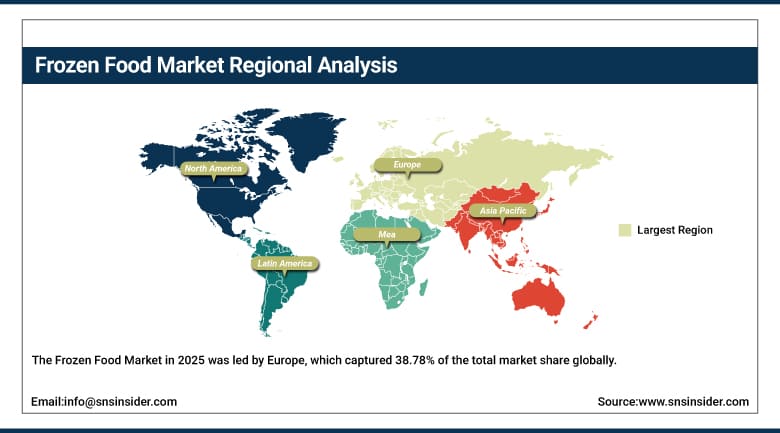
The Frozen Food Market in 2025 was led by Europe, which captured 38.78% of the total market share globally. Such dominance is attributed to efficient retail and distribution channels, high consumer acceptance, and an entrenched tradition of consuming frozen food products. Growing demand for convenient and time-saving food products also contributes to growth in the region. Moreover, regular product innovation by major manufacturers of frozen food products in Europe in terms of healthier and premium quality products strengthens product adoption, thereby maintaining Europe's dominance in the global frozen food market.
Germany led European frozen food consumption with approximately 22.80% of the European market, supported by comprehensive retail distribution through Edeka, Rewe, Lidl, and Aldi. The United Kingdom, France, Netherlands, Poland, and Russia are also contributing meaningfully to regional growth, supported by established frozen food retail infrastructure across the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Frozen Food Market Insights
North America held a significant share of the global Frozen Food Market in 2025, owing to the rise in the number of dual income families and busy lives, resulting in increasing demands for ready to eat and cook frozen foods. Well-developed distribution channels, presence of efficient cold chain network, and consumer acceptance are additional factors contributing to market growth. Some prominent manufacturers are launching healthier frozen food products with high protein content, value, and premium offerings.
The United States accounted for approximately 78.00% of the North American market in 2025, reflecting its large dual-income household base and concentration of leading frozen food manufacturers including Nestlé, Conagra, and Tyson Foods. Canada is contributing to regional growth through steady frozen food adoption and growing consumer interest in convenient meal solutions.
Asia Pacific Frozen Food Market Insights
Asia Pacific is projected to emerge as the region with the highest growth rate from 2026 to 2035 owing to factors such as urbanization and increased size of working population in countries such as India, Indonesia, Japan, South Korea, and Singapore. The hectic lifestyles of consumers are boosting the consumption of ready-to-cook and ready-to-eat frozen foods. Modern retail channels such as supermarkets, hypermarkets, convenience stores, and online grocery stores are making frozen food products more accessible to consumers. The other important factors driving the demand in the region include rising disposable income levels, shifting consumer preferences, cold chain infrastructure development, and awareness among consumers about frozen foods.
China accounted for approximately 32.60% of the Asia Pacific market in 2025, supported by its rapidly expanding urban consumer base and growing modern retail infrastructure. Japan, India, and South Korea are also contributing meaningfully to regional growth, with sustained growth in frozen food consumption across the region's fast-growing urban populations.
Middle East & Africa and Latin America Frozen Food Market Insights
There is a constant increase in the Frozen Food Market in the Middle East & Africa, thanks to the rise in investment in advanced retailing and the development of the cold chain facilities, especially in the Gulf countries. The penetration of supermarkets and convenience retailers has been contributing to better availability of frozen food items. On the other hand, there is the Latin America region that has been reaping gains out of urbanization, changes in lifestyle, and the increased need for convenient meals.
The UAE led the Middle East & Africa market with a 20.60% regional share in 2025, supported by growing modern retail penetration and rising cold chain infrastructure investment. Brazil represented 24.60% of the Latin American market in 2025, driven by expanding frozen food consumption, with Mexico also contributing to regional growth through rising demand for convenient meal solutions.
Growth Drivers: Convenience-Driven Consumption and Cold Chain Infrastructure Development Driving Market Growth
The driving factors behind the growth in The Frozen Food Market include growing demand for convenience food, growing number of retail stores providing frozen food, technological improvements in the cold chain market and innovations in the retail store infrastructure. Since preparation of frozen food products takes less time and effort as compared to home cooked meals, the market will continue to grow due to increasing dual income family households and growing consumer demand for convenience meals.
Innovations in high protein, convenience and value based products continue to transform traditional frozen food brands' portfolio globally. Urbanization is growing rapidly especially in the Asia Pacific region and increasing urban working class population demands more convenience food options. Growing technology of Individual Quick Freezing improves product taste, flavor and nutrient retention.
Restraints: Health Risk Perceptions and Sodium Content Concerns Limiting Market Expansion
However, despite the favorable fundamental demand drivers, the industry is constrained by factors relating to the health risk posed by frozen ready meals in terms of sodium, preservatives, and the process of ingredients in health-conscious consumers. Ultra-processed food segments continue to see rising levels of scrutiny, necessitating reformulation by manufacturers.
Rising competitive pressures among a growing number of manufacturers of frozen foods, especially when taking into consideration the aggressive product launches by established firms targeting the value-oriented consumers, have continued to exert pressure on margins in core segments. Higher input costs and tariff pressures also continue to pose earnings uncertainties for manufacturers.
Opportunities: High-Protein Product Innovation and Cold Chain Expansion Creating New Growth Avenues
There is ample potential for innovation within high-protein, value-oriented frozen meals targeting changing consumer dietary needs and price-sensitive shopping habits. Firms which succeed in marketing innovative new products in their existing brand line-ups have the potential to secure considerable portion of category growth as investor and consumer focus on nutrition and value aligns.
Investment in cold chain infrastructure within developing nations offers another area of significant growth potential, as improved refrigeration systems facilitate efficient frozen food logistics chains. E-commerce expansion and temperature control capabilities in the Asia Pacific and Latin American regions represent another potential area for frozen food producers to expand geographically.
Recent Developments
-
2026: Nestlé secured strategic investment to expand its frozen food portfolio, including ready meals, frozen vegetables, and plant-based offerings.
-
2025: McCain Foods attracted fresh investment to advance its frozen potato and snack product lines, emphasizing brand innovation and supply chain optimization.
-
2025: Nomad Foods introduced innovative frozen seafood and vegetable products sourced sustainably and optimized for freshness retention.
-
2025: ITC Limited raised funding to scale its frozen and ready-to-eat food portfolio in India, focusing on strengthening cold-chain infrastructure and expanding distribution.
Frozen Food Companies are:
-
Nestlé S.A.
-
General Mills, Inc.
-
Conagra Brands, Inc.
-
Tyson Foods, Inc.
-
McCain Foods Limited
-
Unilever PLC
-
The Kraft Heinz Company
-
Ajinomoto Co., Inc.
-
Grupo Bimbo
-
Kellanova
-
Associated British Foods plc
-
JBS S.A.
-
Cargill, Incorporated
-
Dr. Oetker
-
Amy's Kitchen
-
Schwan's Company
-
Lamb Weston Holdings, Inc.
-
Rich Products Corporation
Frozen Food Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 325.09 Billion |
| Market Size by 2035 | USD 536.40 Billion |
| CAGR | CAGR of 5.14% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Frozen Ready Meals, Frozen Meat & Poultry, Frozen Fruits & Vegetables, Frozen Fish & Seafood, Frozen Snacks & Bakery, Others) • By Distribution Channel (Offline, Online) • By End-Use (Retail, Foodservice) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Nestlé S.A., General Mills, Inc., Conagra Brands, Inc., Tyson Foods, Inc., McCain Foods Limited, Nomad Foods Ltd., Unilever PLC, The Kraft Heinz Company, Ajinomoto Co., Inc., Grupo Bimbo, Kellanova, Associated British Foods plc, JBS S.A., Cargill, Incorporated, Dr. Oetker, Bellisio Foods, Amy's Kitchen, Schwan's Company, Lamb Weston Holdings, Inc., Rich Products Corporation |

Frequently Asked Questions
The Frozen Food Market is expected to grow at a CAGR of 5.14% from 2026 to 2035.
The Frozen Food Market was valued at USD 325.09 Billion in 2025.
The market is driven by rising demand for convenience food, expansion of retail stores offering frozen food, and technological advancements in the cold chain market.
The Frozen Ready Meals segment dominated the Frozen Food Market in 2025.
The Europe region dominated the Frozen Food Market in 2025, accounting for approximately 38.78% market share.
