
Fungicides Market Report Scope & Overview:
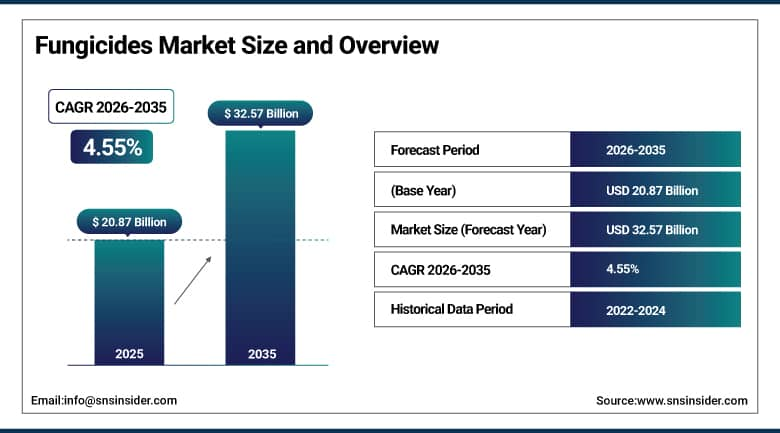
The Fungicides Market was valued at USD 20.87 Billion in 2025 and is expected to reach USD 32.57 Billion by 2035, growing at a CAGR of 4.55% from 2026-2035.
The Fungicides Market is expanding as farmers protect yields against rising disease pressure in cereals, oilseeds and horticulture. Warmer and wetter seasons favor rusts, blights and mildews. Resistance to older chemistries pushes growers toward new modes of action and combination products. Biological options are growing from a small base. Asia Pacific holds the largest share while Latin America expands fastest. Liquid products applied as foliar sprays still anchor sales. Seed treatments and dry granules are gaining ground. Registration speed and residue rules decide which products reach farmers first. Suppliers respond with broader portfolios and local partnerships. Crop losses from fungal disease keep spending resilient even when commodity prices soften.
⮞In July 2025, the Food and Agriculture Organization (FAO) reported that global pesticide use reached about 3.73 Million tonnes of active ingredient in 2023. The scale of this crop protection base explains why fungicide demand remains tied to farm disease management worldwide.
To Get More Information On Fungicides Market - Request Free Sample Report
Fungicides Market Trends:
-
Biological fungicides are gaining ground as residue limits tighten and bioinput approvals grow in major farming countries.
-
New modes of action are entering cereals and horticulture to counter resistance in established fungal pathogens.
-
Mixed-mode and combination products are preferred by advisers who manage resistance across several spray passes.
-
Drone spraying, chemigation and digital disease forecasting are improving timing and cutting wasted applications.
-
Licensing and co-development agreements among leading suppliers are widening access to newly patented actives.
U.S. Fungicides Market Outlook:
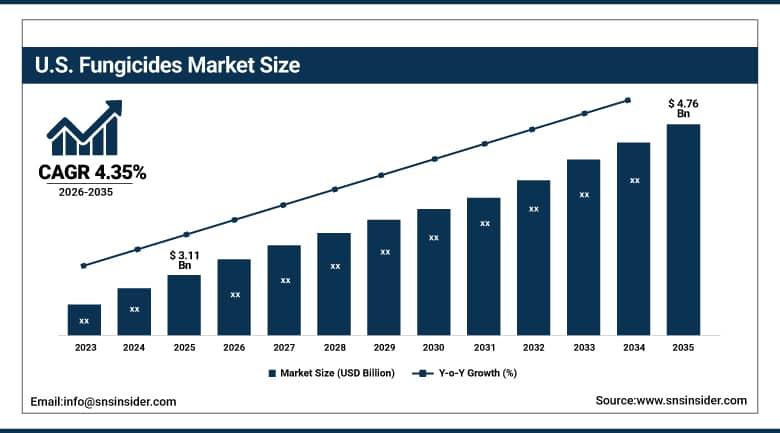
The U.S. Fungicides Market was valued at USD 3.11 Billion in 2025 and is expected to reach USD 4.76 Billion by 2035, growing at a CAGR of 4.35% from 2026-2035.
The U.S. Fungicides Market is growing at a steady pace that trails the global market. Corn, soybeans, wheat and potatoes account for most treated acreage. Tar spot, southern rust and white mold now push growers to apply fungicide on a routine basis. Specialty crops such as grapes and vegetables add high value spray programs. Retail agronomists sell multi-mode products that guard against resistance. Federal registration timelines affect how fast new actives reach farms. Seed treatments and drone applications are broadening the ways products are applied. Large farm sizes let growers invest in scouting and timing tools that raise returns. Cooperatives and custom applicators extend access to smaller operations.
⮞In May 2026, the USDA National Agricultural Statistics Service (NASS) reported that fungicide was applied on 96% of planted potato acres in 2025. Such near universal coverage shows how deeply disease control is built into high value crop budgets in the country.
Fungicides Market Segment Analysis:
-
By Type, the Chemical Fungicides segment dominated the Fungicides Market with approximately 81.16% share in 2025, while the Biological Fungicides segment is the fastest growing with a CAGR of approximately 8.25%.
-
By Formulation, the Liquid Formulations segment dominated the Fungicides Market with approximately 67.73% share in 2025, while the Dry Formulations segment is the fastest growing with a CAGR of approximately 5.55%.
-
By Mode of Application, the Foliar Spray segment dominated the Fungicides Market with approximately 59.36% share in 2025, while the Seed Treatment segment is the fastest growing with a CAGR of approximately 5.65%.
-
By Crop Type, the Cereals and Grains segment dominated the Fungicides Market with approximately 44.22% share in 2025, while the Fruits and Vegetables segment is the fastest growing with a CAGR of approximately 4.98%.
By Type, Chemical Fungicides Dominate Fungicides Market; Biological Fungicides to Register Fastest Growth.
Chemical fungicides stay the first choice of growers because they act within hours and protect against rusts, blights and mildews across many crops. Triazole, strobilurin and dithiocarbamate families are sold at prices that suit commodity farmers. Long shelf life and wide stocking by agrodealers support steady use in developing farm regions. Advisers also know label rates and spray timing well, which lowers perceived risk. Few alternatives match this record of dependable results on large acreage and in wet seasons.
Biological fungicides are advancing because tighter residue limits and export buyer standards reward produce with fewer detectable chemicals. Growers place microbial and plant extract products inside integrated programs to protect organic acreage and ease resistance pressure on conventional actives. Formulation work has improved shelf life and field consistency. Faster national approvals for bioinputs also shorten the path to market, so suppliers keep adding new biological lines. Distributors are widening shelf space for these products as advisers gain field experience.
⮞In August 2025, the U.S. Environmental Protection Agency (EPA) proposed the registration of fluoxapiprolin, a new fungicide for grapes, potatoes and several vegetable crops. Such new actives show how the chemical segment keeps renewing its range of modes of action.
By Formulation, Liquid Formulations Dominate Fungicides Market; Dry Formulations to Register Fastest Growth.
Liquid products suit the sprayer fleets already on farms, so growers can mix them in the tank without added equipment. Suspension concentrates and emulsifiable concentrates disperse evenly in water and give uniform leaf coverage, which speeds uptake of the active ingredient. Manufacturers favor concentrates that are simple to measure and blend with adjuvants or partner products. Contract applicators handle them daily across cereals and horticulture, which preserves the format lead on convenience and dosing accuracy for large and small farms.
Dry products are gaining ground as water dispersible granules replace dusty powders. The granules pour without clouds of fine particles and are measured by weight, which improves operator safety and dosing. Packs are lighter than liquid drums, so exporters pay less freight to reach remote farming areas. Granules also store well in hot climates without freezing or solvent leakage. Policies that discourage solvents in crop protection favor solid forms. Manufacturers therefore keep converting established liquid products into granules.
By Mode of Application, Foliar Spray Dominates Fungicides Market; Seed Treatment to Register Fastest Growth.
Foliar spraying remains the main route since most damaging fungal diseases first show on leaves and canopies where growers can see them. Each pass needs low volume per hectare and can be timed to flowering or grain fill when yield is set. Boom sprayers and aerial rigs already serve most farms. GPS guidance and variable rate nozzles improve coverage and trim waste. Visible canopy results build farmer confidence in repeat applications. Contract spraying services extend the method to small farms.
Seed treatment is expanding because it wraps protection around the seed at planting with very small volumes of active ingredient. Soil and seed borne fungi that cause damping off are controlled before emergence, which safeguards stands and avoids costly replanting. No till and regenerative systems raise early season disease risk and push growers toward the tool. Seed companies now offer pre-treated seed carrying fungicide, insecticide and biological layers in one pass. This saves labor and sprayer trips on farms.
By Crop Type, Cereals and Grains Dominate Fungicides Market; Fruits and Vegetables to Register Fastest Growth.
Corn, wheat and rice are staple crops tied to food security, and fungal disease can strip a large share of their yield. Margins on commodity grain are tight, so preventive programs against rust, gray leaf spot, blast and head blight have become standard practice. Huge planted acreage multiplies product volumes even when the cost per hectare is modest. Government support for staple production and large field sizes keeps spray programs routine, with one or two passes applied each season.
Fruits and vegetables are highly exposed to downy mildew, powdery mildew and gray mold, which damage appearance and shelf life. Retailers and exporters demand blemish free produce with low residues, so growers follow frequent targeted programs using fast degrading products. Changing diets and rising fresh produce consumption lift planted area of high value horticulture. Humid greenhouses and protected cultivation add disease pressure and raise spray intensity per hectare. Export orchards and vineyards spend the most per hectare on protection.
⮞The Crop Protection Network reported in March 2026 that corn disease caused losses of about 1.30 Billion bushels in 2025 across the United States and Ontario. Losses of this size reinforce the yield protection case for preventive fungicide programs in grain production.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
49.80 |
|
North America |
United States |
81.70 |
|
Europe |
France |
22.00 |
|
Latin America |
Brazil |
66.30 |
|
Middle East & Africa |
South Africa |
29.40 |
Asia Pacific Fungicides Market Insights
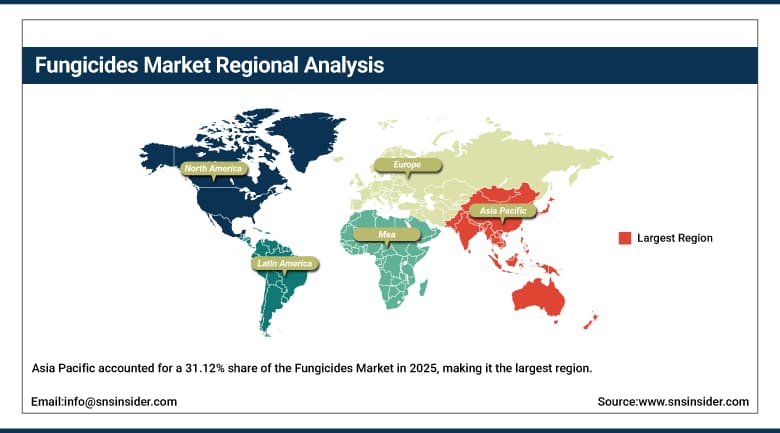
Asia Pacific accounted for a 31.12% share of the Fungicides Market in 2025, making it the largest region. Humid climates, dense rice and vegetable cultivation and large farming populations create steady disease pressure. China represents 49.80% of regional value because of its huge planted area and strong local manufacturing base. India and Southeast Asia add demand through intensive horticulture and banana, rice and plantation crops. Government subsidy and awareness programs encourage wider adoption of crop protection. Rice and wheat intensification in South Asia raises the number of sprays per season. Rising farm incomes support wider purchase of branded products.
Rice blast, sheath blight and wheat rust drive routine spraying in the region, while Japan and Australia lean on advanced premixed products for cereals and specialty crops. Manufacturing capacity expansion in China and India keeps supply competitive across export and local channels. Online sales are also emerging, though rules for platforms remain unsettled. Rising incomes shift demand toward higher quality produce, which supports use of fungicide programs in fruit and vegetables. Plantation crops such as bananas and oil palm add steady spray demand in Southeast Asia. Extension services teach smallholders correct timing and dose.
⮞In September 2025, the Australian Pesticides and Veterinary Medicines Authority (APVMA) published a technical assessment of an emulsifiable concentrate fungicide combining mefentrifluconazole and pyraclostrobin for barley, oats, wheat and pulses. The review shows how premixed liquid products are moving through regional registration.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Fungicides Market Insights
North America holds an 18.25% share of the Fungicides Market, covering the United States and Canada. The United States accounts for 81.70% of regional value with Canada making up the balance. Corn and soybean growers apply fungicide against tar spot, southern rust and white mold, while potato, grape and vegetable producers follow heavier schedules. Canadian wheat and canola acreage faces Fusarium head blight and sclerotinia stem rot. Large farm sizes help growers adopt scouting tools and aerial application. Specialty crop belts in California and the Pacific Northwest add steady demand. Seed treatments are common on soybeans.
Retail agronomy networks dominate distribution and bundle fungicide with seed and fertility advice. Premixes combining several modes of action are widely sold because of resistance worries. Registration agencies in both countries have steady pipelines of new actives and biological products. Cool wet seasons raise disease pressure and spraying, whereas dry years cut applications. Precision application and drone services continue to broaden use across mid-sized farms. Cooperative extension programs publish disease alerts that trigger sprays. Rising interest in biological products comes from fruit, nut and vegetable growers facing buyer residue limits. Lender requirements also support spray decisions.
⮞In 2025, Health Canada's Pest Management Regulatory Agency (PMRA) approved 386 pest control products, including 72 fungicide approvals. This steady flow of fungicide approvals keeps Canadian growers supplied with new tools for resistance management.
Europe Fungicides Market Insights
Europe holds a 21.54% share of the Fungicides Market and is anchored by cereals, oilseed rape, sugar beet, vineyards and orchard crops. France accounts for 22.00% of regional value, followed by Spain, Germany and Italy. Wet temperate seasons favor Septoria leaf blotch, yellow rust and downy mildew, so wheat growers rely on multi-pass programs. Vineyard owners in the Mediterranean arc spray frequently against mildew. Farm advisers also adopt disease forecasting tools that time sprays more precisely. Disease forecasting is common in wheat, where the timing of the flag leaf spray decides much of the return.
Regulation shapes the product mix more than in any other region. Reviews of older active substances and reduction goals under the Farm to Fork strategy limit the number of tools available. Suppliers answer with new chemistries, biological alternatives and combination products that carry lower use rates. Resistance in cereal pathogens is a constant concern. The United Kingdom runs its own approval system, which creates separate launch timelines for new cereal fungicides. Supermarket residue standards add another layer of control and organic acreage is also growing in several member states. Growers value products with longer protection windows.
⮞Eurostat reported in May 2026 that EU pesticide sales reached about 316,000 tonnes in 2024, with fungicides and bactericides making up 40% of the volume. Such a weight confirms that disease control products form the largest single block of plant protection sales in the bloc.
Latin America and Middle East & Africa Fungicides Market Insights
Latin America ranks second by share at 22.14% and is the fastest growing region with a CAGR of 4.95% from 2026 to 2035. Brazil represents 66.30% of regional value on the strength of double cropped soybean and corn systems that need several sprays per season. Mexico is part of Latin America and adds demand through avocado, berry and vegetable exports. Argentina, Colombia and Chile support grain, coffee and fruit programs. Tropical humidity keeps rust and leaf spot pressure high. Credit lines and quicker registration for biologicals speed adoption. Coffee and sugarcane growers add steady fungicide demand.
⮞In May 2026, Sindiveg reported that Brazil's treated area reached about 2.68 Billion hectares in 2025, up 7.60% from 2024. The expanding treated base underpins the region's lead in growth.
The Middle East and Africa hold a 6.95% share, with South Africa representing 29.40% of regional value. South African citrus, grape and maize growers use established spray programs. Gulf countries invest in greenhouse vegetables and date palms that need protected crop disease control. Sub-Saharan Africa offers long term potential but fragmented farms and limited product access slow uptake. Imports supply most products, and regional approval systems are still being aligned. Smallholder training and affordable pack sizes remain the main routes to wider use. Limited cold chain and storage capacity also raise postharvest disease losses.
Market Dynamics:
Growth Drivers: Warmer, Wetter Growing Seasons and Faster Product Registrations Are Raising Fungicide Use.
Climate change is extending the humid spells that fungal pathogens need. Rusts, blights and mildews appear earlier and spread faster in cereals, oilseeds and horticulture. Growers respond with preventive programs rather than waiting for symptoms. Low margin row crops also demand yield protection, since a few lost bushels can erase profit. Rising food demand from growing populations adds pressure to protect every hectare. These forces lift spray frequency in both developed and emerging farm regions. Short rotations in intensive systems also allow disease inoculum to build up in soil and residue. Humid nights favor spore germination and leaf infection.
Newer chemistries add momentum. Succinate dehydrogenase inhibitors and multi-site actives restore performance where older products weakened, and seed treatments gain ground in regenerative and no till systems. Digital disease forecasting helps growers time applications more accurately. Registration systems in large producing countries are processing more products, which brings fresh options to the field. Greater farmer awareness of disease losses supports repeat purchases. Farm cooperatives and extension services now share disease alerts in near real time. Lenders and buyers increasingly expect documented crop protection plans. Better access to credit also helps farmers pay for protection programs.
⮞In January 2026, Brazil's Ministry of Agriculture (MAPA) reported 912 pesticide registrations in 2025. A busy approval pipeline gives growers in the region a wider choice of fungicide options each season.
Restraints: Stricter Residue Rules and Pathogen Resistance Are Limiting the Pace of Fungicide Adoption.
Tighter residue limits and lengthy registration reviews restrict the supply of established actives. Authorities in Europe and several Latin American countries have withdrawn or restricted older substances. Rising organic acreage cuts synthetic use on some farms. Soil copper build up in orchards raises environmental concern. Approval delays and tariffs add cost and uncertainty for suppliers moving products across borders. Each of these factors slows launches and narrows farmer choice. Compliance packages for new data requirements raise the cost of keeping older products on the market. Smaller suppliers often withdraw low volume labels rather than pay for new studies.
Resistance remains a technical limit. Azole and benzimidazole actives have lost field performance against several pathogens, and strobilurin resistance is widespread. Repeated use of single-site products speeds this loss. Concern over effects on beneficial soil microbes and soil toxicity adds scrutiny. Price swings in raw materials can also squeeze manufacturers. Growers must follow strict rotation rules, which cap how often the best performing product can be applied. Biological alternatives still lack the field consistency growers expect in wet seasons. Slow uptake of resistance guidance in smallholder regions further shortens product life.
⮞In February 2026, the European Commission adopted Implementing Regulation (EU) 2026/372, extending approval periods for 29 active substances including the fungicides boscalid and fluopyram. The extensions keep established products available for now but reflect the continuing regulatory scrutiny of fungicide portfolios in Europe.
Opportunities: New Modes of Action, Biologicals and Precision Application Are Opening Fresh Growth Pools for Suppliers.
New modes of action offer the most direct opening, since growers need rotation partners for resistant pathogens. Cereal, potato and grape programs all have unmet needs that fresh chemistry can fill. Biological fungicides give suppliers access to organic and residue sensitive buyers. Nanoencapsulation and controlled release technologies promise longer protection from lower doses. Companies that combine chemical and biological lines can serve integrated programs through one distributor. Suppliers with strong pipelines can also license actives to regional partners and earn income beyond their own sales networks. Premium positioning is possible for products with favorable residue profiles.
Precision agriculture adds a service layer. Drones, sensors and chemigation allow targeted treatment that saves product and labor. Latin America and Asia Pacific offer scale as farms professionalize and credit expands. Sub-Saharan Africa presents a longer horizon where wider product access could unlock smallholder demand. Digital sales channels may also reach remote farms if licensing rules are clarified, giving manufacturers a route beyond traditional agrodealers. Contract application services can bundle drone flights with product sales. Growers in tropical zones with year round disease pressure offer repeat demand. Carbon and sustainability programs may reward lower use rates.
⮞In October 2026, the UK Pesticides Register, as summarized by the British Crop Production Council (BCPC), listed a newly approved cereal fungicide combining prothioconazole and pydiflumetafen for use in Great Britain. Fresh combinations of this kind show how suppliers keep renewing cereal portfolios.
Recent Developments:
-
January 2026, Corteva launched Telbek PRO in Canada as the first Group 21 fungicide for cereals. The product targets Fusarium head blight in wheat, a disease that cuts both yield and grain quality. A new mode of action gives Canadian growers another resistance management tool for a key crop.
-
February 2026, Sumitomo Chemical presented Velera at the Show Rural Coopavel event in Brazil. The fungicide contains metiltetraprole, a new tetrazolinone class active that overcomes G143A strobilurin resistance. The Brazil launch is pending, and the presentation positions the company in the region's largest country market.
-
March 2026, BASF introduced Zorina fungicide in the United States for white mold in soybeans, dry beans and canola. The product combines boscalid with Revysol. BASF cited USD 281.10 Million in soybean losses from white mold in 2024, which shows the scale of the problem the launch addresses.
-
August 2026, Bayer launched Xivana Smart fungicide in India for horticulture. The product carries a new FRAC group 49 active and targets downy mildew and late blight in grapes, cucurbits, potato and tomato. The launch gives Indian growers a fresh mode of action against two costly diseases.
Fungicides Market Key Players:
-
BASF
-
Bayer
-
Corteva
-
FMC
-
ADAMA
-
Sumitomo Chemical
-
Syngenta
-
Nufarm
-
UPL
-
Atul
-
Rovensa Next
-
Seipasa
-
Eden Research
Fungicides Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 20.87 Billion |
| Market Size by 2035 | USD 32.57 Billion |
| CAGR | CAGR of 4.55% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Chemical Fungicides and Biological Fungicides) • By Formulation (Liquid Formulations and Dry Formulations) • By Mode of Application (Foliar Spray, Seed Treatment, Soil Treatment, and Chemigation) • By Crop Type (Cereals and Grains, Fruits and Vegetables, Oilseeds and Pulses, and Turf and Ornamentals) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF, Bayer, Corteva, FMC, ADAMA, Sumitomo Chemical, Syngenta, Nufarm, UPL, Atul, Rovensa Next, Seipasa, Eden Research |

Frequently Asked Questions
Key players in the Fungicides Market include BASF, Bayer, Corteva, FMC, and Syngenta among others.
Key opportunities include new modes of action that help growers manage resistance, biological fungicides for residue sensitive buyers, and precision application through drones and chemigation. Fast expanding farm sectors in Latin America and Asia Pacific offer added scale.
Rising fungal disease pressure on staple and high value crops is the major growth factor. Warmer and wetter seasons, resistance to older actives and the need to protect yield on thin margins push growers toward regular fungicide programs.
The Chemical Fungicides segment dominated the Fungicides Market with approximately 81.16% share in 2025. Fast action, broad-spectrum protection, low cost per hectare and wide availability support its lead.
Asia Pacific dominated the Fungicides Market in 2025 with approximately 31.12% share. Humid climates, large cultivated area, intensive rice and horticulture production and strong local manufacturing in China and India explain the lead.
