
Gluten-Free Products Market Report Scope & Overview:
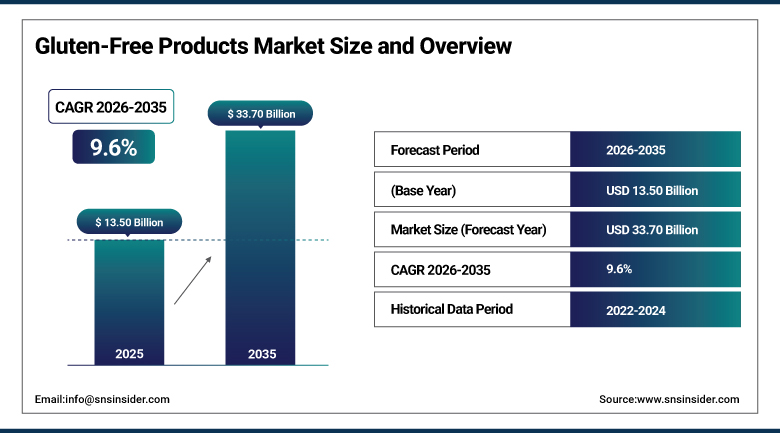
The Gluten-Free Products Market was valued at USD 13.50 Billion in 2025 and is expected to reach USD 33.70 Billion by 2035, growing at a CAGR of 9.6% from 2026 to 2035.
The global Gluten-Free Products Market is experiencing strong growth, owing to rising consumer awareness about health problems associated with gluten intake and rising inclination towards healthy eating habits. High demand for gluten-free bakery products, snacks, ready to eat food items, and desserts is motivating players to diversify their product portfolio. Availability of products in supermarkets, specialist stores, specialist retailers, and online is also contributing to the growth of the market. Advancements in gluten-free formulas, improvement in taste and texture, and rising consumption of alternate grains like rice, corn, and quinoa are some other factors that are helping the market grow. Demand for clean label, healthy, and convenience food products is likely to create ample opportunities for market players in the coming years.
General Mills expanded its gluten-free product portfolio in December 2025 by strengthening its certification standards and introducing improved supply chain traceability for its gluten-free bakery and snack offerings, reinforcing consumer trust and product transparency in the global market as the company continues integrating gluten-free positioning across its mainstream branded product lines rather than treating it as a niche category addition.
To Get more information Gluten-Free Products Market - Request Free Sample Report
Gluten-Free Products Market Trends
-
Growing transition from a niche, condition-driven category to a mainstream functional food segment continues to reshape competitive dynamics.
-
Rising portfolio integration by large FMCG players is bringing gluten-free options into everyday branded products beyond specialty-only positioning.
-
Expanding innovation in texture, taste, and cost parity continues to narrow the gap between gluten-free and conventional wheat-based product experiences.
-
Increasing demand for gluten-free desserts and frozen treats continues as manufacturers maintain taste and texture while eliminating wheat-based ingredients.
-
Growing plant-based and clean-label trend convergence continues to boost interest in gluten-free products offering both indulgence and health-conscious appeal.
U.S. Gluten-Free Products Market Outlook
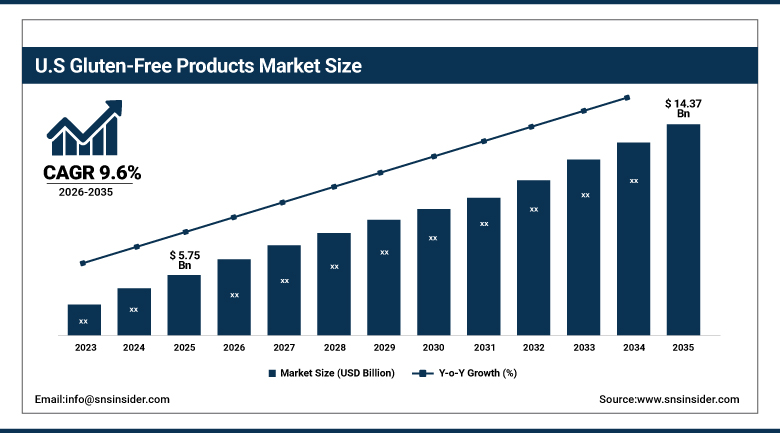
The U.S. Gluten-Free Products Market was valued at USD 5.75 Billion in 2025 and is projected to reach USD 14.37 Billion by 2035, growing at a CAGR of 9.6% during 2026-2035.
The U.S. Gluten-Free Products Market is witnessing strong growth, due to rising awareness among consumers about the negative impact of gluten on their health and increasing trends of adopting specific diets. Rising demand for gluten-free bakery products, snacks, RTE food products, and desserts is motivating players to come up with new and innovative products with enhanced flavors, textures, and nutritional content. The growing availability of gluten-free products in the grocery stores, specialty food stores, and online retail channels is further making the life of consumers easy. Increasing popularity of clean label food products and healthier food products is driving the market further. Innovation in products based on alternate grains like rice, corn, and quinoa is likely to provide further opportunities to players.
General Mills announced plans in February 2026 to expand its gluten-free and protein-rich cereal portfolio, including popular brands such as Cinnamon Toast Crunch and Lucky Charms, aiming to strengthen its presence in the health-oriented breakfast segment by offering more nutritious and gluten-free options, reflecting the continued mainstreaming of gluten-free positioning across some of the most recognizable American breakfast cereal brands.
Gluten-Free Products Market Segment Analysis
-
By Product Type, Bakery Products led the Gluten-Free Products Market with a 31.80% share in 2025, while Desserts & Ice-Creams is the fastest-growing product type segment with a CAGR of 10.90% from 2026-2035.
-
By Source, Rice-based led the Gluten-Free Products Market with a 32.60% share in 2025, while Quinoa-based is the fastest-growing source segment with a CAGR of 10.20% from 2026-2035.
-
By Distribution Channel, Conventional Stores/Supermarkets led the Gluten-Free Products Market with a 71.70% share in 2025, while Online Retail/E-commerce is the fastest-growing distribution channel segment with a CAGR of 10.35% from 2026-2035.
By Product Type, Bakery Products Dominated the Market While Desserts & Ice-Creams Is the Fastest-Growing Segment
The Bakery Products segment led the Gluten-Free Products Market with a revenue share of 31.80% in 2025, due to the rising demand from consumers for substitutes to traditional bakery products such as bread, buns, cakes, and pastries, which do not contain any traces of gluten. Consistent innovation, superior flavor and consistency, and greater availability across various channels help the segment retain its market dominance, thus making bakery products the market leader in the overall gluten-free products market.
The Desserts & Ice-Creams segment is projected to register the fastest CAGR of 10.90% during the forecast period 2026-2035, owing to the increasing consumer consciousness about gluten sensitivity and growing preference for gluten-free lifestyle, leading to a rise in demand for desserts and frozen desserts that are free from any products containing wheat ingredients. Manufacturers have been introducing new products that offer taste and texture similar to those offered by traditional products but without gluten content.
By Source, Rice-based Dominated the Market While Quinoa-based Is the Fastest-Growing Segment
The Rice-based segment led the Gluten-Free Products Market with a revenue share of 32.60% in 2025, due to the extensive use of rice flour in the gluten-free product formulation process. The ingredients used in the preparation of these products have a neutral flavor, easy digestibility, and functional properties suitable for bakery products, snacks, and processed foods. Hence, rice-based ingredients continue to be the favored choice of manufacturers and consumers alike, which keeps this category in the lead in the overall gluten-free product market.
The Quinoa-based segment is expected to register the fastest CAGR of 10.20% during the forecast period 2026-2035, driven by growing consumer preference for premium, nutrient-dense ancient grain alternatives offering superior protein content relative to conventional rice and corn-based formulations. Rising health-conscious consumer interest in functional, nutritionally complete gluten-free ingredients continues to reinforce this segment's above-average growth trajectory.
By Distribution Channel, Conventional Stores/Supermarkets Dominated the Market While Online Retail/E-commerce Is the Fastest-Growing Segment
The Conventional Stores/Supermarkets segment led the Gluten-Free Products Market with a revenue share of 71.70% in 2025, attributed to the fact that supermarkets and hypermarkets constitute one of the largest and easiest to access retail outlets providing varied products for the wide variety of gluten-free products sought by consumers. The conventional stores have consistently offered the greatest access channel to the consumers of gluten-free products.
The Online Retail/E-commerce segment is expected to register the fastest CAGR of 10.35% during the forecast period 2026-2035, on account of the increasing trend towards home delivery services and competitive pricing in conjunction with the great number of gluten-free products available through online retail platforms. Increased consumer interaction through direct-to-consumer channels keeps reinforcing the strong growth performance of this channel.
Regional Analysis
|
Region |
Country |
Share (2025) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
United Kingdom |
22.80% |
|
Asia Pacific |
China |
32.60% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
24.60% |
North America Gluten-Free Products Market Insights
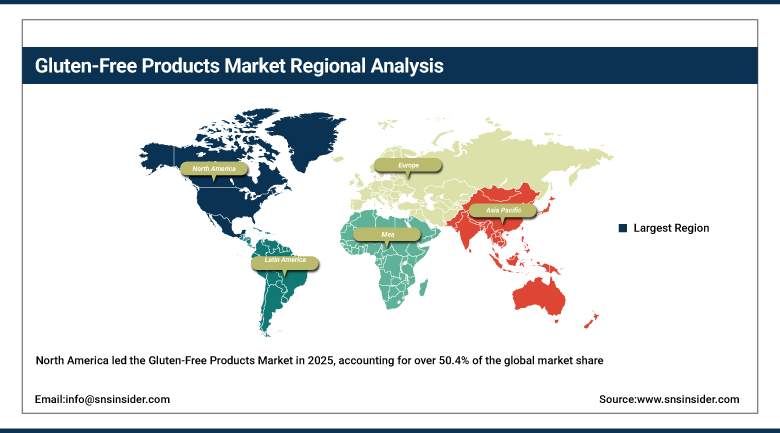
North America led the Gluten-Free Products Market in 2025, accounting for over 50.4% of the global market share. The region’s dominance is supported by high consumer awareness, growing adoption of health-conscious diets, and well-established retail infrastructure. Rising diagnosis of celiac disease and increasing demand for gluten-free food options are further supporting market growth. Additionally, the integration of gluten-free products into mainstream FMCG portfolios and their widespread availability across retail channels continue to strengthen North America’s leading position.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its large health-conscious consumer base and extensive gluten-free product retail infrastructure. Canada is contributing to regional growth through steady celiac disease awareness and growing consumer interest in clean-label, gluten-free food alternatives.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Gluten-Free Products Market Insights
Europe accounted for a considerable percentage of the Gluten-Free Products Market in 2025 due to the presence of strict regulations on gluten-free labeling and existing specialty brands in Europe. Consumer awareness about dietary wellness is driving the demand for gluten-free products. Rising popularity of veganism and plant-based diets is also aiding the growth of the market, especially gluten-free bakery, snacks, and dessert products.
The United Kingdom led the European market with a 22.80% regional share in 2025, supported by strong specialty gluten-free brand presence and growing vegan and gluten-free product category expansion. Germany, France, and Italy are also contributing meaningfully to regional growth, supported by leading global gluten-free bakery companies headquartered across the region.
Asia Pacific Gluten-Free Products Market Insights
Asia Pacific is expected to witness significant growth in the Gluten-Free Products Market due to rising health awareness levels along with the development of retail infrastructure in countries such as China, Japan, and Southeast Asia. Rising income levels, coupled with an increase in the understanding of dietary requirements in relation to gluten, are driving consumers towards healthier food products. This, along with the increased availability of supermarkets, specialty stores, and online retail platforms, is contributing to Asia Pacific's superior growth rate.
China accounted for approximately 32.60% of the Asia Pacific market in 2025, supported by its rapidly expanding health-conscious consumer base and growing domestic gluten-free product manufacturing capacity. Japan, India, and South Korea are also contributing meaningfully to regional growth, with rising awareness of gluten sensitivities and celiac disease across the region's expanding urban centers.
Middle East & Africa and Latin America Gluten-Free Products Market Insights
The Middle East & Africa region is witnessing steady growth in the Gluten-Free Products Market due to increased health and wellness consciousness in the Gulf countries, aided by modern retail infrastructure. Healthier dietary preferences among consumers are boosting the uptake of gluten-free foods. The Latin American region is also recording increased opportunities owing to increased health awareness and increased preference for clean-label food products. The rise in retailing channels such as supermarkets and specialty retailers in major cities is enhancing product availability.
The UAE led the Middle East & Africa market with a 20.60% regional share in 2025, supported by growing health-conscious consumer demand and expanding modern retail penetration. Brazil represented 24.60% of the Latin American market in 2025, driven by expanding gluten-free product consumption, with Mexico also contributing to regional growth through rising celiac disease and gluten sensitivity awareness.
Market Dynamics
Growth Drivers: Celiac Disease Prevalence and Mainstream Portfolio Integration Driving Market Growth
The Gluten-Free Products Market is mainly being fueled due to rise in incidence of celiac disease and gluten sensitivity, growing awareness among consumers about healthy diet, rising trend of clean-label foods, and rising preference for gluten-free lifestyle among health conscious consumers. The market for gluten-free products is moving from a niche, condition-based market towards mainstream functional foods, where growth is increasingly being influenced by regulatory convergence and portfolio integration by major FMCG companies.
Rising shift from a niche, condition-based market towards mainstream functional foods continues to impact competitive landscape. Rising portfolio integration by major FMCG companies is bringing gluten-free products into mainstream, everyday branded foods rather than just specialty foods. Innovation in texture, taste and cost parity continues to close the gap between gluten-free and traditional wheat-based products experience.
Restraints: Higher Production Costs and Ingredient Sourcing Challenges Limiting Market Expansion
Though there is an ideal demand, there are significant constraints that arise due to increased costs of production as well as sourcing high-quality gluten-free raw materials, which might act as challenges for smaller companies trying to compete against established mainstream FMCG brands. Gluten-free bread, cakes, cookies, and muffins still need the expertise of formulating them to match the taste and texture of non-gluten alternatives.
The increasing competitive pressure arising from the presence of more competitors in the industry, especially within the context of the integration of mainstream FMCG brands, is contributing to the squeeze on margins in mainstream products. Competition dynamics of fragmentation, where small and medium-sized firms operate along with large brands, are also contributing to competition pressures.
Opportunities: Texture Innovation and Mainstream Category Convergence Creating New Growth Avenues
Substantial opportunity exists in continued development of texture and taste innovation capable of achieving genuine cost and sensory parity with conventional wheat-based products. Companies that successfully commercialize gluten-free formulations indistinguishable from traditional alternatives stand to capture significant share of category growth as mainstream consumer adoption continues expanding beyond medically necessary purchasers.
Growing plant-based and clean-label trend convergence presents a further significant growth avenue, as manufacturers increasingly combine gluten-free positioning with broader dietary trend alignment to appeal to health-conscious consumers seeking multiple functional benefits. Expanding e-commerce distribution and specialty store curation also represent meaningful untapped opportunity for gluten-free product manufacturers seeking premium positioning.
Recent Developments:
-
2026: Bob's Red Mill announced a perfected formula for its Gluten Free 1-to-1 Baking Flour, delivering improved taste and texture, rolling out nationwide at major retailers including Costco, Whole Foods, and Kroger.
-
2025: Schar launched a new line of gluten-free and vegan cakes in the United Kingdom, responding to growing demand for vegan and gluten-free bakery items.
-
2025: Simple Mills announced the launch of its new line of grain-free and gluten-free baking mixes, including cake, brownie, and pancake mixes.
-
2025-2026: The gluten-free bakery market continued attracting a highly fragmented competitive landscape, with numerous small and medium-sized companies expanding into adjacent snacks and breakfast categories.
Gluten-Free Products Market key players are:
-
General Mills, Inc.
-
Dr. Schär AG / SPA
-
Conagra Brands, Inc.
-
The Hain Celestial Group, Inc.
-
Nestlé S.A.
-
Barilla Group
-
WK Kellogg Co.
-
Bob’s Red Mill Natural Foods, Inc.
-
The Kraft Heinz Company
-
Enjoy Life Foods
-
Hero Group AG
-
Freedom Foods Group Limited
-
Genius Foods Ltd.
-
Amy’s Kitchen, Inc.
-
Kinnikinnick Foods
-
Nature’s Path Foods
-
Farmo S.p.A.
-
Raisio plc
-
Cerealto
-
Warburtons Ltd.
Gluten-Free Products Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.50 Billion |
| Market Size by 2035 | USD 33.70 Billion |
| CAGR | CAGR of 9.6% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Bakery Products, Snacks & RTE Products, Pizzas & Pastas, Desserts & Ice-Creams) • By Source (Rice-based, Corn, Quinoa) • By Distribution Channel (Conventional Stores/Supermarkets & Hypermarkets, Specialty Stores, Online Retail) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | General Mills, Inc., Dr. Schär AG / SPA, Conagra Brands, Inc., The Hain Celestial Group, Inc., Nestlé S.A., Barilla Group, WK Kellogg Co., Bob’s Red Mill Natural Foods, Inc., The Kraft Heinz Company, Enjoy Life Foods, Hero Group AG, Freedom Foods Group Limited, Genius Foods Ltd., Amy’s Kitchen, Inc., Kinnikinnick Foods, Nature’s Path Foods, Farmo S.p.A., Raisio plc, Cerealto, Warburtons Ltd. |
Frequently Asked Questions
The Gluten-Free Products Market is expected to grow at a CAGR of 9.6% from 2026 to 2035.
The Gluten-Free Products Market was valued at USD 13.50 Billion in 2025.
The market is driven by the increasing prevalence of celiac disease and gluten intolerance, rising consumer awareness regarding healthy diets, and growing demand for clean-label foods.
The Bakery Products segment dominated the Gluten-Free Products Market in 2025, accounting for approximately 31.80% market share.
The North America region dominated the Gluten-Free Products Market in 2025, accounting for over 50.4% market share.
