
Hazardous Disposal Bag Market Report Scope & Overview:
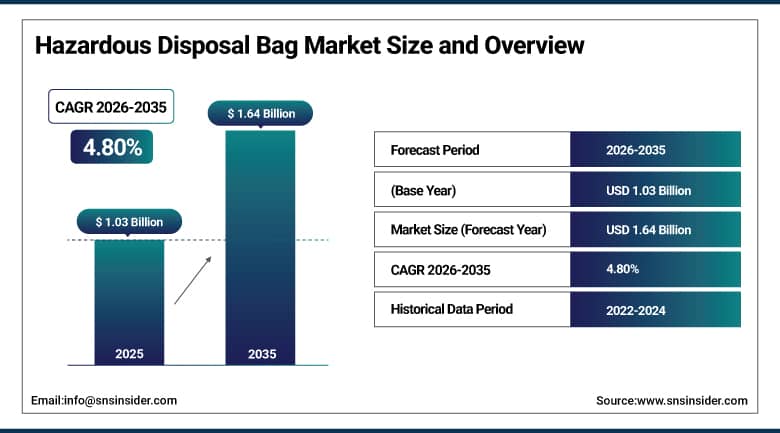
The Hazardous Disposal Bag Market was valued at USD 1.03 Billion in 2025 and is expected to reach USD 1.64 Billion by 2035, growing at a CAGR of 4.80% from 2026 to 2035.
The hazardous disposal bag does not look like a complicated product until you consider what it is actually protecting against, punctures from used syringes, chemical leakage that could contaminate an entire waste stream, or biological material that needs to stay fully contained from the moment it is discarded until it reaches proper disposal. More than 67% of healthcare institutions now use dedicated disposal bags to manage hazardous waste while meeting regulatory and safety standards, and that reliance has only grown as infection control practices tighten and waste management regulation gets stricter across most major markets. Consolidation is also reshaping the industry from the service side, the 2024 acquisition of Stericycle by WM for USD 7.2 billion brought together the country's largest solid waste and medical waste disposal operations under one roof.
In this context, Stericycle, Inc., a firm whose value was US$ 7.2 billion at the time of its acquisition by WM (Waste Management, Inc.), which was completed in November 2024, provided the segment's services that generated synergies amounting to US$ 250 million within three years.
To Get More Information On Hazardous Disposal Bag Market - Request Free Sample Report
Hazardous Disposal Bag Market Trends
- Biodegradable material options are expanding as healthcare and industrial customers seek more sustainable disposal solutions.
- Larger-capacity bags are gaining share as industrial and healthcare facilities manage growing volumes of hazardous waste.
- Consolidation among waste management service providers is reshaping which suppliers control disposal bag specification and procurement.
- Color-coded bag systems are becoming more standardized to help facilities segregate different hazardous waste streams accurately.
- Research laboratory demand is expanding as pharmaceutical and biotechnology R&D activity grows globally.
The U.S. Hazardous Disposal Bag Market Outlook
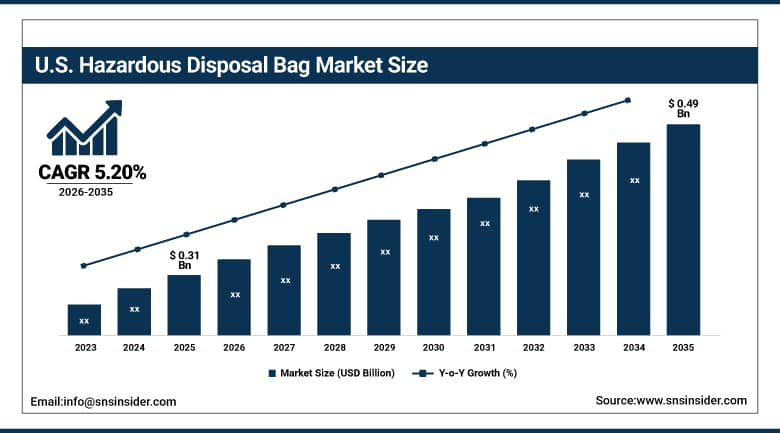
The U.S. Hazardous Disposal Bag Market was valued at USD 0.31 Billion in 2025 and is projected to reach USD 0.49 Billion by 2035, growing at a CAGR of 5.20% during 2026-2035.
Government intervention continues to play an active role in influencing demand in the domestic market in ways not seen in other industries, as evident in the changes proposed by EPA for 2024 regarding hazardous waste correction actions. Hospitals and diagnostic laboratories continue to make up the biggest demand generator due to increased activities within the sector and the continual production of biohazardous wastes. Consolidation of the top service providers within the industry through mergers such as that of Waste Management with Stericycle will increase specification requirements and the number of buyers, who include hospitals and research laboratories. The latter segment continues to exhibit increased demand due to growing R&D efforts within the pharmaceutical and biotechnology sectors.
In 2025, WM continued integrating Stericycle's medical waste operations, targeting approximately USD 100 million in synergies during the year through combined route density and cross-selling of hazardous and medical waste disposal services.
Hazardous Disposal Bag Market Segment Analysis
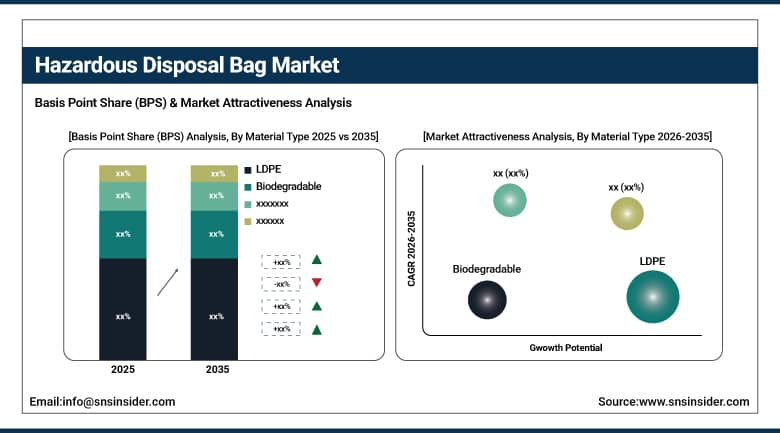
- By Material Type, LDPE segment dominated the hazardous disposal bag market in 2025 with 46% share; biodegradable segment is the fastest-growing segment, registering a CAGR of 7.40% from 2026 to 2035.
- By Capacity, medium (20-60 liters) segment dominated the hazardous disposal bag market in 2025 with 48% share; large (above 60 liters) segment is the fastest-growing segment, registering a CAGR of 6.80% from 2026 to 2035.
- By Bag Type, biohazard bags segment dominated the hazardous disposal bag market in 2025 with 44% share; chemical waste bags segment is the fastest-growing segment, registering a CAGR of 7.20% from 2026 to 2035.
- By End-Use Industry, healthcare segment dominated the hazardous disposal bag market in 2025 with 41% share; laboratories & research segment is the fastest-growing segment, registering a CAGR of 6.70% from 2026 to 2035.
By Material Type, LDPE dominates the hazardous disposal bag market while biodegradable grows fastest
LDPE commands 46% share of the market by type of material and continues to be the preferred option simply because of the fact that it is moldable to various sizes and gauges along with providing the flexibility and tear resistance that waste containment needs to have. The sealability of LDPE, along with its proven history in both the health care and industrial sectors, makes LDPE the obvious choice.
Biodegradable materials are growing fastest, at a 7.40% CAGR, as technological advancements in biodegradable plastic formulations open genuine new avenues for manufacturers responding to sustainability pressure without compromising the containment performance hazardous waste disposal demands. Facilities increasingly weighing environmental impact alongside safety compliance are driving early adoption of these alternatives, particularly in markets with strong regulatory or institutional sustainability commitments.
By Capacity, medium (20-60 liters) dominates the hazardous disposal bag market while large (above 60 liters) grows fastest
The medium capacity range, 20 to 60 liters, accounts for 48% of the market, sitting at the size most commonly used across standard healthcare and laboratory waste bins where daily hazardous waste volumes fit comfortably without requiring frequent bag changes or oversized containment. This range has become something close to a facility standard, which keeps procurement and waste management workflows consistent across most healthcare and laboratory settings.
Large-capacity bags, above 60 liters, are growing fastest, at a 6.80% CAGR, as industrial facilities and larger healthcare systems managing higher hazardous waste volumes look for ways to reduce the frequency of bag changes and associated handling labor. This trend tracks closely with rising overall hazardous waste generation across healthcare, pharmaceutical, and industrial sectors, where efficiency gains from fewer, larger containment units matter increasingly to facility operations.
By Bag Type, biohazard bags dominates the hazardous disposal bag market while chemical waste bags grows fastest
Biohazard Bags hold 44% of the market by bag type, the largest single category, reflecting how central biological waste containment is to healthcare and laboratory operations where infection control depends directly on reliable, clearly identified disposal packaging. Standardized color coding and labeling requirements have made biohazard bags close to a universal fixture in any facility handling infectious or potentially contaminated materials.
Chemical waste bags have emerged as the fastest-growing category of bags, with a 7.20% CAGR, owing to the strict regulations governing chemical waste management from industrial plants and the growing need for more customized options that cannot be fulfilled by conventional bags. The rise in generation of hazardous industrial wastes along with increasing compliance with chemical waste management regulations is driving the growth of the market.
By End-Use Industry, healthcare dominates the hazardous disposal bag market while laboratories & research grows fastest
Healthcare accounts for 41% of the hazardous disposal bag market, the largest single end-use industry, reflecting the sheer volume of hazardous waste that hospitals, clinics, and diagnostic laboratories generate daily, syringes, gloves, bandages, and surgical tools that all require safe containment and disposal to prevent infection spread. Also, regulatory requirements for medical waste management are one of the strictest in comparison to all other industries. This fact ensures the demand for proper medical waste disposal bags will remain stable in any case despite the state of economy.
Laboratories & research is the fastest growing end-user industry that experiences an annual growth rate of 6.70%. This is explained by increasing number of activities conducted in the pharmaceutical and biotechnology sectors on the global scale. These activities create specific hazardous waste, which needs a special treatment. Besides, due to increased R&D budgets and establishment of new laboratories, the demand in the market is growing.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.20% |
|
Asia Pacific |
China |
34.80% |
|
Europe |
Germany |
25.40% |
|
Middle East & Africa |
UAE |
17.60% |
|
Latin America |
Brazil |
26.30% |
North America Hazardous Disposal Bag Market Insights
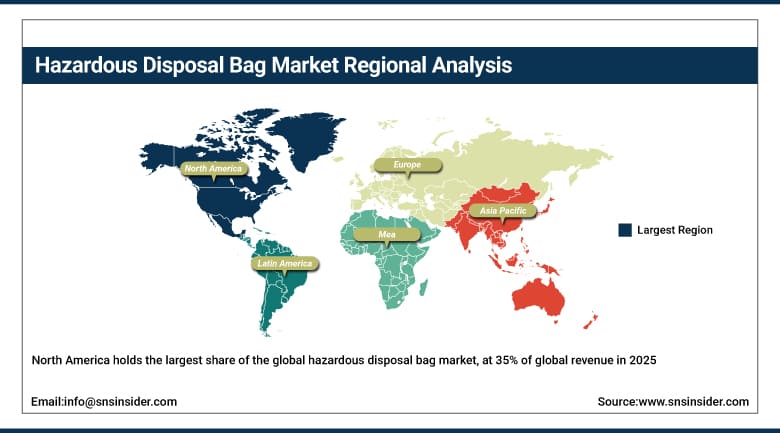
North America holds the largest share of the global hazardous disposal bag market, at 35% of global revenue in 2025, supported by well-established healthcare systems and strict environmental regulations, including the U.S. EPA's 2024 amendment impacting hazardous waste corrective actions, that mandate proper waste disposal practices across nearly every industry. Despite the growing maturity of the market, high levels of awareness related to occupational safety and infection control will ensure continuous demand.
The U.S. constitutes 85.20% of the North American market owing to the huge healthcare sector and hazardous waste generation in the country. Canada holds a minor yet significant part of the market attributed to its health care sector and hazardous waste regulations.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Hazardous Disposal Bag Market Insights
Europe holds a substantial 25% share of the global hazardous disposal bag market, supported by comprehensive waste management regulation and well-established healthcare systems that have long treated proper hazardous waste containment as standard, non-negotiable practice. Strict environmental compliance requirements across the region continue reinforcing steady demand even as growth in absolute terms remains more measured than in Asia Pacific.
Germany leads the European market with a 25.40% share, supported by its large healthcare system and strict regulatory compliance standards. France and the United Kingdom follow, with demand in both countries tied to established healthcare infrastructure and comprehensive waste management regulation.
Asia Pacific Hazardous Disposal Bag Market Insights
Asia Pacific is growing faster than any other region in this market, expanding at a 6-7% CAGR, supported by the region's rapidly growing pharmaceutical industry, valued at more than USD 600 billion, alongside expanding healthcare infrastructure and rising industrialization across China and India. Rapid urbanization and growing healthcare access in markets where modern waste management practices are still developing are creating exactly the kind of first-time adoption growth that mature markets like North America can no longer generate.
China holds roughly 34.80% of the regional market, supported by its expanding pharmaceutical manufacturing base and growing healthcare infrastructure. India is growing quickly as healthcare access and pharmaceutical production both expand, while Japan and South Korea contribute through their established, quality-focused healthcare and industrial waste management sectors.
Middle East & Africa and Latin America Hazardous Disposal Bag Market Insights
The Middle East & Africa region is experiencing gradual growth on account of increasing investment in medical facilities in the Gulf nations, along with increasing emphasis on effective methods for disposal of waste in the region. The case is similar in Latin America, where the reason behind gradual growth is the growing healthcare infrastructure in Brazil and industrial hazardous waste production in the region.
The UAE dominates the Middle East & Africa region with a market share of 17.60%, owing to its growing healthcare infrastructure and being a hub for distribution of medical supplies in the region. In Latin America, Brazil accounts for a share of 26.30%, which is largely attributed to its growing healthcare system, followed by Mexico through its industrial and pharmaceutical sectors.
Market Dynamics
Growth Drivers: Healthcare Waste Generation and Regulatory Compliance Fueling Market Growth
The growing trend of health care activities in the world, along with the increase in volume of infectious and biohazardous waste, is undoubtedly one of the major factors leading to the growth of this market due to the necessity of containment solutions for hospital and clinic waste management. The stricter regulatory requirements for proper hazardous waste disposal in health care, pharmaceutical, and industry sectors make it an essential need for disposal bags rather than a luxury item.
Growing pharmaceutical and biotechnology research activity is adding a meaningful additional demand line, as expanding laboratory facilities generate specialized hazardous waste requiring careful, category-specific containment solutions.
Restraints: Material Cost Volatility and Alternative Disposal Method Competition Limiting Market Expansion
Resin price volatility for LDPE and HDPE, tied to broader petrochemical commodity markets, makes it difficult for disposal bag manufacturers to hold pricing steady with healthcare and industrial customers on long-term supply contracts. Alternatives to waste containment include the use of containers that contain hazardous waste, which could be competitive with bags when puncture resistance and extended shelf life become more important than the flexibility of bags.
Requirements related to the issue in question vary greatly by country and type of waste, making it truly complex to comply when trying to sell standardized products around the world.
Opportunities: Biodegradable Materials and Consolidation-Driven Standardization Creating New Growth Avenues
Biodegradable material innovation represents a clear growth opportunity as healthcare and industrial customers increasingly weigh environmental impact alongside safety compliance, particularly in markets with strong institutional sustainability commitments. Manufacturers who can develop biodegradable formulations that maintain full containment performance stand to capture premium positioning as this consumer and regulatory preference continues building.
Consolidation among major waste management service providers offers a second opportunity, as combined entities standardize disposal bag specifications across larger customer networks, creating scale opportunities for suppliers who can meet the more rigorous compliance and volume requirements these larger buyers demand.
Recent Developments:
- 2024: WM (Waste Management, Inc.) completed its USD 7.2 billion acquisition of Stericycle, Inc., adding regulated medical waste and secure information destruction services and creating combined synergies expected to reach USD 250 million over three years.
- 2025: WM continued integrating Stericycle's medical waste operations, targeting approximately USD 100 million in synergies during the year through combined route density and cross-selling of hazardous and medical waste disposal services.
- 2025: Clean Harbors, Inc. continued expanding its hazardous waste collection and disposal network following its 2022 acquisition of Heritage-Crystal Clean, strengthening its position across industrial and used-oil waste streams.
- 2025: Veolia Environnement S.A. continued expanding its regulated waste containment and disposal bag supply chain across Europe and North America to support growing healthcare and industrial hazardous waste volumes.
Hazardous Disposal Bag Market key players are:
- Stericycle, Inc.
- Clean Harbors, Inc.
- Veolia Environnement S.A.
- Waste Management, Inc.
- Republic Services, Inc.
- Amcor plc
- Novolex Holdings, LLC
- Poly-America, L.P.
- Inteplast Group
- Cesco Solutions
- Colonial Bag Corporation
- American Bag & Tag Corp.
- Medegen Medical Products, LLC
- Bemis Manufacturing Company
- Thermo Fisher Scientific Inc.
- Cardinal Health, Inc.
- Daniels Health
- MedPro Disposal
- Medtronic plc
- Suez S.A.
Hazardous Disposal Bag Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.03 Billion |
| Market Size by 2035 | USD 1.64 Billion |
| CAGR | CAGR of 4.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (LDPE, HDPE, Biodegradable, Others) • By Capacity (Small (Below 20 Liters), Medium (20-60 Liters), Large (Above 60 Liters)) • By Bag Type (Biohazard Bags, Chemical Waste Bags, Sharps Container Liners, Others) • By End-Use Industry (Healthcare, Industrial & Chemical, Laboratories & Research, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stericycle, Inc., Clean Harbors, Inc., Veolia Environnement S.A., Waste Management, Inc., Republic Services, Inc., Amcor plc, Novolex Holdings, LLC, Poly-America, L.P., Inteplast Group, Cesco Solutions, Colonial Bag Corporation, American Bag & Tag Corp., Medegen Medical Products, LLC, Bemis Manufacturing Company, Thermo Fisher Scientific Inc., Cardinal Health, Inc., Daniels Health, MedPro Disposal, Medtronic plc, Suez S.A. |
Frequently Asked Questions
Key players include Stericycle, Inc., Clean Harbors, Inc., Veolia Environnement S.A., Waste Management, Inc., and Republic Services, Inc., alongside other established waste management and disposal bag manufacturers.
Key opportunities include biodegradable material innovation for sustainability-conscious healthcare and industrial customers, standardized disposal bag specification driven by waste management provider consolidation, and expanding research laboratory demand tied to pharmaceutical and biotechnology growth.
The market is driven by rising healthcare waste generation, tightening regulatory frameworks mandating proper hazardous waste disposal, and growing pharmaceutical and biotechnology research activity.
The Healthcare segment dominated the Hazardous Disposal Bag Market in 2025.
The North America region dominated the Hazardous Disposal Bag Market in 2025, accounting for approximately 35% of global market share.
