
Healthcare Fraud Detection Market Report Scope & Overview:
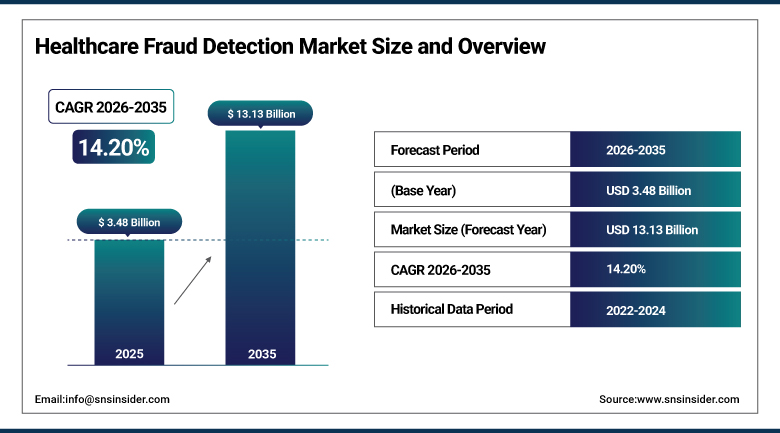
The Healthcare Fraud Detection Market was valued at USD 3.48 Billion in 2025 and is expected to reach USD 13.13 Billion by 2035, growing at a CAGR of 14.20% from 2026-2035.
The Healthcare Fraud Detection Market is expanding as payers and public programs adopt analytics and artificial intelligence to identify improper billing before and after claims are paid. Growth is driven by rising claim volumes, the digitization of health records, increasingly organized fraud schemes and tighter regulatory scrutiny of improper payments. Vendors combine rules engines, anomaly detection, network analysis and machine learning with investigator workflows, and many now offer managed services that pair technology with clinical and coding experts.
⮞On November 18, 2024, Cotiviti introduced 360 Pattern Review at the NHCAA Annual Training Conference, a fully managed service that combines prepay claim pattern review with postpay fraud, waste and abuse analysis and is supported by more than 70 credentialed investigative and clinical analysts. The company said it identified about USD 15 billion in suspect claims across its fraud, waste and abuse clients in 2023, which illustrates the scale of the problem payers are trying to address.
To Get more information Healthcare Fraud Detection Market - Request Free Sample Report
Healthcare Fraud Detection Market Trends
- Machine learning and generative AI models for claims and documentation review
- Shift from pay-and-chase recovery to prepayment fraud prevention
- Cloud-based deployment and real-time claims scoring
- Detection of manipulated or AI-generated medical documentation
- Managed services combining technology with clinical and coding experts
- Data sharing and network analysis across payers and government programs
U.S. Healthcare Fraud Detection Market Outlook
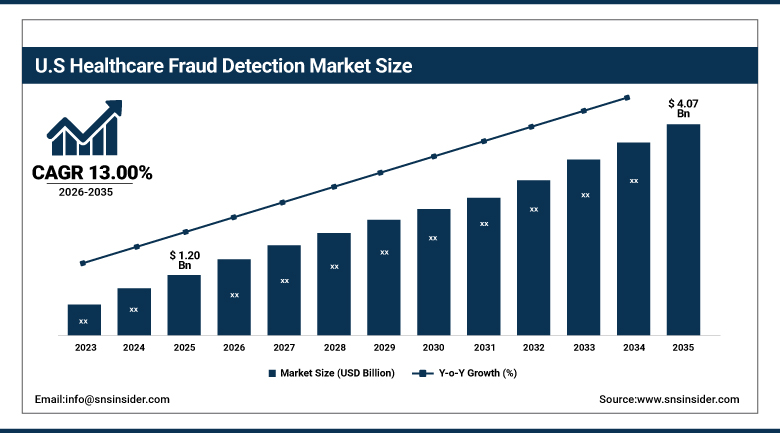
The U.S. Healthcare Fraud Detection Market was valued at USD 1.20 Billion in 2025 and is expected to reach USD 4.07 Billion by 2035, growing at a CAGR of 13.00% from 2026-2035.
The U.S. Healthcare Fraud Detection Market is the largest national market, supported by the scale of Medicare, Medicaid and commercial insurance spending, a large body of anti-fraud regulation and active enforcement by the Department of Justice and the HHS Office of Inspector General. The National Health Care Anti-Fraud Association has estimated that fraud accounts for at least 3% of health spending. Payers and government contractors invest in prepayment edits, provider scoring and investigator tools, and demand is rising for solutions that identify telehealth, laboratory, durable equipment and home health schemes.
⮞In March 2026, Codoxo launched an artificial intelligence tool designed to flag AI-generated or manipulated medical documentation and images submitted with claims. The product responds to concern among U.S. payers that generative tools could be used to fabricate records at scale, and it reflects how vendors are extending fraud analytics from billing data into the supporting clinical evidence.
Healthcare Fraud Detection Market Segment Analysis
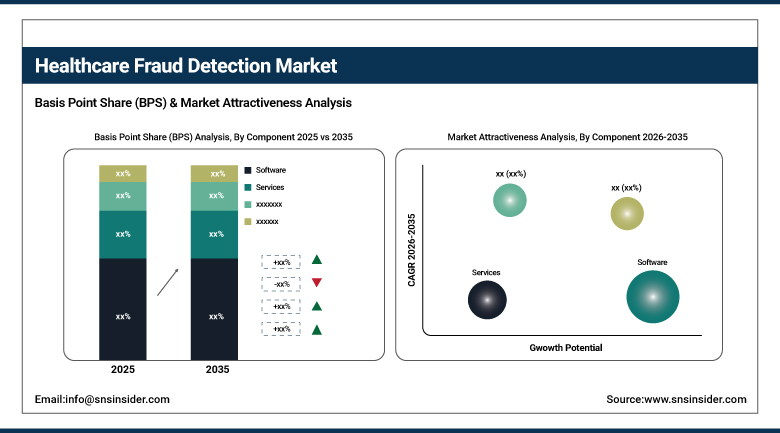
- By Component, software segment dominated the Healthcare Fraud Detection Market in 2025 with 58.20% share; services segment is the fastest-growing segment, with an estimated CAGR of 10.80% during 2026–2035.
- By Type, descriptive analytics segment dominated the Healthcare Fraud Detection Market in 2025 with an estimated 46.00% share; predictive analytics segment is the fastest-growing segment, with an estimated CAGR of 16.20% during 2026–2035.
- By Delivery Mode, cloud-based segment dominated the Healthcare Fraud Detection Market in 2025 with 64.10% share, and is also the fastest-growing segment, with an estimated CAGR of 15.60% during 2026–2035.
- By Application, insurance claims review segment dominated the Healthcare Fraud Detection Market in 2025 with 53.30% share; payment integrity segment is the fastest-growing segment, with an estimated CAGR of 12.00% during 2026–2035.
- By End User, private insurance payers segment dominated the Healthcare Fraud Detection Market in 2025 with 43.20% share; public and government agencies segment is the fastest-growing segment, with an estimated CAGR of 11.60% during 2026–2035.
By Component, Software Dominates Healthcare Fraud Detection Market; Services to Register Fastest Growth.
Software dominates the Healthcare Fraud Detection Market because payers need platforms that score claims, detect anomalies and manage investigations at the volumes processed every day. Rules engines, machine learning models and network analysis are licensed or hosted as subscriptions that integrate with claims adjudication systems, and large insurers prefer to own core analytics assets. Vendors are adding natural language tools to review clinical notes and documents, which expands the software layer beyond billing data and strengthens switching costs. Cloud-hosted software also eases frequent updates.
Services are projected to register the fastest growth as payers seek managed offerings that combine technology with clinical coders, nurses and investigators who review flagged claims and recover payments. Many health plans lack the specialist staff needed to act on model output, so vendors sell prepayment review, special investigation unit support and recovery audit work under outcome-based contracts. Implementation, model tuning and training also add consulting revenue as data sources multiply. Outcome-based pricing aligns vendor fees with recovered savings, which attracts cost-conscious plans.
By Type, Descriptive Analytics Dominates Healthcare Fraud Detection Market; Predictive Analytics to Register Fastest Growth.
Descriptive analytics dominates the Healthcare Fraud Detection Market because dashboards, billing pattern reports and peer-comparison tools are the first step in any fraud program and require less data science expertise than advanced models. Payers and government contractors use them to find outliers by provider, procedure code and geography, and to support audits and regulatory reporting. Their lower cost and ease of interpretation make them widely used even where more advanced analytics are being introduced. These reports also inform provider education and contract negotiation.
Predictive analytics is projected to register the fastest growth as insurers shift from recovering money after payment toward preventing improper claims before they are paid. Machine learning models trained on historical claims score each submission for risk in near real time, and supervised and unsupervised methods are combined to detect new schemes. Prescriptive analytics follows, recommending actions such as pending a claim, requesting records or referring a provider, though adoption is limited by the need for explainable decisions. Vendors invest heavily in feature engineering from procedure, diagnosis and provider network data.
By Delivery Mode, Cloud-Based Dominates Healthcare Fraud Detection Market and Is Also the Fastest-Growing Delivery Mode.
Cloud-based delivery dominates the Healthcare Fraud Detection Market because it allows payers to scale analytics quickly, ingest claims from multiple sources and update models without long hardware cycles. Vendors operate secure environments that meet healthcare privacy and security requirements, and payers value shorter deployment times and lower infrastructure cost. Cloud platforms also make it easier to share threat intelligence across clients and to deliver real-time claim scoring through application interfaces. Continuous monitoring is easier to deliver from shared platforms. Updates are delivered continuously.
Cloud-based deployment is also expected to be the fastest-growing delivery mode as government programs and smaller plans move away from legacy systems. On-premise installations remain in use where data residency rules, security policies or existing investments favor local control, particularly among large government agencies. Hybrid arrangements, in which sensitive data remains local while analytics run in the cloud, are emerging as a compromise that supports modernization without requiring full migration. Regulators increasingly accept cloud controls that meet recognized security frameworks.
By Application, Insurance Claims Review Dominates Healthcare Fraud Detection Market; Payment Integrity to Register Fastest Growth.
Insurance claims review dominates the Healthcare Fraud Detection Market because reviewing submitted claims for coding errors, duplicate billing, unbundling and upcoding is the core activity of payer fraud, waste and abuse programs. Payers apply edits and models across professional, facility, pharmacy and dental claims, and government programs run similar reviews at large scale. The volume of claims and the measurable savings from denied or recovered payments justify steady investment in this application. Payers also use review results to refine edits and provider education.
Payment integrity is projected to register the fastest growth as payers expand programs that verify coverage, coordination of benefits, medical necessity and contract compliance before and after payment. This broader approach combines fraud detection with claims editing and recovery, and it attracts budgets from finance as well as special investigation units. Identity management and pharmacy billing applications also grow as telehealth, specialty drugs and synthetic identities create new risks for payers and pharmacy benefit managers. Specialty drug and compounded medication billing add further review work for pharmacy benefit teams.
By End User, Private Insurance Payers Dominate Healthcare Fraud Detection Market; Public and Government Agencies to Register Fastest Growth.
Private insurance payers dominate the Healthcare Fraud Detection Market because they process large claim volumes, bear the direct cost of improper payments and compete on cost control. Commercial plans and managed care organizations run special investigation units and contract with analytics and recovery vendors. Pressure to hold premiums down pushes plans to invest in prepayment analytics, provider scoring and automated review that reduce manual work and speed claim adjudication. Employers that self-insure also fund fraud programs through their administrators. Administrators help here too.
Public and government agencies are projected to register the fastest growth as Medicare, Medicaid and national insurance schemes expand and face scrutiny over improper payments. Legislation and enforcement programs require agencies and their contractors to adopt analytics, and new public insurance programs in emerging markets create demand for fraud controls from the start. Third-party service providers, hospitals and healthcare providers also invest, using tools to protect revenue integrity and to respond to payer audits. Cross-agency data sharing programs further extend analytics use across public insurers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
80.00 |
|
Europe |
Germany |
26.58 |
|
Asia Pacific |
China |
34.91 |
|
Latin America |
Brazil |
52.64 |
|
Middle East & Africa |
United Arab Emirates |
31.27 |
North America Healthcare Fraud Detection Market Insights
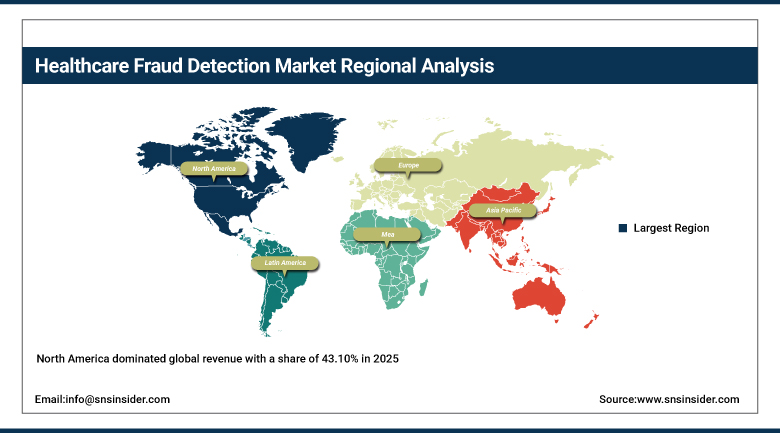
North America dominated global revenue with a share of 43.10% in 2025, supported by the scale of Medicare, Medicaid and commercial insurance spending, extensive anti-fraud regulation and active enforcement by the Department of Justice and the HHS Office of Inspector General. The United States accounts for most regional demand, with vendors such as Optum, Cotiviti and Conduent based in the region. Large health plans also run in-house data science teams that complement vendor platforms.
Payers and government contractors invest in prepayment edits, provider scoring and investigator tools, and demand is rising for solutions that identify telehealth, laboratory, durable equipment and home health schemes. Canada adds demand through provincial claims programs. High adoption and market saturation moderate growth relative to emerging regions, and data privacy rules require careful handling of protected health information. Whistleblower recoveries and settlements keep the financial case for detection visible to executives and boards. Rural hospital billing and ambulance services also draw attention.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Healthcare Fraud Detection Market Insights
Europe is growing at a CAGR of 13.20% during 2026-2035. Germany leads through its statutory health insurance funds, which are required to operate units that investigate misconduct, followed by France, the United Kingdom, Italy and Spain. Shift Technology, based in France, supplies insurance fraud analytics to payers in several countries. Switzerland and the Netherlands also operate strict insurer oversight that supports analytics adoption. Austria and Belgium add smaller national programs, and the Nordic countries run advanced claims data systems.
The General Data Protection Regulation limits how health data can be shared and processed, which shapes deployment and favors vendors with strong privacy controls. Public systems such as the National Health Service in the United Kingdom run counter-fraud functions, and growing private health insurance in several countries adds demand. Cross-border data sharing is limited, so analytics are often tuned to national billing codes and reimbursement rules. Vendors also respond with in-region hosting and pseudonymization features to address privacy requirements. Fragmented payer structures slow regional standardization.
Asia Pacific Healthcare Fraud Detection Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 17.60% from 2026-2035. China leads regional demand as national insurance schemes expand, followed by India, Japan, South Korea and Australia. India's government health insurance programs and a large private insurance base create demand for claims analytics, and MediBuddy's Sherlock system shows local vendors entering the market. Australia contributes through Medicare compliance programs that audit provider billing. Singapore and Thailand add demand through hospital networks and insurers that are modernizing claims workflows.
Rising health insurance coverage, digitization of claims and growing awareness of improper payments are the main growth factors. Japan and South Korea run mature national insurance systems that use claims review, while Southeast Asian economies are building digital claims platforms. Limited data quality, fragmented provider networks and varying regulations slow adoption in some countries, although cloud delivery lowers the barrier for payers with smaller budgets. Public-private partnerships and regional technology service firms support deployment in emerging economies. Language and coding differences require tailored models. Cloud service providers also expand local data centers.
MEA & Latin America Healthcare Fraud Detection Market Insights
In Latin America, Brazil leads through its large private health plan sector and public system, followed by Mexico, Argentina and Colombia. Health plans face rising costs from unnecessary procedures and billing abuse, and regulators encourage better controls. Growing insurance penetration and digital claims are creating demand for analytics, although budget limits and uneven data quality constrain adoption. Chile and Peru add smaller volumes as private insurers digitize claims. Colombia adds demand through its health insurance system, where regulators monitor billing by provider networks.
In the Middle East and Africa, the United Arab Emirates and Saudi Arabia lead through mandatory health insurance schemes that require electronic claims, while South Africa has an established private medical scheme sector. Regulators in Gulf countries are strengthening claims oversight and payers are adopting analytics to manage cost growth. Limited insurance coverage in much of Africa restricts demand beyond a few large markets. Regional consultancies and global vendors often partner to deliver analytics under multi-year contracts. Egypt and Qatar are also introducing digital claims platforms.
Market Dynamics
Growth Drivers: Rising Claim Volumes and Regulatory Pressure to Reduce Improper Payments
Increases in claims volume and increases in the complexity of billing are the driving forces behind fraud analytics demand. Telemedicine, specialty pharmacy, genetic testing and home healthcare are some of the newer billing categories, which allow schemes to work in the spaces that have not been defined between them yet. Millions of claims daily cannot be reviewed manually, therefore, payers start using automated methods of scoring, anomaly detection and network analysis to process each claim and choose those that are suspicious to review.
Political and regulatory pressure on reduction of improper payments is another driving factor behind fraud analytics. Programs of the government get investigated and criticized for losses. Enforcing agencies increase their data-based prosecution efforts. Payers unable to create an efficient anti-fraud program will suffer from it and continue to invest. Development of cloud computing and machine learning technology made it cheaper to use advanced analytics models, even for small-scale insurance companies and third-party administrators.
Restraints: Data Privacy Constraints, Legacy Systems and False Positives
Data privacy and security constraints pose obstacles for fraud detection initiatives, since fraud detection requires granular patient and provider data that is highly regulated. Regulations surrounding protected health information impose barriers to data exchange between payers, providers and vendors, with international transfers being especially challenging. Compliance constraints increase expenses and extend the time-to-procurement, while payers are hesitant to migrate sensitive claims data to external environments, thus impeding the adoption of cloud and consortium approaches.
Another obstacle for implementation comes from the use of legacy claims management systems and poor accuracy of models. Fragmented claims platforms and varying coding used by many payers hinder data integration and reduce its quality. High false positives impose heavy workloads on investigators and negatively impact provider relations, since legitimate claims can get delayed or declined. There is a lack of data scientists and clinicians who have experience in fraud detection modeling, thus making vendor-managed services a must for adoption.
Opportunities: Generative AI Detection, Prepayment Prevention and Emerging Markets
Generative AI offers opportunities on both sides of the problem. Fraudsters can create convincing false documentation, which creates demand for tools that detect manipulated records and images, as illustrated by Codoxo's March 2026 launch. Vendors can also apply large language models to summarize investigation files, read clinical notes and match documentation to billed codes, improving investigator productivity and enabling new products that complement traditional analytics and rules.
Prepayment prevention and emerging markets provide additional opportunity. Shifting from pay-and-chase recovery to preventing improper payments improves payer economics and supports outcome-based pricing. Expanding public insurance programs in India, China, the Middle East and Latin America are building digital claims systems with fraud controls included, and vendors that offer cloud platforms, local language support and partnerships with insurers and system integrators can capture a growing share of new programs throughout the forecast period.
Recent Developments:
- In March 2026, Codoxo launched an artificial intelligence tool that flags AI-generated or manipulated medical documentation and images submitted with claims. The product extends fraud analytics from billing data to the clinical evidence behind each claim.
- In August 2025, Cognizant launched a suite of machine learning tools for real-time analysis of claims data. The tools are intended to help payers detect anomalies earlier in the adjudication process.
- In September 2024, Microblink set up its Fraud Lab to improve identity fraud detection using artificial intelligence-based verification. The lab supports identity checks that are relevant to enrollment and claims fraud.
- In August 2024, MediBuddy launched Sherlock, an artificial intelligence-powered system for detecting fraudulent healthcare reimbursement claims in real time. The system targets reimbursement abuse in the Indian insurance and corporate benefits market.
Healthcare Fraud Detection Market Key Players are:
- Optum, Inc. (UnitedHealth Group)
- Cotiviti, Inc.
- Conduent Incorporated
- CGI Inc.
- ExlService Holdings, Inc.
- Fair Isaac Corporation
- SAS Institute Inc.
- HCL Technologies Limited
- Wipro Limited
- Codoxo
- Cognizant Technology Solutions Corporation
- Gainwell Technologies LLC
- Shift Technology
- LexisNexis Risk Solutions
- Thomson Reuters Corporation
- Qlarant Quality Solutions, Inc.
- Northrop Grumman Corporation
- Healthcare Fraud Shield, Inc.
- Zelis
- Claritev Corporation
Healthcare Fraud Detection Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.48 Billion |
| Market Size by 2035 | USD 13.13 Billion |
| CAGR | CAGR of 14.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Services) • By Type (Descriptive Analytics, Predictive Analytics, and Prescriptive Analytics) • By Delivery Mode (Cloud-Based and On-Premise) • By Application (Insurance Claims Review, Payment Integrity, Identity Management, Pharmacy Billing Issues, and Others) • By End User (Private Insurance Payers, Public and Government Agencies, Third-Party Service Providers, Hospitals and Healthcare Providers, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Optum, Inc. (UnitedHealth Group); Cotiviti, Inc.; Conduent Incorporated; CGI Inc.; ExlService Holdings, Inc.; Fair Isaac Corporation; SAS Institute Inc.; HCL Technologies Limited; Wipro Limited; Codoxo; Cognizant Technology Solutions Corporation; Gainwell Technologies LLC; Shift Technology; LexisNexis Risk Solutions; Thomson Reuters Corporation; Qlarant Quality Solutions, Inc.; Northrop Grumman Corporation; Healthcare Fraud Shield, Inc.; Zelis; Claritev Corporation |

Frequently Asked Questions
Key players include Optum, Cotiviti, Conduent, CGI, ExlService, FICO, SAS, HCL Technologies, Wipro, Codoxo, Cognizant, Gainwell, Shift Technology, LexisNexis Risk Solutions and Thomson Reuters.
Key opportunities include generative AI tools that detect manipulated documentation, prepayment fraud prevention, managed services, and new public insurance programs in Asia Pacific, the Middle East and Latin America.
The major growth factor is the rising volume and complexity of claims, combined with regulatory pressure to reduce improper payments and the availability of machine learning and cloud analytics.
By Component, the Software segment dominated the market in 2025, supported by payer demand for platforms that score claims, detect anomalies and manage investigations at scale.
North America dominated the market with a share of 43.10% in 2025, driven by the scale of public and private insurance spending and active enforcement against improper payments.
