
Healthcare Supply Chain Management Market Report Scope & Overview:
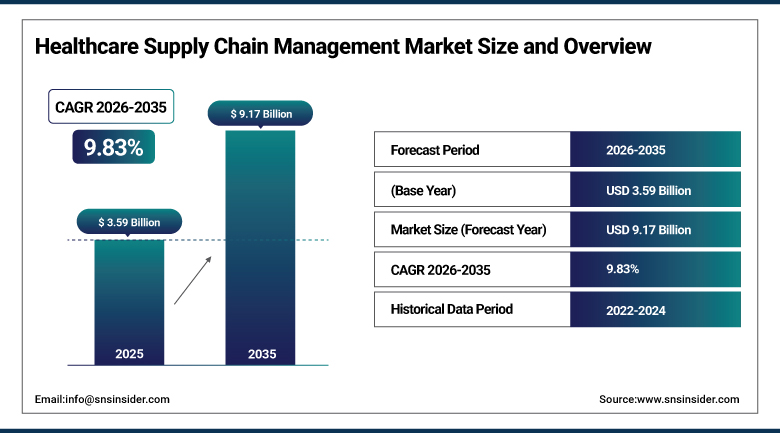
The Healthcare Supply Chain Management Market was valued at USD 3.59 Billion in 2025 and is expected to reach USD 9.17 Billion by 2035, growing at a CAGR of 9.83% from 2026-2035.
The Healthcare Supply Chain Management Market is expanding as hospitals and manufacturers digitize how they buy, store and deliver medical products. Persistent drug and device shortages have raised the priority of supply visibility. Cloud platforms now connect purchasing, inventory and logistics data across health systems. Radio frequency identification and barcode tracking reduce stock losses and expired items. Artificial intelligence supports demand forecasting and supplier risk scoring. Group purchasing organizations and vendors are adding analytics to guide contract choices. Integration cost and data security risk still slow adoption in smaller facilities. Tariffs and trade rules also add pressure on sourcing decisions. The market is expected to grow as providers seek resilience and lower supply cost.
⮞For instance, in the second quarter of 2026, the American Society of Health-System Pharmacists reported 227 active drug shortages in the United States, the third straight quarterly increase. The persistence of shortages keeps supply visibility high on hospital agendas.
To Get more information Healthcare Supply Chain Management Market - Request Free Sample Report
Healthcare Supply Chain Management Market Trends
-
Migration of procurement and inventory tools from on-premise systems to cloud platforms
-
Use of artificial intelligence for demand forecasting, substitution and supplier risk scoring
-
Expansion of RFID, barcode and sensor tracking for supplies and implants
-
Growth of digital control towers that connect hospitals, distributors and manufacturers
-
Greater focus on supply resilience after drug shortages and tariff changes
U.S. Healthcare Supply Chain Management Market Outlook
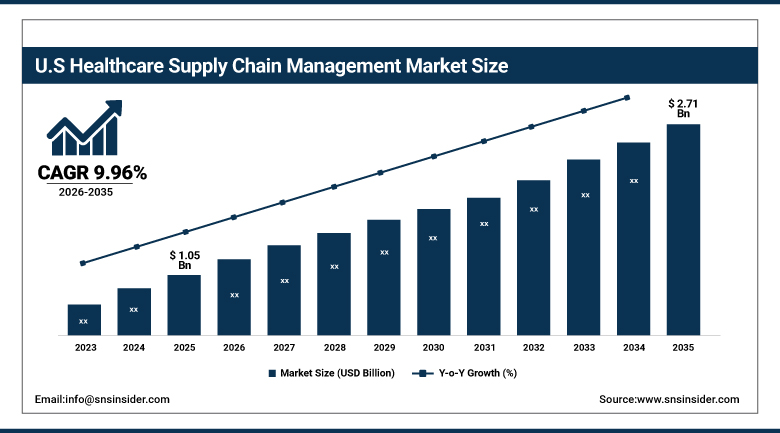
The U.S. Healthcare Supply Chain Management Market was valued at USD 1.05 Billion in 2025 and is expected to reach USD 2.71 Billion by 2035, growing at a CAGR of 9.96% from 2026-2035.
The U.S. Healthcare Supply Chain Management Market is the largest national market and is shaped by large health systems and powerful purchasing organizations. Hospitals face labor costs, supply price increases and recurring drug shortages. Many systems are replacing manual counting with automated inventory tools. Group purchasing organizations manage large contract volumes and offer analytics to members. Federal tariff actions and trade reviews add uncertainty to product sourcing. Cybersecurity rules affect software selection. Integration with electronic health records remains a key buying factor. Demand is therefore expected to rise as providers pursue cost savings and supply resilience. Large integrated delivery networks are also consolidating suppliers and vendors to simplify operations. This trend favors platforms that connect purchasing, inventory and finance data.
⮞In January 2026, Vizient said its contract portfolio represents USD 156 billion in annual purchasing volume. The scale shows the size of the purchasing activity that supply chain software and services support in the United States.
Healthcare Supply Chain Management Market Segment Analysis
-
By Component, the Software segment dominated the Healthcare Supply Chain Management Market with approximately 57.64% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 10.66%.
-
By Deployment, the Cloud-Based segment dominated the Healthcare Supply Chain Management Market with approximately 54.43% share in 2025, and is also the fastest growing with a CAGR of approximately 10.65%.
-
By Function, the Inventory Management segment dominated the Healthcare Supply Chain Management Market with approximately 30.05% share in 2025, while the Analytics segment is the fastest growing with a CAGR of approximately 11.97%.
-
By End User, the Healthcare Providers segment dominated the Healthcare Supply Chain Management Market with approximately 51.38% share in 2025, while the Pharmaceutical and Biotechnology Companies segment is the fastest growing with a CAGR of approximately 11.39%.
By Component, Software Dominates the Healthcare Supply Chain Management Market and Services Grows Fastest
Software leads the market because it provides the core tools for purchasing, inventory control, order management and spend analysis. Hospitals buy suites that connect to electronic health records and finance systems, and these links reduce manual entry and errors. Subscription models spread cost over several years, which suits budget-constrained providers. Vendors also add modules for contract compliance, product substitution and recall management, so existing customers expand spending over time. Strong demand for visibility across many suppliers keeps software at the center of purchasing plans. Hospitals value these tools because they replace spreadsheets and phone calls with shared data, which reduces errors in ordering, receiving and billing across facilities.
Services are growing faster as providers seek help with implementation, data cleanup, integration and managed operations. Many health systems lack the staff to run procurement analytics or to maintain item master data, and they turn to vendors and consultants. Outsourced supply chain operations, including vendor-managed inventory and logistics, are expanding in hospitals under cost pressure. Training and change management services also support adoption of new tools. As platforms become more complex, service contracts are expected to represent a larger share of vendor revenue. Outsourced implementation, analytics support and managed procurement are growing as health systems struggle to hire specialists, and vendors bundle these services with long-term software contracts.
⮞In March 2026, Tecsys reported software as a service annual recurring revenue of USD 83.30 million at January 31, 2026. The figure shows the growth of subscription software among healthcare supply chain vendors.
By Deployment, Cloud-Based Dominates the Healthcare Supply Chain Management Market and Grows Fastest
Cloud-based platforms lead because they remove the need for hospitals to host and maintain servers and allow faster rollout across many sites. Health systems that have merged or acquired facilities can place all locations on a common platform and view spend in one place. Vendors release updates continuously, which keeps analytics and compliance features current. Security certifications and data residency options have eased earlier concerns about storing supply data off site. Subscription pricing also lowers upfront cost and makes budgeting more predictable for providers. Subscription pricing lowers upfront cost, and vendors push updates without downtime, which helps health systems adopt new features faster than they could with older installed software.
Cloud delivery is also the fastest growing model because it supports artificial intelligence and network features that on-premise tools cannot match. Forecasting engines need large data sets from many sources, and cloud systems can connect suppliers, distributors and hospitals in near real time. Control tower tools that show shortages and delivery status depend on shared data. Smaller hospitals and ambulatory networks, which could not afford large licensed systems, are adopting cloud tools at a quick pace as vendors introduce modular offers. This model reflects a wider shift in healthcare information technology toward hosted platforms, as providers prefer to move maintenance and security work to vendors.
⮞In September 2025, Oracle announced new cloud capabilities to help healthcare organizations streamline supply chain operations at its Health and Life Sciences Summit. The announcement shows large enterprise vendors extending cloud supply chain tools to providers.
By Function, Inventory Management Dominates the Healthcare Supply Chain Management Market and Analytics Grows Fastest
Inventory management leads functional demand because hospitals hold large volumes of supplies, implants and medications that must be tracked by lot, expiry and location. Automated cabinets, barcode scanning and radio frequency identification reduce stockouts and write-offs. Clinicians spend less time searching for items, which supports patient care. Inventory data also supports charge capture and recall response. Hospitals see quick returns from reducing excess stock, so inventory tools are often the first purchase in a supply chain program. Accurate counts reduce write-offs for expired products and free nurses from manual tracking, which improves time spent on patient care and lowers carrying cost across storerooms.
Analytics is growing fastest as providers and manufacturers use data to guide contracts, forecast demand and spot risk. Spend analysis highlights price variation across facilities and identifies savings from standardizing products. Predictive models estimate shortages and suggest substitutes before stocks run out. Dashboards give executives a view of supplier performance and delivery reliability. Artificial intelligence is increasing the value of these tools, and vendors are bundling analytics into core platforms, which broadens use among mid-sized health systems. Forecasting, spend visibility and supplier risk scoring are the main use cases, and buyers expect them to be available inside the same platform they use for ordering.
⮞In March 2026, Zebra Technologies introduced the DS82-HC healthcare scanner with four days of battery life at HIMSS26. The device shows how hardware makers are supporting tracking and inventory workflows in clinical settings.
By End User, Healthcare Providers Dominates the Healthcare Supply Chain Management Market and Pharmaceutical and Biotechnology Companies Grows Fastest
Healthcare providers account for the largest share because hospitals and health systems manage the most complex purchasing and inventory operations. They buy thousands of products from many suppliers, and they face pressure to reduce supply expense. Large systems operate central distribution centers and use software to coordinate deliveries to hospitals and clinics. Surgical supplies, implants and pharmaceuticals each need specialized tracking. Providers also use supply data to support quality programs and regulatory reporting, which sustains investment. Their purchasing decisions often cover several hospitals at once, so a single contract can add significant volume for software and automation vendors serving the group.
Pharmaceutical and biotechnology companies are growing fastest as they invest in serialization, cold chain monitoring and end-to-end visibility. Regulations such as the Drug Supply Chain Security Act require tracking of prescription products through the supply chain. Biologics and cell therapies need temperature controlled logistics and chain of identity records. Manufacturers also use supply chain platforms to manage contract manufacturers and distributors across regions. Tariffs and shortages are raising the importance of supplier risk tools for this group. Manufacturers also need better visibility into distribution and returns, and regulations on serialization and verification increase the data they must collect, share and store.
⮞In November 2025, Gartner ranked AdventHealth first for a second year in its 17th Healthcare Supply Chain Top 25. The ranking shows the focus that large provider systems place on supply chain performance.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
69.97 |
|
Europe |
United Kingdom |
35.21 |
|
Asia Pacific |
China |
23.53 |
|
Latin America |
Brazil |
47.38 |
|
Middle East & Africa |
Saudi Arabia |
31.84 |
North America Healthcare Supply Chain Management Market Insights
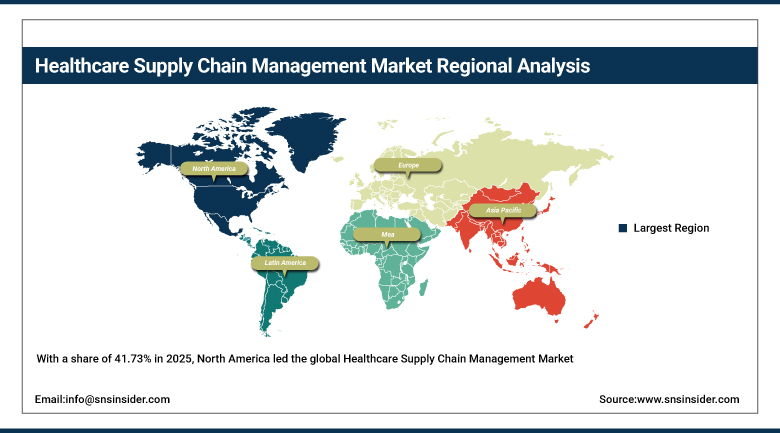
With a share of 41.73% in 2025, North America led the global Healthcare Supply Chain Management Market. The United States contributes most regional demand through large integrated delivery networks, powerful group purchasing organizations and high spending on healthcare technology. Canada adds provincial initiatives to centralize procurement and improve inventory control, while Mexico is consolidating public purchasing of medicines and devices. Leading vendors such as Oracle, GHX, Tecsys, Infor and Omnicell compete with distributors that offer their own digital tools. Recurring drug shortages and tariff actions encourage providers to invest in visibility and supplier diversification. Strong demand for integrated software across hospital networks also keeps technology vendors investing in local support and implementation teams.
Hospitals are under strong financial pressure from labor costs and supply prices, which makes savings from standardization and automation a priority. Cybersecurity expectations influence vendor selection, because supply systems link to clinical and financial data. Consolidation among providers and purchasing organizations is creating larger buyers with greater bargaining power. Cold chain logistics for biologics and specialty drugs is growing, and logistics firms are acquiring healthcare focused carriers. Mergers among software providers also continue as vendors seek broader suites for health systems. Rising use of automated dispensing and tracking systems in operating rooms and pharmacies supports further adoption of connected supply platforms.
⮞In November 2025, UPS completed its acquisition of Andlauer Healthcare Group, a healthcare logistics provider, in a transaction valued at about USD 1.60 billion. The deal shows the strategic value of specialized healthcare logistics in North America.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Healthcare Supply Chain Management Market Insights
Europe is the second largest region, led by the United Kingdom, Germany, France, Italy and Spain. National health systems purchase through central bodies, and tenders favor suppliers with strong compliance records. The United Kingdom has invested in inventory systems and supply chain standards through NHS Supply Chain, while Germany has a large hospital sector that is modernizing its digital infrastructure. European Union rules on medical device identification and falsified medicines require tracking from manufacturer to patient. Regional shortages of critical medicines have increased policy focus on supply resilience. Pan-European procurement rules and the Falsified Medicines Directive also encourage hospitals and manufacturers to invest in tracking and data sharing tools.
Vendors must adapt to differing national procurement rules and data protection requirements. Hospitals in the Nordic countries and the Netherlands are early adopters of automation and analytics. Southern and Eastern European countries are upgrading systems with the support of recovery funds, which opens new demand for cloud tools. Sustainability reporting is also entering procurement decisions, as hospitals ask suppliers for data on emissions and packaging. Cross-border groups and pharmaceutical manufacturers prefer platforms that serve several countries under one contract. Public health systems in several countries are consolidating purchasing, which creates scale for platforms that can manage tenders, contracts and inventory in one place.
⮞In December 2025, NHS Supply Chain reported that its Inventory Management System programme was live at 19 trusts across 83 locations. The rollout shows continued public investment in inventory visibility in Europe.
Asia Pacific Healthcare Supply Chain Management Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 11.43% during 2026-2035. China, India, Japan, Australia and South Korea lead regional demand. Hospital construction, rising insurance coverage and expansion of private hospital chains are increasing the number of facilities that need supply systems. China is building digital hospital platforms and domestic software suppliers are expanding. India is formalizing procurement practices, while Japan focuses on automation to offset labor shortages. Australia has mature distribution networks and is investing in cold chain capacity. Growing hospital construction and rising insurance coverage add steady demand for systems that manage supplies for new facilities and expanding networks.
Pharmaceutical manufacturing in India and China makes the region a major source of generic drugs and devices, so manufacturer demand for traceability tools is high. Governments are promoting digital health, track-and-trace rules and local manufacturing. Regional distributors are partnering with global software vendors to offer cloud services. Fragmented logistics and uneven infrastructure raise the value of visibility tools, particularly for temperature sensitive products. Professional training programs are also being introduced to build skills in healthcare supply chain management. Large private hospital chains are the earliest adopters, and many are working with global vendors to standardize purchasing and storeroom processes across sites.
⮞In April 2026, the Consortium of Accredited Healthcare Organizations in India launched a healthcare supply chain certification program with ISM-India. The program shows rising professionalization of supply chain roles in the region.
MEA & Latin America Healthcare Supply Chain Management Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Public health systems purchase in large volumes and are moving toward consolidated procurement and electronic tracking. Private hospital groups in Brazil and Mexico adopt cloud inventory and procurement tools to reduce waste. Currency changes and import dependence affect pricing, and regional distributors support vendors with local service. Regulatory agencies are strengthening track-and-trace rules for medicines, which supports demand for serialization and monitoring tools. Governments are investing in hospital infrastructure and national procurement agencies, which creates demand for transparent purchasing and inventory systems.
In the Middle East and Africa, Saudi Arabia and the United Arab Emirates lead demand through national health transformation programs and centralized purchasing entities. Large hospital projects specify digital supply systems from the start. South Africa has a developed private hospital sector, while many African countries rely on donor-funded supply programs. Start-ups in the region are building digital marketplaces for medical products, which connect suppliers with hospitals and pharmacies and improve price transparency. Challenges remain, including limited technical skills, uneven connectivity and fragmented distribution, but pilot programs and cloud tools are helping close these gaps.
⮞In February 2025, Saudi Arabia's NUPCO secured about USD 667 million in supply chain financing agreements to support its supply operations for hospitals and clinics. The agreements show the scale of centralized health procurement in the Gulf.
Market Dynamics
Growth Drivers: Supply Disruptions and Demand for Traceability
Supply disruptions are the strongest driver of market growth. Repeated drug shortages, tariff changes and logistics delays have shown hospitals the cost of limited visibility. Providers now invest in tools that show stock levels across facilities, identify substitutes and alert buyers to supplier delays. Executives treat supply resilience as a patient safety issue and not only as a cost matter. This change in priority moves budgets toward software, analytics and services that were previously seen as optional. Shortages of drugs and devices also force hospitals to hold higher safety stock, which increases the need for tools that show inventory levels across sites in real time.
Regulatory traceability requirements add further demand. Drug supply chain security laws, medical device identification rules and recall obligations require accurate records of product movement. Manufacturers, distributors and hospitals therefore adopt platforms that capture lot, serial number and expiry data. Interoperable networks make it easier to share this information among partners. Rising procedure volumes from aging populations also increase the quantity of supplies handled, which supports investment in automation and tracking technology. Regulators in many countries expect product tracing and recall readiness, so manufacturers and providers are investing in systems that connect their records through the full distribution chain.
⮞In May 2026, TraceLink reported a network of more than 315,000 authenticated enterprises and trading partners. The network size shows the scale of digital traceability systems in pharmaceutical supply chains.
Restraints: Tariffs, Integration Cost and Cybersecurity Risk
Tariffs and trade measures create uncertainty for sourcing and pricing. Medical supplies and pharmaceuticals move through global networks, and new duties or investigations can change supplier choices and costs overnight. Hospitals with fixed budgets may delay software investment while they manage rising supply prices. Vendors that rely on imported hardware, such as scanners and tags, also face higher costs. Policy changes may eventually support domestic production, yet the transition adds near-term risk. Cost is the second concern, as many hospitals operate with thin margins and must weigh software spending against clinical priorities and staffing needs.
Integration cost and cybersecurity risk are further restraints. Connecting supply systems to electronic health records, finance and supplier networks requires technical work, and smaller facilities lack skilled staff. Data breaches at healthcare vendors can expose sensitive information and lead to regulatory penalties. Buyers therefore run lengthy security reviews, which slow sales cycles. Resistance to change among clinicians and purchasing staff can also reduce the value of new systems if training is limited. Legacy systems create further friction because older records are difficult to clean, map and migrate, and smaller hospitals often lack the skills to manage large integration projects.
⮞In April 2026, the White House announced a 100% tariff on patented pharmaceutical products, with a 15% rate for the European Union, Japan, South Korea and Switzerland. The measure shows the trade policy pressure affecting healthcare sourcing.
Opportunities: Artificial Intelligence and Emerging Market Digitization
Artificial intelligence offers a major opportunity because supply chains generate large data sets that are poorly used today. Models can forecast demand by procedure, recommend order quantities and predict supplier failures. Vendors are launching AI agents that automate routine purchasing tasks, such as substitution and order correction. Start-ups are attracting funding to build specialized tools for hospitals, and large vendors are adding similar features to existing suites. Providers that adopt these tools early can reduce waste and avoid disruptions. Predictive models can flag likely shortages, suggest alternate suppliers and reduce emergency purchases, which gives providers clear savings and protects patient care.
Emerging markets present a second opportunity. Governments in Asia Pacific, the Middle East and Latin America are building hospitals, creating central purchasing bodies and introducing track-and-trace rules. These programs favor cloud platforms and marketplaces that can be deployed quickly. Partnerships with regional distributors and local integrators allow global vendors to enter markets with lower upfront investment. Demand for professional training and certification also creates openings for service providers that offer education and consulting. Vendors that offer low-cost cloud tools and local language support can reach clinics and mid-sized hospitals that have not adopted formal supply systems before.
⮞In May 2025, Clarium raised a USD 27.00 million Series A round led by Northzone to build artificial intelligence tools for hospital supply chains. The financing shows investor interest in AI-based supply chain products.
Recent Developments:
-
2026: Medline launched Mpower, a digital control tower built with Microsoft. Early users at ten U.S. health systems reported efficiency gains of more than 50% in order substitution workflows.
-
2025: Patient Square Capital completed its USD 2.60 billion acquisition of Premier, Inc. at USD 28.25 per share. The take-private transaction gives the group purchasing and supply chain solutions provider private ownership.
-
2026: GHX launched an orchestration platform that helps supply chain leaders sense, decide and act faster. The company said more than 600 provider organizations already use its capabilities.
-
2025: McKesson announced its intent to separate its Medical-Surgical Solutions business into an independent company. The plan is intended to sharpen focus on each business and its customers in the supply chain.
Healthcare Supply Chain Management Market Key Players are
-
Oracle Corporation
-
McKesson Corporation
-
Cardinal Health, Inc.
-
Global Healthcare Exchange (GHX)
-
Premier, Inc.
-
Vizient, Inc.
-
Tecsys Inc.
-
Infor, Inc.
-
Medline Industries, LP
-
Omnicell, Inc.
-
Zebra Technologies Corporation
-
TraceLink, Inc.
-
Clarium
-
Aumet
Healthcare Supply Chain Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.59 Billion |
| Market Size by 2035 | USD 9.17 Billion |
| CAGR | CAGR of 9.83% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services, and Hardware) • By Deployment (Cloud-Based and On-Premise) • By Function (Inventory Management, Procurement and Sourcing, Order Management, Warehouse and Transportation Management, Analytics, and Other Functions) • By End User (Healthcare Providers, Pharmaceutical and Biotechnology Companies, Medical Device Manufacturers, Group Purchasing Organizations, and Other End Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Oracle Corporation, McKesson Corporation, Cardinal Health, Inc., Global Healthcare Exchange (GHX), Premier, Inc., Vizient, Inc., Tecsys Inc., Infor, Inc., Medline Industries, LP, Omnicell, Inc., Zebra Technologies Corporation, TraceLink, Inc., Clarium, Aumet |

Frequently Asked Questions
Key players include Oracle, McKesson, Cardinal Health, GHX, Premier, Vizient, Tecsys, Infor, Medline, Omnicell, Zebra Technologies, TraceLink, Clarium and Aumet.
Key opportunities include artificial intelligence for forecasting and purchasing automation, cloud control towers, traceability for pharmaceuticals and digitization of procurement in emerging markets.
Supply disruptions and demand for visibility are the main growth factors, supported by drug shortages, tariff changes and regulatory traceability requirements.
By Component, the Software segment dominated the market in 2025 with an estimated 57.64% share, supported by demand for purchasing, inventory and analytics tools in hospitals.
North America dominated the market with a share of 41.73% in 2025, driven by large health systems, powerful purchasing organizations and early adoption of cloud and analytics tools.
