
Hydrocarbon Accounting Solution Market Report Scope & Overview:
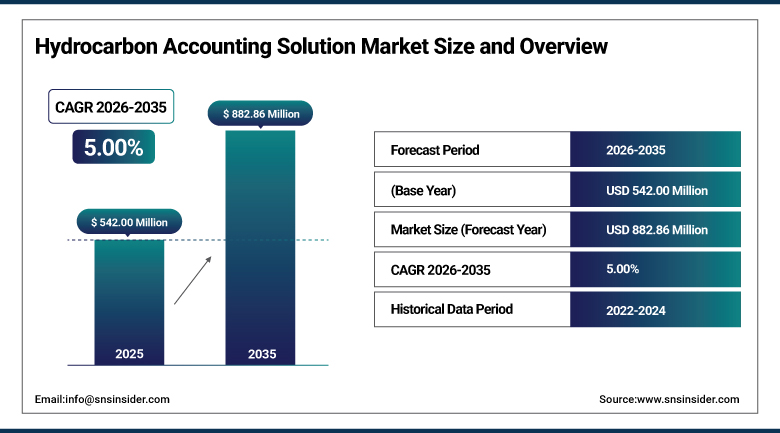
The Hydrocarbon Accounting Solution Market was valued at USD 542.00 Million in 2025 and is expected to reach USD 882.86 Million by 2035, growing at a CAGR of 5.00% from 2026-2035.
The Hydrocarbon Accounting Solution Market covers software and services that measure, allocate and reconcile oil, gas and water volumes from the wellhead through pipelines, terminals and refineries, and turn them into financial records for royalties, joint ventures, taxes and partner reporting. Operators use these systems to trace hydrocarbons through custody transfers, resolve measurement differences and meet regulatory and audit requirements. Demand is stable because accurate volume accounting underpins revenue, and it is growing as companies add emissions tracking, cloud deployment and AI-based validation. Vendors include enterprise software groups, energy specialists and oilfield services firms, and large operators often run these tools for decades.
⮞AI is reaching energy back offices. On April 8, 2026, Enverus announced Enverus ONE, a governed AI platform that serves as an execution layer for energy companies, live from April 7. It combines Enverus's proprietary data, used by more than 8,000 customers in 50 countries, with its Astra energy model and generative AI, and ships with pre-built Flows such as AFE Evaluation and Current Production Valuation. Customer data sits in isolated private tenancies with audit trails and SOC 2 Type II certification, and the roadmap adds Flows for finance and operations through 2026.
To Get more information Hydrocarbon Accounting Solution Market - Request Free Sample Report
Hydrocarbon Accounting Solution Market Trends
-
Migration from on-premises accounting systems to cloud-based platforms
-
AI-based validation of allocation and measurement data
-
Integration of emissions and methane reporting with production accounting
-
Digital twins and real-time data feeds replacing monthly manual reconciliation
-
Consolidation of upstream software portfolios among large vendors
-
Governed AI assistants that work with private operator data
U.S. Hydrocarbon Accounting Solution Market Outlook
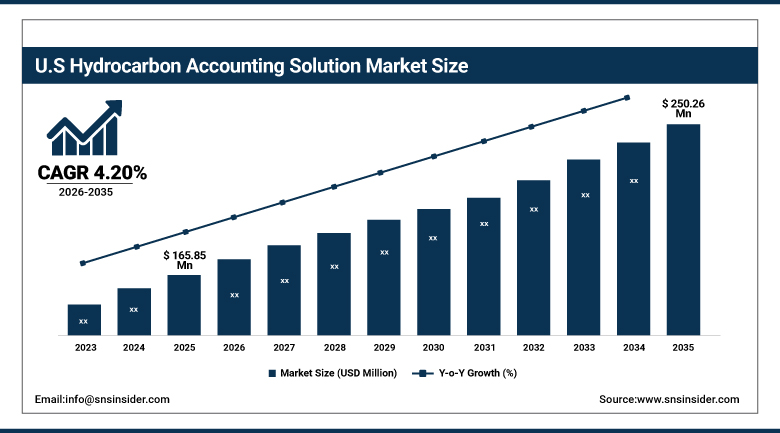
The U.S. Hydrocarbon Accounting Solution Market was valued at USD 165.85 Million in 2025 and is expected to reach USD 250.26 Million by 2035, growing at a CAGR of 4.20% from 2026-2035.
The U.S. Hydrocarbon Accounting Solution Market is the largest national market, driven by thousands of independent operators, mineral and royalty owners, midstream gatherers and service companies across the Permian, Eagle Ford, Bakken, Appalachia and the Gulf. Complex joint ventures, royalty obligations and state reporting requirements create steady demand for allocation and revenue systems. Vendors including Quorum, Enverus, P2 Energy Solutions, SAP and SLB compete, while many small operators still rely on spreadsheets or basic accounting tools. Methane and emissions rules are adding reporting needs, and consolidation among producers shapes buying patterns.
⮞Oilfield services groups are buying software. On April 29, 2026, SLB announced it would acquire S&P Global Energy's geoscience and petroleum engineering software business, widely used by U.S. land operators. SLB plans to integrate the portfolio into its digital platforms and add agentic AI using its Lumi platform and Tela framework with S&P Global Energy's upstream data, and the deal is expected to close in the second half of 2026 or early 2027. The Houston-based company did not disclose the price.
Hydrocarbon Accounting Solution Market Segment Analysis
-
By Component, the Software segment dominated the Hydrocarbon Accounting Solution Market with approximately 71.00% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 6.40%.
-
By Deployment Mode, the On-Premises segment dominated the Hydrocarbon Accounting Solution Market with approximately 63.00% share in 2025, while the Cloud-Based segment is the fastest growing with a CAGR of approximately 8.40%.
-
By Function, the Production Allocation and Reconciliation segment dominated the Hydrocarbon Accounting Solution Market with approximately 34.00% share in 2025, while the Emissions and ESG Reporting segment is the fastest growing with a CAGR of approximately 9.50%.
-
By Application, the Oil segment dominated the Hydrocarbon Accounting Solution Market with approximately 52.00% share in 2025, while the Natural Gas segment is the fastest growing with a CAGR of approximately 6.40%.
-
By End-User, the Upstream segment dominated the Hydrocarbon Accounting Solution Market with approximately 48.00% share in 2025, while the Midstream segment is the fastest growing with a CAGR of approximately 6.00%.
By Component, Software Dominates the Hydrocarbon Accounting Solution Market and Services Grows Fastest
Software leads because hydrocarbon accounting depends on specialized platforms that hold well, facility and contract hierarchies, run allocation logic and post volumes into financial systems. Products such as Quorum's Energy Components, SAP's oil and gas modules and P2 Energy Solutions' tools are long-lived and deeply embedded, so license and maintenance revenue is stable. Operators rarely switch because history and audit trails sit inside the system, which supports software's roughly 70% share.
Services are growing fastest as companies need consulting, implementation, data migration and managed support to modernize aging systems. Cloud migrations, new emissions modules and integration with ERP and measurement systems require specialist skills, and firms such as Infosys, Wipro, CGI and Accenture sell large projects. Smaller operators outsource production accounting entirely, and the shortage of experienced accountants who understand allocation pushes more work to service providers.
⮞In December 2025, Enverus introduced Enverus AI, a secure, energy-specific artificial intelligence system embedded in industry workflows. The platform applies energy-sector data and analytics to support faster decision-making, creating opportunities to automate software-intensive upstream business processes.
By Deployment Mode, On-Premises Dominates the Hydrocarbon Accounting Solution Market and Cloud-Based Grows Fastest
On-premises deployment leads because many large operators and national oil companies run mature installations that handle sensitive volume and revenue data and are customized for local rules. Replacing them is costly and risky, as errors could affect royalty payments and partner billing. Security policies, connectivity limits at remote sites and long contract cycles keep a majority of the installed base on premises.
Cloud-based solutions are growing fastest as vendors move products to software-as-a-service and operators seek lower infrastructure costs, faster updates and easier partner access. Cloud allows real-time data from sensors and measurement systems and supports AI features that need scalable computing. Smaller operators adopt cloud first, while larger companies move in phases. Governed AI platforms such as Enverus ONE, with private tenancy and audit trails, show how vendors address data concerns.
⮞In November 2025, ADNOC announced the initial deployment of its AI-powered Production System Optimization platform across eight fields, integrating SLB's Lumi platform with Cognite Data Fusion to analyze real-time operational data and optimize production across wells and processing facilities.
By Function, Production Allocation and Reconciliation Dominates the Hydrocarbon Accounting Solution Market and Emissions and ESG Reporting Grows Fastest
Production allocation and reconciliation leads because it is the core of hydrocarbon accounting, assigning measured volumes back to wells, leases and partners and reconciling differences between field measurement, pipeline receipts and sales. Accurate allocation determines royalties, taxes and revenue shares, so every producer needs it. The function requires configuration for complex networks, shared facilities and custody transfer points, which keeps spending concentrated here.
Emissions and ESG reporting is growing fastest as regulators and investors demand measured greenhouse gas and methane data tied to production volumes. Vendors such as Quorum have added Scope 1 and Scope 2 emissions calculations and Scope 3 management to their accounting products. Because emissions inventories draw on the same volume records, operators prefer integrated modules over separate tools. Stricter methane rules and corporate climate targets support rapid growth from a small base.
⮞In December 2025, Brazil's National Agency of Petroleum, Natural Gas and Biofuels approved a review of Resolution ANP No. 889/2022, initiating a public consultation process to update requirements governing the acquisition, processing, and access of technical data across regulated energy activities.
By Application, Oil Dominates the Hydrocarbon Accounting Solution Market and Natural Gas Grows Fastest
Oil leads because crude production involves the most wells, custody transfers and royalty arrangements worldwide, and liquids require careful allocation among blends, terminals and tankers. Producers in the United States, the Middle East, Russia, Brazil and Norway run large oil accounting systems, and price volatility raises the value of accurate volumes. Oil's long history in the sector explains its roughly half share of spending.
Natural gas is growing fastest because LNG expansion, pipeline growth and gas processing add complex allocation tasks involving composition, heating value and multiple measurement points. New LNG terminals need accounting systems that track inventory, cargoes and nominations, and Energy Components has been used to bring terminals online in months. Gas also faces tighter methane scrutiny, which raises demand for integrated measurement and emissions accounting.
⮞In December 2025, Saudi Aramco commenced operations at its Tanajib Gas Plant, designed to process associated raw gas from the offshore Marjan and Zuluf fields. The facility's digital integration supports operational efficiency and expands gas-processing capabilities, increasing the importance of accurate gas-volume accounting.
By End-User, Upstream Dominates the Hydrocarbon Accounting Solution Market and Midstream Grows Fastest
Upstream companies lead because exploration and production operators manage the largest number of assets, partners and royalty owners, and their revenue depends on allocating produced volumes accurately. Joint ventures, production sharing contracts and mineral interests multiply accounting complexity. Large operators and national oil companies buy enterprise systems, and independents buy specialized tools, which together account for almost half of spending.
Midstream companies are growing fastest as pipeline, gathering, processing and terminal networks expand to move shale output and LNG exports. They need to allocate volumes across shippers and facilities, reconcile imbalances and bill fees, and growing pipeline capacity increases transaction volumes. Regulators also require accurate reporting of losses and emissions. Providers are extending upstream tools into midstream workflows and offering integrated custody transfer and invoicing modules.
⮞In November 2025, Emerson introduced its Fisher ARMOR digital monitoring solution for natural gas utility grids, combining measurement and communications capabilities for remote infrastructure monitoring, improved data collection, operational reliability, and regulatory compliance across gas distribution networks.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00 |
|
Asia Pacific |
China |
35.00 |
|
Europe |
Norway |
22.50 |
|
Middle East & Africa |
Saudi Arabia |
38.00 |
|
Latin America |
Brazil |
48.00 |
North America Hydrocarbon Accounting Solution Market Insights
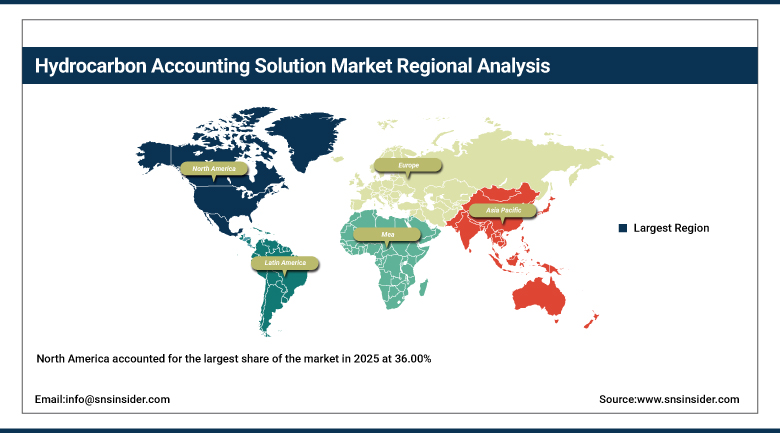
North America accounted for the largest share of the market in 2025 at 36.00%. The United States holds most regional value through shale operators, midstream networks and vendors such as Quorum, Enverus, P2 Energy Solutions and SLB. Canada adds oil sands and gas producers with complex royalty regimes.
Strict reporting rules, many joint ventures and a large base of independent operators sustain demand. AI and consolidation are changing the vendor landscape, as shown by Enverus ONE in April 2026 and SLB's acquisition of S&P Global Energy's upstream software. Growth is slower than in Asia Pacific because the installed base is mature, but cloud migration and emissions reporting add upgrades.
⮞In February 2026, the U.S. Energy Information Administration reported that pipeline projects completed during 2025 added approximately 6.3 billion cubic feet per day of natural gas transportation capacity, with 85% directed toward the South Central region, strengthening the infrastructure supporting gas flows and LNG demand.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Hydrocarbon Accounting Solution Market Insights
Asia Pacific is the fastest-growing region, advancing at a CAGR of 6.20% during 2026-2035. China and India lead growth, with national oil companies expanding production, pipelines and LNG import terminals, and Japan, South Korea, Australia and Southeast Asia contribute through LNG and refining.
Rising energy consumption and tighter compliance rules drive investment in measurement and accounting systems. Indian and Chinese IT services firms such as Infosys and Wipro deliver implementations globally and locally, and local operators are modernizing legacy systems. Complex ownership structures and varied standards slow some projects, but infrastructure investment supports steady growth.
⮞In February 2025, AVEVA and HPCL-Mittal Energy Limited signed a memorandum of understanding to advance digital transformation at India's refining and petrochemical facilities, with plans involving cloud-based industrial software, digital twins, advanced analytics, and AI-driven technologies.
Europe Hydrocarbon Accounting Solution Market Insights
Europe held the significant share of the Hydrocarbon Accounting Solution Market in 2025. Norway, the United Kingdom, the Netherlands and Germany lead through North Sea production, LNG import terminals, refining and trading hubs. TietoEVRY's Energy Components, now part of Quorum, originated in Norway and remains widely used.
Environmental policy and emissions trading drive demand for integrated volume and emissions accounting, and operators in mature basins seek efficiency through digitalization. Declining North Sea output and the energy transition moderate long-term growth, but LNG terminals and decommissioning accounting keep spending active.
⮞In October 2025, Norway's Ministry of Energy outlined continued modernization of the Norwegian Offshore Directorate's petroleum-data infrastructure, including replacement of outdated IT systems and development of automated processes for data collection, processing, and quality assurance across the continental shelf.
MEA & Latin America Hydrocarbon Accounting Solution Market Insights
The Middle East and is growing at a steady growth rate during the forecast period. Saudi Arabia, the United Arab Emirates, Qatar, Kuwait and Iraq lead through national oil companies, large gas and LNG projects and refining expansion, while Nigeria, Angola and Egypt add demand. Many projects are executed by international vendors and integrators.
Latin America is experiencing the robust growth in the market. Brazil leads through deepwater pre-salt production, with Mexico, Argentina, Colombia and Guyana contributing. Policy changes, state company budgets and currency swings restrain spending, but new offshore developments and shale activity in Argentina support demand for modern accounting.
⮞In January 2025, Saudi Aramco's North Ghawar Oil Producing Complex joined the World Economic Forum's Global Lighthouse Network, recognizing its large-scale adoption of Fourth Industrial Revolution technologies to improve operational performance and environmental management across oil production activities.
Growth Drivers: Regulatory Compliance, Joint Venture Complexity and Emissions Reporting
Regulatory compliance is a primary driver. Governments require accurate production reporting for royalties, taxes and resource management, and auditors expect traceable allocation. Errors can cause penalties and disputes, so operators invest in systems that document how volumes were measured and allocated, and in controls that reduce manual spreadsheet work.
Joint venture complexity and emissions reporting add momentum. Production often involves several partners with different interests, and each needs accurate statements. At the same time, methane and greenhouse gas rules link emissions to production volumes, so vendors such as Quorum add Scope 1, 2 and 3 modules to accounting platforms. Integrated tools are attractive because they use a single source of volume data.
⮞In January 2026, Brazil's National Agency of Petroleum, Natural Gas and Biofuels updated its production-monitoring information, detailing how its Production Inspection System collects measurement-instrument data and validates operator-reported volumes in monthly production statements, supporting regulatory oversight and royalty calculations.
Restraints: Legacy System Lock-In, High Implementation Cost and Cyclical Energy Spending
Legacy system lock-in is a significant restraint. Many operators run customized systems built over decades, and replacing them risks disrupting royalty and partner billing. Data migration is complex, and users resist change, so projects can be delayed or limited to partial upgrades, which slows market growth to a mid-single-digit pace.
High implementation cost and cyclical spending add pressure. Large deployments require consulting, integration with measurement and ERP systems and training, and smaller producers may not justify the cost. When oil and gas prices fall, operators cut software budgets and postpone upgrades. Concern about energy transition also leads some investors to limit long-term upstream spending.
Opportunities: Governed AI, Cloud Migration and LNG and Midstream Expansion
Governed AI offers a major opportunity. Platforms such as Enverus ONE, launched in April 2026, and SLB's planned agentic AI built on S&P Global Energy's upstream data aim to automate manual tasks and check data quality. In hydrocarbon accounting, AI can flag allocation anomalies, match measurement records and speed month-end close, provided data stays secure and auditable.
Cloud migration and LNG and midstream expansion provide further opportunities. Moving aging on-premises systems to cloud subscriptions creates upgrade revenue for vendors and integrators, and new LNG terminals, pipelines and gas processing plants need accounting from the start. Providers with proven LNG, custody transfer and emissions modules can win new projects in the United States, Qatar, Australia and Africa.
⮞In September 2025, Emerson announced the availability of AspenTech Subsurface Intelligence, a cloud-native, AI-enabled environment using domain-specific agents and the OSDU Data Platform to automate subsurface workflows and improve collaboration across exploration and production teams, illustrating opportunities for connected energy-data applications.
Recent Developments:
-
2026: Quorum highlighted the transition to cloud-based Upstream On Demand Accounting, consolidating accounts payable, revenue, division orders, and joint-interest billing into integrated workflows.
-
2026: Accenture examined scaling AI across upstream energy operations, emphasizing integration into everyday workflows, governance, and operating models to convert analytics into measurable operational performance.
-
2026: Infosys participated in the SAP for Energy and Utilities Conference, highlighting its engagement in technology-led transformation involving AI, automation, data, and energy-sector modernization.
Hydrocarbon Accounting Solution Market Key Players are:
-
SAP SE
-
IFS AB (IFS Energy & Resources)
-
EnergySys Limited
-
Omnira Software
-
Pansoft Company Limited
-
Enertia Software
-
W Energy Software
-
Pandell
-
Peloton
-
PAS Master
-
Infosys Limited
-
CGI Inc.
-
Capgemini SE
-
SLB
-
Halliburton Company
-
Weatherford International plc
-
Enverus
-
Oracle Corporation
Hydrocarbon Accounting Solution Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 542.00 Million |
| Market Size by 2035 | USD 882.86 Million |
| CAGR | CAGR of 5.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services) • By Deployment Mode (On-Premises, Cloud-Based) • By Function (Production Allocation and Reconciliation, Royalty and Revenue Accounting, Joint Venture Accounting, Emissions and ESG Reporting, Others) • By Application (Oil, Natural Gas, Water) • By End-User (Upstream, Midstream, Downstream) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SAP SE, Quorum Software, IFS AB (IFS Energy & Resources), EnergySys Limited, Omnira Software, Pansoft Company Limited, Enertia Software, W Energy Software, PakEnergy, Pandell, Peloton, PAS Master, Infosys Limited, CGI Inc., Capgemini SE, SLB, Halliburton Company, Weatherford International plc, Enverus, Oracle Corporation |

Frequently Asked Questions
Key players include SAP, Quorum Software, Infosys, Wipro, SLB, Halliburton, and Pansoft, among others.
Key opportunities include governed AI for data validation and month-end close, cloud migration of aging on-premises systems, and new accounting needs from LNG terminals and midstream expansion.
The major growth factor is regulatory compliance and joint venture complexity, which require traceable allocation of volumes, supplemented by rising demand for emissions reporting tied to production data.
By Component, the Software segment dominated the market with approximately 71.00% share in 2025, owing to deeply embedded allocation and revenue accounting platforms with stable license and maintenance revenue.
North America dominated the market with a share of 36.00% in 2025, supported by shale operators, midstream networks and strict reporting requirements in the United States.
