
Immersive Content Creation Market Report Scope & Overview:
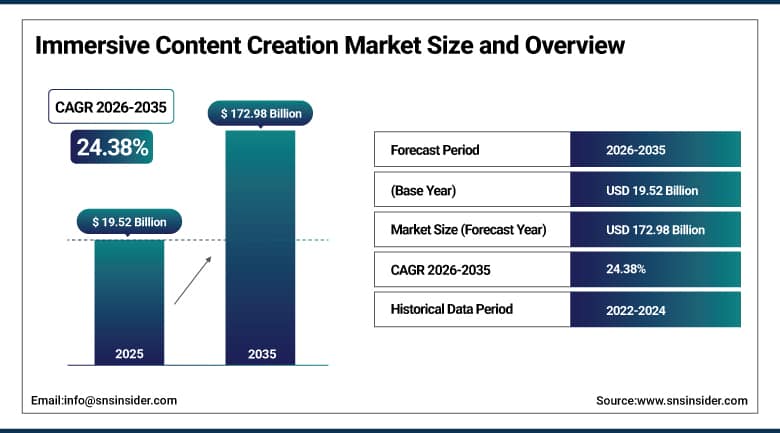
The Immersive Content Creation Market was valued at USD 19.52 Billion in 2025 and is estimated at USD 24.28 Billion in 2026. It is projected to reach USD 172.98 Billion by 2035, advancing at a CAGR of 24.38% from 2026 to 2035. Immersive content creation covers the hardware, software, and services used to build virtual, augmented, and mixed reality experiences, including capture cameras, game engines, three-dimensional design tools, and production services. Gaming demand, enterprise training, and generative design tools are widening the base of creators and buyers. Subscription tools are spreading quickly.
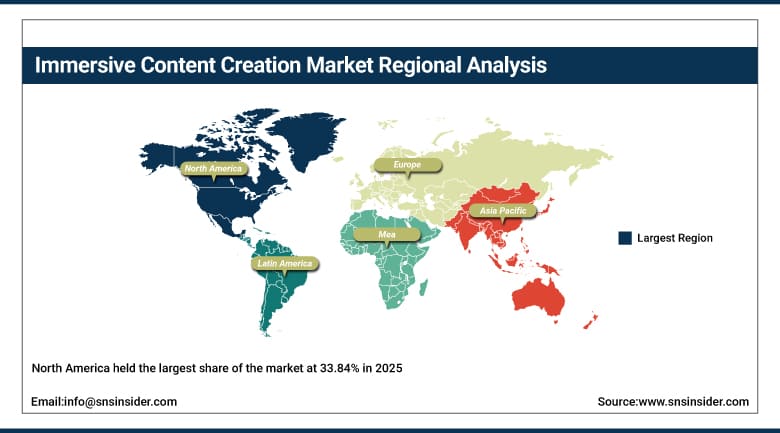
The North American region became the largest regional market, taking 33.84% share due to the presence of the game studios, technology platform, and various enterprise users in the region. The APAC region will come second and is projected to grow at the fastest rate owing to the increased usage of devices and mobile gaming along with government investment in China, Japan, South Korea, and India. Europe has been profiting from the presence of its media, automotive, and design industry, while Latin America and Middle East & Africa have been witnessing the installation of more studios and entertainment initiatives.
To Get More Information On Immersive Content Creation Market - Request Free Sample Report
Key Report Takeaways
- By component, hardware held a 39.84% share in 2025, while software is the fastest growing.
- By technology, virtual reality accounted for a 38.26% share in 2025, while augmented reality is the fastest growing.
- By end use, gaming represented a 32.14% share in 2025, while entertainment and media is the fastest growing.
- By content format, immersive video commanded a 34.86% share in 2025, while interactive games and three-dimensional environments are the fastest growing.
- By region, North America led with a 33.84% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Generative artificial intelligence is changing how scenes are built. Tools that create three-dimensional assets, textures, and characters from text or images are shortening production schedules, and studios are using them to prototype worlds before committing artists and budgets.
Real-time engines are spreading beyond games. Film, automotive, architecture, and retail teams use game engines to build virtual production stages, product configurators, and design reviews that run on headsets, phones, and browsers.
Spatial capture is becoming easier. Phone-based scanning and splat-based reconstruction let creators turn real places into editable three-dimensional scenes, and mapping platforms are letting developers attach content to precise locations.
Common formats and standards are improving portability. OpenXR and OpenUSD support lets creators build once and publish across several headsets, while platform owners add support for new devices and spatial computing systems.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Gaming and Entertainment Demand for Interactive Experiences |
+9.36% |
North America and Asia Pacific |
Short term (2 years or less) |
|
Generative Artificial Intelligence and Real-Time Engines |
+7.14% |
Global |
Short term (2 years or less) |
|
Enterprise Training, Design Review, and Digital Twins |
+5.88% |
North America and Europe |
Medium term (2 to 4 years) |
|
Growing Headset Installed Base and Falling Hardware Costs |
+4.84% |
Global |
Medium term (2 to 4 years) |
|
Interoperability Standards and High-Speed Connectivity |
+3.66% |
Global |
Long term (4 years or more) |
Gaming and Entertainment Demand for Interactive Experiences
Gaming remains the largest source of immersive content demand, and studios are building virtual reality and augmented reality titles for headsets, phones, and consoles. Streaming platforms, theme parks, and live event producers are also commissioning immersive video and interactive experiences to hold audience attention. Each project requires capture equipment, engines, modeling tools, and production services, which supports spending across hardware, software, and services. Consumers who own headsets expect a steady flow of new titles, and that expectation keeps studios investing in tools and talent.
Generative Artificial Intelligence and Real-Time Engines
Artificial intelligence is lowering the cost and time needed to produce three-dimensional content. Tools that generate meshes, textures, animation, and environments from prompts let small teams produce work that once required large studios. Engine vendors continue to release versions with virtual production, digital human, and automation features. Faster iteration widens the pool of creators, including advertisers, educators, and independent developers, and it raises the volume of projects started each year. Subscription pricing for these tools turns creative demand into recurring software revenue.
Enterprise Training, Design Review, and Digital Twins
Companies have been using immersive content in their training programs, design evaluations, and collaborative projects. Based on the predictions of the European Commission, the global value of the virtual worlds market is expected to surpass EUR 800 billion by 2030 due to the use of virtual worlds in industries and governments, and the needs of consumers. Automakers, aerospace firms, construction companies, and healthcare organizations develop digital twins and processes that help cut costs for travel and reduce errors. This necessitates content that must be created by certain teams and software.
Growing Headset Installed Base and Falling Hardware Costs
The advent of headsets, light weight glasses, and other forms of spatial computing technology makes immersion more achievable. In fact, with prices reducing and increased comfort levels, consumers and businesses adopt such technologies and hence creating a larger market for new content. To develop applications for such devices, programmers need capture rigs, fast machines, tracking equipment and motion capturing equipment hence the need for hardware sales to studios due to device shipment. Platforms providers also provide developers’ programs and tools which force studios to embrace such devices from the onset. Content libraries expand as installed bases grow.
Interoperability Standards and High-Speed Connectivity
Common standards lower the cost of building for many devices. The Khronos Group released OpenXR 1.1 in April 2024, folding five extensions into the core specification so developers can write applications that run across headsets. Faster mobile and fixed networks also support streaming of rendered scenes and shared virtual spaces. Cloud rendering lets creators publish high-quality experiences to modest hardware, which broadens reach and improves the return on content production budgets across sectors. Open standards reduce vendor lock-in for studios.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Production and Development Costs |
-2.48% |
Global |
Short term (2 years or less) |
|
Fragmented Platforms and Hardware Standards |
-1.86% |
Global |
Medium term (2 to 4 years) |
|
Hardware Dependency and Comfort Barriers |
-1.34% |
Global |
Medium term (2 to 4 years) |
|
Platform Retrenchment and Monetization Uncertainty |
-0.82% |
North America and Europe |
Long term (4 years or more) |
High Production and Development Costs
Building high-quality immersive content requires skilled artists, engineers, capture equipment, and long testing cycles. Costs are particularly high for photorealistic environments, volumetric capture, and interactive worlds that must run smoothly at high frame rates. Independent creators and small studios often lack funding to compete, and project delays or overruns can end a studio's work. Generative tools are lowering some costs, but quality control and optimization for several devices keep total budgets high for most serious productions. Many projects exceed initial budgets.
Fragmented Platforms and Hardware Standards
There is a need for developers to cater to headsets, operating systems, controllers, and application stores that come with different requirements. The cross-industry standardization body for virtual worlds stated that more than 2,500 member organizations were present in the organization as of June 2026, which reflects the fact that there are so many entities developing these common standards even though there isn’t one standard yet. It results in increased testing costs and delay in release due to optimization required by each platform.
Hardware Dependency and Comfort Barriers
Immersive experiences depend on headsets, powerful graphics processors, and reliable tracking. Cost, weight, and fatigue prevent many users from using gadgets, while some users suffer motion sickness. These problems restrict the number of audiences and their use duration, thus affecting the monetization capabilities of the produced content. Companies have to do procurements and management in case of deploying large numbers of devices. Until gadgets become light and affordable, content producers cannot aim at larger audiences than mobile or console games. Some users abandon devices after early trials. Retention is therefore weak.
Platform Retrenchment and Monetization Uncertainty
Strategic shifts by large platform owners can change the market quickly. The withdrawal of flagship virtual worlds from headset stores shows how such moves can unsettle studios that built on a platform. Business models for immersive content remain unproven, with uneven app store revenue and piracy concerns. Investors become cautious when audiences grow more slowly than expected, and some studios pivot to mobile or traditional formats, which reduces demand for specialized tools and services. Funding for experimental projects has tightened.
Immersive Content Creation Market Segment Analysis
By Component, Hardware Dominates Immersive Content Creation Market; Software to Register Fastest Growth.
Hardware held a 39.84% share in 2025 because creators need capture cameras, headsets for testing, motion tracking systems, and high-performance workstations before any content can be produced. Studios and enterprises refresh equipment as devices improve, and large projects such as volumetric stages require significant capital. Hardware spending also rises with each new device generation, which keeps this component the largest part of the market in early stages of adoption. Rental markets for specialized rigs also help smaller studios.
The software segment is expected to witness the highest CAGR of 26.08% during the years from 2026 through 2035. Game engines, 3D design software, spatial capture, and AI generators have moved towards a subscription system where the customers will pay for the usage of their tools until they keep working on them. The cloud services for collaboration and automation have widened the customer base to non-professional artists as well. Training materials and certification programs help new users.
By Technology, Virtual Reality Dominates Immersive Content Creation Market; Augmented Reality to Register Fastest Growth.
Virtual reality has an ownership share of 38.26% in 2025 since gaming, simulation, and training titles have been developed for fully immersive headsets for a longer time than in any other platform. The studios have developed well-built pipelines, engines, and distribution stores for these platforms, and the users expect to have finished titles in the stores. Additionally, the enterprise users depend on virtual spaces for training for their safety, which ensures that virtual reality will continue to be the core of development and expenditure.
Augmented reality is expected to register the fastest growth, with a CAGR of 26.34% from 2026 to 2035. Phones, glasses, and spatial computers can overlay content on real surroundings, and marketers, retailers, and manufacturers are adopting these experiences for product visualization and remote assistance. Location mapping tools allow content to attach to real places. Mixed reality and other formats also grow, but augmented reality reaches the broadest audience through devices people already own. Prices for compatible devices continue to fall.
By End Use, Gaming Dominates Immersive Content Creation Market; Entertainment and Media to Register Fastest Growth.
Gaming represented a 32.14% share in 2025 because players are the most active users of immersive devices and studios have the strongest production capability. Game developers adopt new engines, motion capture, and spatial audio tools quickly, and a single successful title can drive many headset sales. Established distribution stores and a culture of frequent releases make gaming the largest and most reliable source of demand for creation tools and services. Publishers fund tools and talent aggressively through internal studios.
The entertainment and media segment is forecasted to grow at the highest rate of 25.62%, from 2026 to 2035. Studios, television stations, music promotions, and sports organizations have started to create documentaries, live events, and venues using immersive technology for those who cannot attend physically. The virtual production sets are also leveraging game engines to expedite the filming process. Education and training, healthcare, retail, and automotive uses expand as well, but media projects attract the largest new creative budgets. Partnerships between studios support the shift.
By Content Format, Immersive Video Dominates Immersive Content Creation Market; Interactive Games and 3D Environments to Register Fastest Growth.
Immersion videos accounted for 34.86% of the share because they are the fastest media form to produce and disseminate, using multiple camera systems and conventional editing software. Companies use videos for story telling purposes and also as a mode of training, which can be viewed on mobile phones and inexpensive headsets. Lower production complexity compared with fully interactive worlds helps this format reach more buyers, which keeps it the largest by value. Distribution is simple across web, social, and mobile channels for most buyers.
Interactive games and 3D environments will grow rapidly with a compound annual growth rate of 27.46%. Real-time engines, procedural generation, and AI software make it possible to create explorable environments at reduced cost, and consumers would like to act rather than observe. Enterprise digital twins and virtual showrooms create additional demand. 360-degree photography continues to be widely used for property tours and tourism purposes, although with a lower rate of growth. Photogrammetry tools help teams capture real spaces quickly and cheaply today.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
71.35% |
|
Asia Pacific |
China |
38.64% |
|
Europe |
Germany |
24.86% |
|
Middle East & Africa |
Saudi Arabia |
31.47% |
|
Latin America |
Brazil |
46.28% |
North America Immersive Content Creation Market
North America held the largest share of the market at 33.84% in 2025, supported by game studios, technology platforms, and a deep base of enterprise buyers. The United States accounted for most regional demand, with a 2025 value of USD 4.71 Billion, and is expected to grow at a CAGR of 22.58% from 2026 to 2035. Canada adds demand through its game development hubs and visual effects industry. Demand is broad-based across industries. Games conventions and trade shows support deal making.
Many of the leading engine, design software, and device makers are headquartered in the region, and they invest heavily in developer programs and creator tools. Hollywood and the games industry are adopting virtual production and immersive formats, while defense, healthcare, and manufacturing buyers deploy training simulations. Venture funding for spatial capture and generative design start-ups continues to support new tool launches. Universities and research labs also contribute talent and open-source tools, and tax incentives in several states and provinces support studio expansion.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Immersive Content Creation Market
The Asia-Pacific region is estimated to grow at the highest pace in the coming years, at a CAGR of 27.14% from 2026 to 2035. This is because China, Japan, South Korea, and India have a combination of a huge population of gamers, device manufacturing, and government backing in digital sectors. Mobile games and short video platforms are incorporating augmented reality for their users, generating a need for creation software. Income generation is also enabled by mobile payments and short videos.
China has the biggest national market, with domestic producers of headsets and large technology companies supporting studios producing content. Japan and South Korea have well-established animation and gaming industry sectors that are using virtual production, whereas India is creating its creator community by using low-cost devices and outsourcing studios. Government programs for the digital economy and education add demand across the region. Australia adds demand through its visual effects industry and training programs, and Southeast Asian countries are growing gaming communities that attract new studios and tool vendors.
Europe Immersive Content Creation Market
Europe holds a solid foundation in the areas of film, design, automotive, and cultural institutions that utilize immersive media. Germany, the UK, France, and the Nordic states contribute to the majority of regional investments. The ITU, an organization that operates out of Geneva, launched the Virtual Worlds Standards Joint Coordination Activity in May 2025, demonstrating the region’s desire for the creation of standardization and interoperability in virtual worlds. Immersive storytelling is promoted via film festivals and cultural funds. Media funds within the region fund cross-border immersive productions.
Real-time engines are used by game and visual effects producers from Europe to develop their projects, while museums and tourist organizations use them to organize virtual tours. Automotive and industrial organizations use immersive technologies to facilitate the process of designing and training. Financial support is provided to encourage the development of innovative technologies, whereas privacy laws regulate the production and distribution of biometric or geographic content. Eastern European studios provide outsourcing services in the sphere of art and engineering at lower prices. Procurement is gradual.
Middle East & Africa Immersive Content Creation Market
The Middle East & Africa region holds a small share, yet Gulf countries are investing in entertainment, tourism, and digital economy programs that include immersive experiences. Saudi Arabia and the United Arab Emirates lead regional spending, funding game studios, theme parks, and virtual heritage projects as part of national diversification plans. South Africa and Egypt add smaller volumes through animation and visual effects work. Large events and tourism projects in Riyadh and Dubai commission immersive installations. Sovereign funds finance many projects.
Hardware gets into the region mainly by imports. Meanwhile, local entrepreneurs are developing their expertise through accelerator programs and partnerships with universities. While sports and events marketing is looking at creating virtual experiences for its fans, the governments are focusing on simulations training for educational and healthcare reasons. There is room for growth in a rather small market thanks to better connectivity and funding for creative industries. The cost of internet and devices is a major factor limiting the growth of virtual experiences, hence funding goes to lower cost mobile solutions.
Latin America Immersive Content Creation Market
Latin America is a developing market, with Brazil and Mexico accounting for most spending. The region has a large mobile gaming audience and growing independent studios, and advertisers use augmented reality filters and immersive campaigns on social platforms. Outsourced animation and visual effects work for international productions provides additional experience with three-dimensional tools and pipelines. Advertisers in São Paulo and Mexico City also fund augmented reality campaigns that reach large social audiences. Regional publishers also localize titles for Spanish and Portuguese speakers.
Costs of devices and poor connectivity have been a hindrance to the uptake of headsets as platforms for consumption of content. This is why most innovations tend to be centered around mobile phones. Argentina, Colombia, and Chile increase demand by engaging in initiatives such as education, tourism, and cultural activities. The creation of regional accelerators and support for creative industries through public funding is aiding in setting up of new studios while cloud-based technology has reduced investment required to initiate production. Remote work has also opened export opportunities for freelance artists.
Competitive Landscape
The competitive landscape is fragmented, with game engine providers, design software groups, graphics hardware makers, platform owners, spatial capture specialists, and a large number of production studios. Leading suppliers compete on tool quality, ecosystem size, ease of publishing across devices, and artificial intelligence features, while newer entrants compete on spatial capture and browser-based creation. No firm holds a dominant share, because creators combine tools from several suppliers.
Strategy revolves around updates to engines and tools, generation of artificial intelligence, support for open standards, and partnerships with devices manufacturers and cloud services providers. Some companies have also been making investments in developer ecosystems, digital twin technologies, virtual production capabilities, as well as acquisitions that bring in capabilities of capture and collaboration.
Immersive Content Creation Market Industry Leaders
1. Unity: Provider of a real-time three-dimensional development platform used to build games and immersive applications, including support for Android XR devices.
2. Epic Games: Developer of Unreal Engine, widely used for games, virtual production, and immersive experiences, and a participant in the OpenXR standard.
3. Adobe: Software company whose Substance 3D collection and Firefly generative tools support three-dimensional asset creation and design workflows.
4. Autodesk: Design software provider offering immersive tools such as Workshop XR for design review in architecture, engineering, and manufacturing.
5. NVIDIA: Supplier of graphics processors and the Omniverse platform built on OpenUSD for collaborative three-dimensional content and digital twins.
Companies Covered in this Report
- Unity
- Epic Games
- Adobe
- Autodesk
- NVIDIA
- Apple
- Snap
- Niantic Spatial
- Matterport
- Varjo
- Magnopus
- Meta
Recent Industry Developments
- February 2025: CoStar Group completed its acquisition of Matterport to expand its three-dimensional digital twin offerings.
- June 2025: Apple introduced visionOS 26 with new spatial scene capabilities for developers building experiences for Apple Vision Pro.
- October 2025: Unity made Android XR support generally available in Unity 6, with launch experiences on Samsung Galaxy XR.
- March 2026: Adobe announced a cloud-native three-dimensional digital twin solution in public beta, built on OpenUSD technology.
- April 2026: Niantic Spatial launched Scaniverse for business along with an updated visual positioning system and developer kit.
- June 2026: Epic Games released Unreal Engine 5.8 with MetaHuman and virtual production updates.
Scope and Research Methodology
This report defines the Immersive Content Creation Market as the commercial value of hardware, software, and services used to design, capture, produce, and publish virtual, augmented, and mixed reality content, including cameras, engines, authoring tools, and production services. Consumer headsets sold purely for playback are excluded, as are finished games and media titles. Values are stated in USD at vendor selling prices, including subscription revenue. The base year is 2025 and the forecast runs from 2026 to 2035. Gaming hardware used only for play, such as consoles and controllers, is excluded from the estimate, and platform fees collected by stores are not counted.
Primary research comprised interviews with studio heads, technical artists, enterprise training managers, procurement officers, system integrators, and executives at engine, design software, and capture hardware vendors. Secondary research drew on standards body publications, company filings, developer documentation, product catalogs, and industry association releases. Tool seats and equipment shipments were linked to studio counts, developer surveys, and enterprise deployments in each country, then converted to value using license and hardware pricing. Each interview followed a structured guide covering production pipelines, tool spending, hardware refresh cycles, pricing, and adoption barriers, and responses were coded by region and studio size so that patterns could be compared across countries.
A bottom-up build by component, technology, and country was cross-checked against a top-down view based on creative software and digital media spending. Forecasts apply growth rates by segment that reflect device adoption, engine releases, and pricing trends, with scenarios for platform strategy changes. Regional shares were validated against studio counts and developer activity, and the five regions sum to the global figure. Findings were reviewed by internal analysts and external experts before release. Where estimates differed, analysts revisited assumptions on seat counts and equipment pricing and consulted additional experts until the figures converged on a single view. Documentation is retained for audit.
Immersive Content Creation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 19.52 Billion |
| Market Size by 2035 | USD 172.98 Billion |
| CAGR | CAGR of 24.38% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Hardware, Software, and Services) • By Technology (Virtual Reality, Augmented Reality, Mixed Reality, and Others) • By End Use (Gaming, Entertainment and Media, Education and Training, Healthcare, Retail and E-Commerce, Automotive, and Others) • By Content Format (Immersive Video, 360-Degree Photography, Interactive Games and 3D Environments, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Unity, Epic Games, Adobe, Autodesk, NVIDIA, Apple, Snap, Niantic Spatial, Matterport, Varjo, Magnopus, Meta, Google |

Frequently Asked Questions
The market was valued at USD 19.52 Billion in 2025 and is estimated at USD 24.28 Billion in 2026. It is forecast to reach USD 172.98 Billion by 2035.
The market is projected to expand at a CAGR of 24.38% from 2026 to 2035.
North America led with a 33.84% share in 2025, while Asia Pacific is the fastest-growing region, with a CAGR of 27.14% from 2026 to 2035.
Hardware held the largest share, at 39.84% in 2025, while software is expected to grow fastest.
Entertainment and media is expected to record the fastest growth, with a CAGR of 25.62% from 2026 to 2035.
Gaming and entertainment demand, generative artificial intelligence and real-time engines, enterprise training and digital twins, a growing headset installed base, and interoperability standards.
High production costs, fragmented platforms, hardware dependency and comfort barriers, and platform retrenchment with monetization uncertainty.
