
In-flight Entertainment & Connectivity Market Report Scope & Overview:
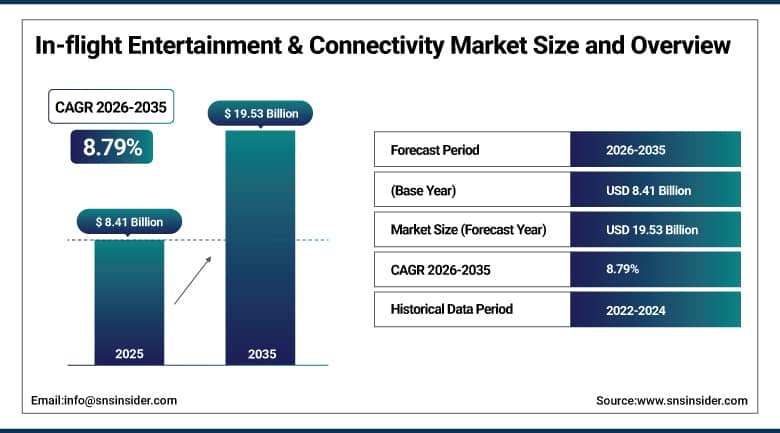
The In-flight Entertainment & Connectivity Market was valued at USD 8.41 Billion in 2025 and is expected to reach USD 19.53 Billion by 2035, growing at a CAGR of 8.79% from 2026-2035.
Passenger expectations for seamless digital experiences at 35,000 feet have rapidly evolved, driving airlines to redefine their in-flight entertainment and connectivity strategies across their fleets. As travelers increasingly anticipate high-speed internet, on-demand content, and personalized services comparable to what they experience at home or in the office, carriers must continuously balance technological innovation against operational complexity and cost pressures throughout their cabin modernization programs. In-flight entertainment and connectivity refers to the full range of technologies and services provided to passengers during air travel, spanning movies, television shows, music, and games delivered through seat-back or wireless streaming systems, alongside the broadband internet access that has become an increasingly central expectation for both leisure and business travelers alike. The surging global air travel market, ongoing technological advancements in satellite communication, high investment in research and development activities, and a rising number of long-haul flights continue fueling sustained market growth, while airlines' increasing focus on passenger well-being and differentiated onboard experience continues to reinforce the strategic importance of comprehensive entertainment and connectivity offerings.
On September 8, 2025, Panasonic Avionics Corporation and Intellian Technologies announced a new high-performance, cost-effective low earth orbit-only terminal system designed to connect to Eutelsat's OneWeb LEO network. The new terminal system features Intellian's LEO-only aviation antenna, seamlessly integrating the modem and controller into a design that requires no radome, with Panasonic Avionics indicating that many airlines are expected to adopt a multi-terminal approach that allows them to quickly and affordably add this capability to any connectivity-equipped aircraft, immediately offering multi-orbit capabilities that improve passenger satisfaction, drive net promoter scores, and enhance loyalty while increasing onboard connectivity revenue.
Market Size and Forecast
-
Market Size in 2026E: USD 9.15 Billion
-
Market Size by 2035: USD 19.53 Billion
-
CAGR (2026-2035): 8.79%
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get More Information On In-flight Entertainment & Connectivity Market - Request Free Sample Report
In-flight Entertainment & Connectivity Market Trends
-
Rising adoption of multi-orbit satellite connectivity combining geostationary and low earth orbit constellations for improved coverage.
-
Growing shift toward free, complimentary onboard WiFi as airlines compete on passenger experience differentiation.
-
Expanding retrofit activity as airlines upgrade legacy aircraft fleets with modern, high-resolution entertainment systems.
-
Increasing adoption of bring-your-own-device wireless streaming reducing dependence on embedded seat-back hardware.
-
Rising demand for personalized content recommendation systems leveraging passenger data and viewing history.
-
Growing strategic partnerships between IFEC providers and emerging low earth orbit satellite constellation operators.
U.S. In-flight Entertainment & Connectivity Market Outlook
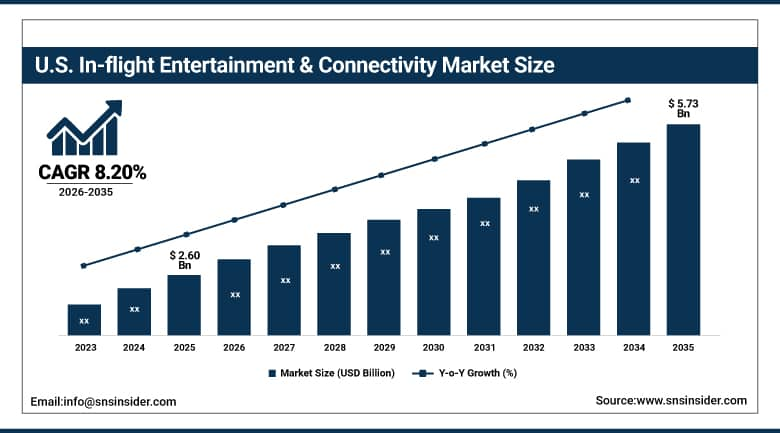
The U.S. In-flight Entertainment & Connectivity Market was valued at USD 2.60 Billion in 2025 and is expected to reach USD 5.73 Billion by 2035, growing at a CAGR of 8.20% from 2026-2035.
The U.S. In-flight Entertainment & Connectivity Market continues to benefit from intense competitive dynamics among major domestic carriers racing to differentiate their passenger experience through connectivity offerings, alongside sustained investment in satellite communication infrastructure supporting both narrow-body and wide-body fleet connectivity. Airline inflight WiFi in the United States continues converging toward free access as a standard passenger expectation, with most carriers offering complimentary connectivity or pricing that hovers around eight dollars per flight, reflecting a broader competitive shift away from per-flight or per-session pricing models toward connectivity positioned as a core component of the overall passenger experience rather than a premium add-on service. Domestic carriers continue investing substantially in transitioning legacy air-to-ground connectivity systems toward faster, more reliable satellite-based alternatives capable of supporting streaming-quality bandwidth throughout entire domestic and international route networks.
American Airlines announced that free WiFi would begin rolling out in January 2026, applying to aircraft equipped with Viasat and Intelsat, formerly Gogo, satellite internet systems, though widebody aircraft equipped with Panasonic internet would not initially offer complimentary access under the new policy. This announcement followed Delta Air Lines' earlier decision to drop Gogo internet from its main domestic fleet in favor of Viasat, a transition the carrier indicated would better support its broader effort to stream content directly to seat-back entertainment screens, illustrating how domestic carriers continue actively reshaping their connectivity provider relationships as they compete on both pricing and underlying technical performance.
In-flight Entertainment & Connectivity Market Segment Analysis
-
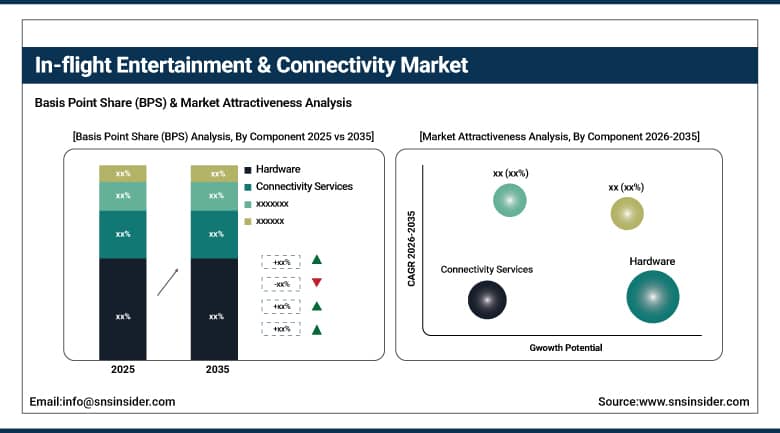
By Component, the Hardware segment dominated the In-flight Entertainment & Connectivity Market with approximately 44.60% share in 2025, while the Connectivity Services segment is the fastest growing with a CAGR of approximately 10.20%.
-
By Aircraft Type, the Narrow-Body segment dominated the In-flight Entertainment & Connectivity Market with approximately 51.60% share in 2025, while the Regional Jets segment is the fastest growing with a CAGR of approximately 10.60%.
-
By Fit Type, the Retrofit segment dominated the In-flight Entertainment & Connectivity Market with approximately 52.60% share in 2025, and is also the fastest growing with a CAGR of approximately 10.20%.
-
By End User, the Commercial Airlines segment dominated the In-flight Entertainment & Connectivity Market with approximately 82.60% share in 2025, while the Business Aviation segment is the fastest growing with a CAGR of approximately 9.60%.
By Component, Hardware Dominates the In-flight Entertainment & Connectivity Market and Connectivity Services Grows Fastest
Hardware dominates the market because of the extensive usage of seat-back entertainment systems, in-flight onboard servers, and antenna installations, as well as the broader networking infrastructure required within aircraft cabins to support both entertainment delivery and connectivity services. This dominance continues to be driven by ongoing cabin modernization activities across airplane fleets worldwide, as airlines increasingly recognize that the physical hardware installed throughout the cabin represents both a substantial capital investment and a foundational enabler for whatever content delivery and connectivity services the airline ultimately chooses to layer on top of that infrastructure. Hardware's strong presence spans both new aircraft deliveries, where original equipment manufacturers increasingly integrate IFEC systems directly into the production line, and extensive retrofit projects across existing fleets, where airlines invest in upgrading older cabin interiors with modern seat-back displays, improved antenna systems, and updated onboard server architecture.
Connectivity services represent the fastest-growing component category, driven by the growing need among airlines for reliable broadband connectivity in-flight, combined with the expanding penetration of satellite-based connectivity services capable of delivering genuinely usable bandwidth throughout even the longest intercontinental flight segments. As passenger expectations for streaming-quality connectivity continue climbing toward parity with home and office internet experiences, airlines increasingly view connectivity services not merely as a technical capability but as a genuine revenue-generating opportunity, whether through direct passenger payment, sponsored free access models, or bundled loyalty program benefits designed to drive customer retention.
By Aircraft Type, Narrow-Body Dominates the In-flight Entertainment & Connectivity Market and Regional Jets Grows Fastest
Narrow-body aircraft hold the largest aircraft type share, reflecting their status as the workhorses of global point-to-point airline networks, typically featuring a fuselage diameter of three to four meters and a single aisle accommodating between 100 and 240 passengers depending on specific aircraft configuration. Narrow-body aircraft continue to be increasingly equipped with in-flight entertainment and connectivity systems, particularly wireless solutions that allow passengers to stream content directly to their own personal devices rather than relying exclusively on embedded seat-back hardware, an approach that can reduce both installation weight and capital cost while still delivering a satisfying entertainment experience. These aircraft often operate multiple flights per day across dense short-to-medium-haul route networks, substantially increasing the cumulative opportunities for passengers to access and benefit from in-flight entertainment and connectivity services relative to less frequently utilized aircraft types, while also benefiting from greater availability of production linefit slots at original equipment manufacturer assembly lines given the sheer production volume of narrow-body platforms relative to wide-body aircraft.
Regional jets represent the fastest-growing aircraft type, as low-cost carriers increasingly expand their route networks into secondary cities where brand loyalty is increasingly tied to digital touchpoints, including onboard connectivity and entertainment quality, rather than traditional differentiators like lounge access or complimentary meal service. This shift reflects a broader transformation in how airlines, particularly value-focused and regional carriers, compete for passenger loyalty in markets where traditional premium service differentiators carry less weight with cost-conscious travelers who nonetheless still expect a baseline level of digital connectivity throughout their journey.
By Fit Type, Retrofit Dominates the In-flight Entertainment & Connectivity Market and Also Grows Fastest
Retrofit installations dominate the market, experiencing sustained growth due to the increasing number of older aircraft being upgraded with modern in-flight entertainment systems as airlines seek to enhance passenger experience without committing to the substantially larger capital investment that new aircraft acquisition would require. This segment benefits directly from airlines' recognition that a comparatively modest retrofit investment can meaningfully extend the competitive viability of an existing aircraft's passenger experience, particularly as connectivity and entertainment capability increasingly influence booking decisions and customer satisfaction scores across both leisure and business travel segments.
Retrofit installations are also the fastest-growing fit type, as the sheer scale of the global in-service aircraft fleet, the vast majority of which was delivered with entertainment and connectivity technology that has since been substantially surpassed by newer alternatives, continues to create a large and sustained addressable market for upgrade programs. Airlines increasingly view retrofit investment not as a discretionary expense but as a genuine competitive necessity, particularly as rival carriers continue announcing their own fleet-wide upgrade programs that raise the baseline passenger expectation for connectivity quality and entertainment system sophistication across the entire industry.
By End User, Commercial Airlines Dominates the In-flight Entertainment & Connectivity Market and Business Aviation Grows Fastest
Commercial airlines represent the overwhelming majority of end-user demand, reflecting the sheer scale of the global commercial aviation fleet relative to business and private aviation, alongside commercial carriers' substantial and continuously expanding investment in passenger experience differentiation as a core competitive strategy. The scale of global commercial air passenger traffic, combined with intensifying competition among carriers for passenger loyalty in an industry where core transportation service has become increasingly commoditized, continues to reinforce sustained commercial airline investment in entertainment and connectivity capability as one of the few remaining meaningful differentiators available to carriers competing on largely similar route networks and pricing structures.
Business aviation represents the fastest-growing end-user category, as private jet operators and charter services increasingly recognize that connectivity and entertainment capability have become genuine baseline expectations among business aviation passengers accustomed to seamless digital connectivity in their everyday professional lives. Business aviation customers, who often use flight time for continued professional productivity rather than purely leisure purposes, continue driving demand for increasingly capable, low-latency connectivity solutions that support video conferencing and real-time business communication throughout flight, a use case that differs meaningfully from the primarily entertainment-focused connectivity demand that characterizes much of commercial aviation.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Middle East & Africa |
United Arab Emirates |
32.60% |
|
Latin America |
Brazil |
24.60% |
North America In-flight Entertainment & Connectivity Market Insights
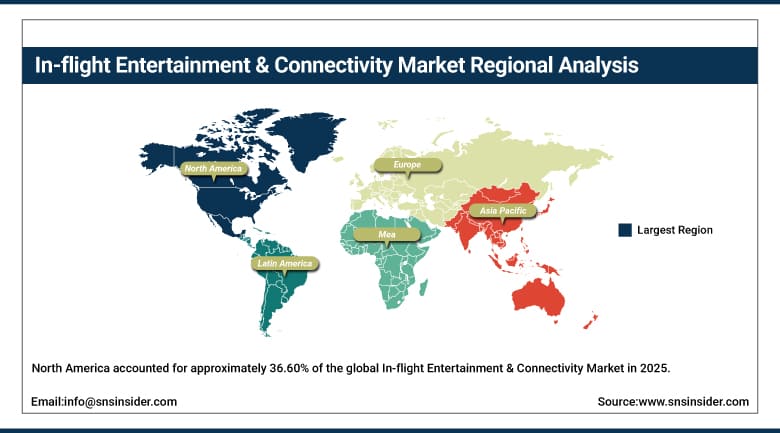
North America accounted for approximately 36.60% of the global In-flight Entertainment & Connectivity Market in 2025, making it the largest regional market, supported by the region's substantial commercial aviation fleet, intense competitive dynamics among major domestic carriers, and sustained investment in satellite communication infrastructure. The United States anchors regional demand through its concentration of leading IFEC hardware manufacturers, satellite connectivity providers, and major commercial airlines that continue competing aggressively on passenger connectivity experience as a core service differentiator. The region's carriers continue racing to transition legacy air-to-ground connectivity systems toward faster, more reliable satellite-based alternatives, with multiple major domestic airlines announcing complimentary WiFi rollouts across substantial portions of their fleets in recent periods, reflecting the competitive pressure that continues to push connectivity from a premium paid service toward a baseline passenger expectation.
Canada is contributing incremental regional demand as its own commercial aviation sector continues investing in passenger experience modernization. Continued domestic investment in multi-orbit satellite connectivity infrastructure, combined with sustained retrofit activity across the region's substantial existing commercial aircraft fleet, is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding markets in Asia Pacific pursuing rapid fleet expansion and connectivity infrastructure buildout.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific In-flight Entertainment & Connectivity Market Insights
Asia Pacific is the fastest-growing regional market, driven by rapidly expanding commercial aviation fleets, rising air passenger traffic, and sustained government and airline investment in aviation infrastructure modernization across China, India, and other major regional economies. China's substantial and continuously expanding domestic commercial aviation fleet continues to anchor regional demand for both linefit and retrofit IFEC installations, as the country's major carriers pursue passenger experience differentiation strategies increasingly aligned with global industry standards. The region's rapidly growing middle-class travel base continues to expand the addressable market for both entertainment content and connectivity services, as rising disposable income across the region translates into growing traveler expectations for the kind of digital connectivity experience increasingly standard across Western commercial aviation markets.
India's rapidly expanding commercial aviation sector, supported by substantial fleet expansion among both established carriers and newer low-cost entrants, continues to contribute meaningful incremental regional growth as domestic and international route networks continue expanding. Japan and South Korea contribute additional scale through established aviation sectors increasingly integrating advanced multi-orbit satellite connectivity, while Southeast Asian carriers continue expanding regional and international route networks that require corresponding connectivity infrastructure investment, reinforcing Asia Pacific's position as the fastest-growing market for in-flight entertainment and connectivity through the forecast period.
Europe In-flight Entertainment & Connectivity Market Insights
Europe represents a significant share of the global In-flight Entertainment & Connectivity Market, anchored by Germany's substantial aviation industrial base and the region's concentration of major legacy carriers continuing to invest in fleet-wide passenger experience modernization programs. European regulatory and competition authorities continue closely monitoring the connectivity provider landscape, reflecting the strategic importance regulators place on maintaining genuine competition within an industry increasingly characterized by consolidation among major satellite connectivity providers serving the region's substantial commercial aviation fleet.
The United Kingdom, France, and other major European aviation markets contribute significant regional demand as national carriers continue extending advanced IFEC system adoption across both new aircraft deliveries and substantial retrofit programs targeting existing fleets. Regional carriers continue pursuing multi-orbit satellite connectivity strategies similar to those adopted across North America, positioning European airlines to maintain competitive parity with global peers on passenger connectivity experience through the forecast period.
MEA & Latin America In-flight Entertainment & Connectivity Market Insights
The Middle East & Africa market is anchored substantially by major long-haul carriers based in the United Arab Emirates and Qatar, which have historically positioned premium in-flight entertainment and connectivity capability as central pillars of their broader passenger experience differentiation strategy on long-haul international routes. These carriers continue investing heavily in cutting-edge IFEC technology as part of their broader competitive positioning against other major global long-haul carriers, reinforcing the region's outsized strategic importance within the global IFEC landscape relative to its overall fleet size.
Latin America's market remains comparatively modest, with Brazil contributing incremental growth as regional carriers continue gradually expanding entertainment and connectivity investment across both domestic and international route networks. Regional carriers continue evaluating multi-orbit satellite connectivity adoption as part of broader fleet modernization strategies, though commercial-scale adoption across the region remains considerably earlier-stage relative to more established global aviation markets.
Market Dynamics
Growth Drivers: Rising Air Passenger Traffic and Passenger Experience Differentiation
Surging global air travel represents the primary driver of In-flight Entertainment & Connectivity Market growth, as rising passenger volumes worldwide continue expanding the addressable base of travelers expecting seamless digital entertainment and connectivity throughout their journey. Ongoing technological advancements in satellite communication technology, combined with high levels of research and development investment across the connectivity provider landscape, continue to make genuinely usable, streaming-quality in-flight connectivity increasingly achievable across a broader range of aircraft types and route profiles than was previously commercially viable. Rising numbers of long-haul flights, which inherently generate greater passenger demand for both entertainment content and reliable connectivity given the extended duration passengers spend confined to their seats, continue to reinforce sustained market growth across the broader IFEC industry.
Increasing focus on passenger well-being and experience differentiation represents a second major growth driver, as airlines increasingly recognize that entertainment and connectivity quality represents one of the few remaining meaningful competitive differentiators available in an industry where core transportation service has become increasingly commoditized across competing carriers. Growing passenger expectations for seamless digital experiences while traveling, shaped substantially by the connectivity quality passengers experience in their everyday personal and professional lives, continue to push airlines toward increasingly aggressive investment in both hardware modernization and connectivity service quality, reinforcing sustained market expansion across virtually every major commercial aviation region worldwide.
Restraints: High Installation Costs and Aircraft Downtime Requirements
The high cost associated with installation and retrofits is a significant constraint in this respect, since a complete overhaul of an IFEC system, which involves replacing of seats with seat back hardware, installation of antenna as well as networking of the plane would need a large amount of money that could not be justified by small or financially strained airlines, especially regional and budget air carriers whose overall margins are lower than those of legacy airlines.
An additional constraint in this respect is the necessity of aircraft downtime, as the process of retrofitting requires taking of planes out of service, which involves an actual opportunity cost that should be carefully considered by the airline before making any decisions. This factor makes it difficult for airlines implementing a comprehensive fleet modernization plan, which usually involves dozens or even hundreds of planes to make such a decision.
Opportunities: Multi-Orbit Satellite Integration and Free Connectivity Monetization
Continued integration of multi-orbit satellite connectivity, combining traditional geostationary coverage with increasingly capable low earth orbit constellations, represents a substantial opportunity, as providers that can successfully deliver seamless, low-latency connectivity across diverse route profiles and geographic regions are positioned to capture demand from airlines seeking genuinely differentiated connectivity performance relative to legacy single-orbit systems. Strategic partnerships between established IFEC providers and emerging low earth orbit satellite operators continue to reshape the competitive landscape, positioning providers with genuine multi-orbit integration capability to capture disproportionate future contract awards.
The continued shift toward free, complimentary onboard connectivity offers a further substantial avenue for growth, as airlines increasingly explore alternative monetization models, including sponsored access, loyalty program integration, and bundled service offerings, that allow them to offer passengers complimentary connectivity while still generating meaningful revenue through indirect channels. Providers and airlines that can successfully develop compelling alternative monetization strategies are well positioned to capture demand from an industry increasingly convinced that complimentary connectivity delivers greater overall passenger loyalty and satisfaction value than traditional per-flight or per-session pricing models.
Recent Developments:
-
In February 2024, Air India selected Thales to retrofit its Boeing 777 and 787 aircraft with the AVANT Up in-flight entertainment system under a contract valued at USD 400 million. The agreement covers upgrades across 40 aircraft, enhancing passenger experience with features including a 4K QLED HDR display and improved connectivity options, with retrofit completion expected by the end of 2025.
-
On June 13, 2025, Viasat announced that its subsidiary Inmarsat Global had agreed to a binding term sheet with Ligado Networks and AST & Science to settle Inmarsat's opposition to Ligado's planned restructuring. Under the agreement, Viasat expects to receive USD 568 million from Ligado by March 31, 2026, funds the company indicated would primarily be used to manage near-term debt maturities.
In-flight Entertainment & Connectivity Market Key Players
-
Panasonic Avionics Corporation
-
Thales Group
-
Collins Aerospace (RTX Corporation)
-
Viasat Inc.
-
Anuvu (Global Eagle Entertainment)
-
Gogo Inc.
-
Honeywell International Inc.
-
Burrana Pty Ltd.
-
Safran S.A.
-
SITA
-
Intelsat S.A.
-
Lufthansa Systems GmbH & Co. KG
-
Astronics Corporation
-
Bluebox Aviation Systems Ltd.
-
Kymeta Corporation
-
SmartSky Networks LLC
-
Airbus S.A.S.
-
Boeing Global Services
-
Zodiac Aerospace (Safran)
-
Global Communications Corp
In-flight Entertainment & Connectivity Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.41 Billion |
| Market Size by 2035 | USD 19.53 Billion |
| CAGR | CAGR of 8.79% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Component (Hardware, Connectivity Services, and Content) • by Aircraft Type (Narrow-Body, Wide-Body, and Regional Jets) • by Fit Type (Linefit and Retrofit) • by End User (Commercial Airlines and Business Aviation) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Panasonic Avionics Corporation, Thales Group, Collins Aerospace (RTX Corporation), Viasat Inc., Anuvu (Global Eagle Entertainment), Gogo Inc., Honeywell International Inc., Burrana Pty Ltd., Safran S.A., SITA, Intelsat S.A., Lufthansa Systems GmbH & Co. KG, Astronics Corporation, Bluebox Aviation Systems Ltd., Kymeta Corporation, SmartSky Networks LLC, Airbus S.A.S., Boeing Global Services, Zodiac Aerospace (Safran), Global Communications Corp |
Frequently Asked Questions
Key players include Panasonic Avionics Corporation, Thales Group, Collins Aerospace, Viasat Inc., Anuvu, Gogo Inc., and Honeywell International Inc., among other IFEC hardware and connectivity providers.
Continued integration of multi-orbit satellite connectivity and the continued shift toward free, complimentary onboard connectivity represent the primary opportunities for providers.
Growth is primarily driven by surging global air travel combined with airlines' increasing focus on passenger well-being and experience differentiation.
By Component, Hardware dominated the market with approximately 44.60% share in 2025, reflecting extensive usage of seat-back entertainment, onboard servers, and antenna installations.
North America dominated the market with approximately 36.60% share in 2025, supported by the region's substantial commercial aviation fleet and intense carrier competitive dynamics.
