
Precision Guided Munition Market Report Scope & Overview:
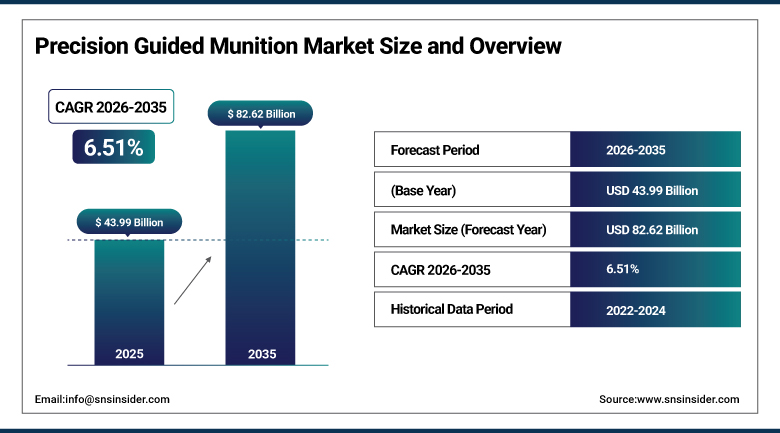
The Precision Guided Munition Market was valued at USD 43.99 Billion in 2025 and is expected to reach USD 82.62 Billion by 2035, growing at a CAGR of 6.51% from 2026 to 2035.
The precision guided munition market is growing at a very high rate due to the growth in military expenditure, emergence of anti-missile defense systems, and advancements in guidance technology. "Precision Guided Munitions" is a name for missiles, rockets, bombs, and artillery rounds that are equipped with different kinds of guidance systems like GPS, laser guidance, inertial guidance, and radar guidance. This allows the targeting of particular objects with great precision while minimizing the risk of collateral damage. Moreover, there are other factors behind the growth of this market, including the increased demand for precision strike weapons, modernization efforts in the military sector, improvements in guidance technologies such as GPS/INS and AI, and interest in the network-centric warfare concept.
The market for Precision Guided Munitions is shifting from an exclusive class of weaponry to one of procurement necessity. The need for accuracy, range, survivability, and safe logistics in contemporary battlefields have enabled continued development of precision guided missiles, precision guided bombs, loitering munitions, precision guided artillery, naval strike missiles, and multi-spectral seekers in smart weapons.
To Get more information Precision Guided Munition Market - Request Free Sample Report
Precision Guided Munition Market Trends
- Rising adoption of AI-enabled and autonomous technologies is improving targeting speed and operational effectiveness in complex battlefield environments.
- Growing focus on operational efficiency is increasing demand for precision systems that reduce logistical requirements while improving mission reliability.
- Increasing adoption of loitering munitions is combining intelligence, surveillance, reconnaissance, and precision-strike capabilities within a single platform.
- Expanding open-mission-system architectures and continuous software updates are enabling faster weapon integration across existing military platforms.
- Strategic partnerships among defense contractors, guidance technology providers, and allied militaries are accelerating development of network-integrated precision munitions.
The U.S. Precision Guided Munition Market Outlook
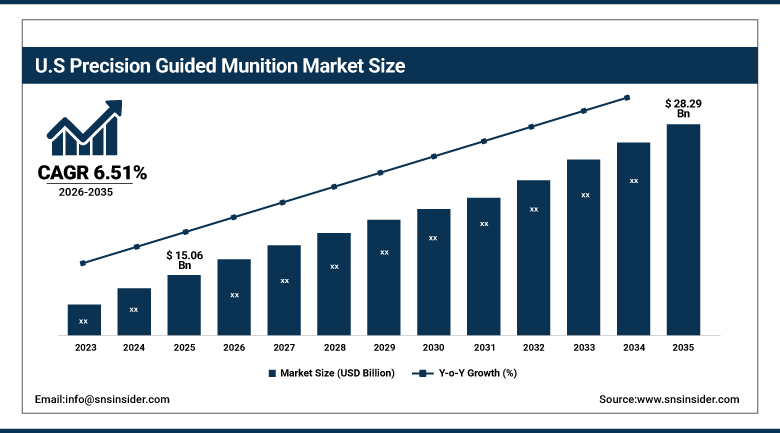
The U.S. precision guided munition market was valued at USD 15.06 Billion in 2025 and is projected to reach USD 28.29 Billion by 2035, growing at a CAGR of 6.51% during 2026–2035.
The major defense contractors in the nation have been expanding their capability for producing precision-guided missiles due to consistently high levels of spending on defense coupled with the procurement of these precision-guided weapons. The increasing need for replenishment in light of the consistent consumption of these munitions in recent wars coupled with modernization efforts in the military continues to drive up the domestic demand for these missiles.
In April 2025, the U.S. Department of Defense’s announced the investment of USD 4.7 billion to expand domestic production of critical munitions, including precision-guided weapons. The initiative supports production-capacity expansion and supply-chain resilience for systems such as the Patriot PAC-3, GMLRS, and other advanced munitions, reinforcing U.S. demand for precision-guided weapon replenishment and modernization.
Precision Guided Munition Market Segment Analysis
- By Technology, GPS dominated the precision guided munition market with a 31.00% share in 2025, while AI-enabled/multi-mode seeker is the fastest-growing technology segment with a CAGR of 9.60% from 2026–2035.
- By Speed, supersonic dominated the precision guided munition market with a 43.27% share in 2025, while hypersonic is the fastest-growing speed segment with a CAGR of 10.29% from 2026–2035.
- By Range, medium-range dominated the precision guided munition market with a 49.87% share in 2025, while long-range is the fastest-growing range segment with a CAGR of 8.43% from 2026–2035.
- By Product Type, tactical missiles dominated the precision guided munition market with a 38.60% share in 2025, while loitering munitions is the fastest-growing product type segment with a CAGR of 9.00% from 2026–2035.
By Technology, GPS dominated the precision guided munition market, while AI-enabled/multi-mode seeker is the fastest-growing segment.
By technology, the GPS segment captured the biggest revenue share of 31% in 2025. GPS-guided munitions remain the dominant technology category owing to their proven accuracy, established integration across major weapon platforms, and cost-effective navigation solution supporting the majority of tactical missile, guided bomb, and artillery munition programs across allied defense forces worldwide.
The AI-enabled/multi-mode seeker segment is expected to register the fastest CAGR of 9.60% during the forecast period 2026-2035. Increasing military interest in self-guided and AI-powered weapon systems that are quick to engage targets has led to a rapid expansion of the sector owing to the fact that militaries prefer multi-mode seekers incorporating GPS, laser, and IR guidance.
By Speed, supersonic dominated the precision guided munition market, while hypersonic is the fastest-growing segment.
By speed, supersonic systems held 43.27% share in 2025, the largest within the speed segmentation. The category of supersonic weaponry retains its dominance in terms of speed due to its proven service record as well as efficient combination of the speed of engagement and compatibility of the platforms for the most part of currently developed tactical missile and guided munition systems around the world.
The hypersonic is expected to grow at a CAGR of 10.29% and is the fastest in all segments in terms of the speed of weapons. The increasing investment into the development of hypersonic strike weapons is being observed, due to the necessity to overcome modern missile defense systems and shorten the time of target engagement.
By Range, medium-range dominated the precision guided munition market, while long-range is the fastest-growing segment.
In terms of range, medium range weaponry, covering 50 to 300 km, earned 49.87% of sales in 2025, ranking first in the range segment. The medium range category continues to be the most popular due to its tactical flexibility in various battle situations since it provides an optimal combination of engagement range and platform compatibility in most strike systems today.
Long-range weapons, exceeding 300 km, represent the fastest-growing slot at an 8.43% CAGR through 2035. Growing demand for standoff strike capability enabling forces to engage targets while remaining outside adversary air defense range is driving rising long-range munition segment growth across an increasingly contested modern battlefield environment.
By Product Type, tactical missiles dominated the precision guided munition market, while loitering munitions is the fastest-growing segment.
The tactical missiles segment is the leading product segment in the market. Tactical missiles remain the dominant product category owing to their established, widely deployed role across air-to-ground, ground-to-ground, and naval strike applications, representing the foundational and most extensively procured precision-guided munition category across global defense forces worldwide.
The loitering munitions segment is expected to register the highest CAGR of 9.0%, due to its ability to combine ISR and precision strike capabilities in a single platform. Growing military demand for loitering munitions offering persistent surveillance combined with on-demand precision strike capability is driving rapid segment growth across increasingly unmanned-platform-integrated modern combat operations.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
France |
27.60% |
|
Asia Pacific |
India |
38.60% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Precision Guided Munition Market Insights
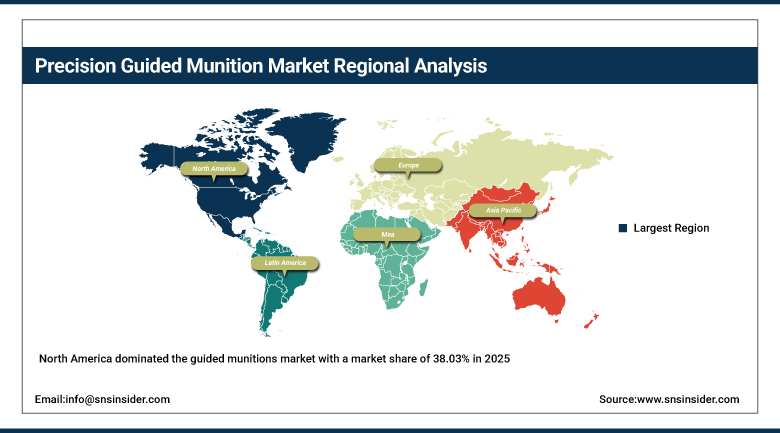
North America dominated the guided munitions market with a market share of 38.03% in 2025, driven by sustained high defense spending, continuous procurement of advanced precision weapons, and substantial domestic defense industrial base across the region.
The US emerged as the dominant market player for the North America precision guided munition market during 2025 owing to its efforts in continuously replenishing its stockpiles and updating its military. The growth in North America can also be attributed to Canada owing to its defense modernization plans.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Precision Guided Munition Market Insights
The Europe precision guided munition market was a significant contributor in 2025. This is attributed to the region's substantial defense industrial base, strong presence of leading precision-guided munition manufacturers, and sustained NATO-aligned military modernization investment across member states.
France is one of the major markets in Europe owing to its strong defense manufacturing base and presence of leading precision munition manufacturers such as MBDA and Thales Group. Other countries such as Germany, home to Rheinmetall AG, and Italy, home to Leonardo S.p.A., are also contributing to market growth through extensive precision munition manufacturing capacity.
Asia Pacific Precision Guided Munition Market Insights
Asia Pacific is also expected to register higher CAGR compared to the other regional markets during the forecast period. This is mainly attributed to increased economic growth and technological advancements in various nations of this region, along with cross-border disputes fueling sustained defense procurement investment.
India is one of the main growth drivers in the Asia Pacific precision guided munition market, owing to its substantial defense modernization investment and growing domestic precision munition manufacturing capability. China and South Korea are also contributing to regional growth through expanding military modernization programs and rising demand for advanced guided weapon systems.
Middle East & Africa and Latin America Precision Guided Munition Market Insights
Regional conflicts and increasing tension in the Middle East & Africa further fuel precision-guided munition demand across the region, while Latin American regions gradually expand market participation as defense modernization investment grows.
Brazil is set to be a prominent Latin American market fueled by growing domestic defense manufacturing capacity and rising military modernization investment. The Middle East & Africa region has UAE and Saudi Arabia investing in modern defense procurement infrastructure that is increasing demand for precision-guided munitions across their expanding military and security sectors.
Market Dynamics
Growth Drivers: Rising military expenditure and precision strike demand driving market growth
Increasing military expenditure, advancements in missile defense systems, and technological developments in guidance technology are among the primary drivers of the precision guided munition market. The rising requirement for precision weapons along with the modernization activities in the defense sector will ensure continuous purchases in the defense sectors for aerial, ground, and naval sectors in various countries due to a preference for systems that have greater efficiency and lower logistics in their operations by armed forces around the world.
Developments in the GPS/INS and AI-enabled technologies, the requirement for reduced collateral damage in modern warfare, and the increasing importance of network-centric warfare system will fuel growth in the market. Modern warfare, the necessity to replenish stockpiles, the requirement for long-range strikes, and the manufacture of guided weapons will aid demand in the forecast period.
Restraints: High procurement costs and regulatory constraints limiting market expansion
One of the main barriers to market growth is federal and legislative rules and regulations governing precision-guided munition export and procurement, which continue to constrain cross-border sales and complicate defense contractor operations across multiple international markets.
Also, cost and lack of budget continue to limit further growth in the market since the advanced guidance technology involving GPS, lasers, and multi-mode seekers are relatively expensive for each unit purchased and might put strain on the defense budget, especially among the smaller allies that want to modernize their precision strike technology. There have been a lot of issues with the expense of such ammunition.
Opportunities: Expansion of hypersonic capability and loitering munition platforms creating new growth avenues
Growing military investment in hypersonic strike capability, projected to register the fastest speed-category CAGR at 10.29%, represents a substantial opportunity for defense contractors capable of developing next-generation weapons that defeat increasingly sophisticated missile defense systems.
There is a considerable growth opportunity in the continued expansion of loitering munitions combining ISR and precision strike capabilities in a single platform. The expansion of defense modernization programs and rising cross-border tensions in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Lockheed Martin expanded its Precision Strike Missile (PrSM) production capacity, strengthening its ability to supply growing US Army and allied demand for long-range precision strike munitions.
- 2025: RTX Corporation launched an updated GPS-guided precision munition variant designed for allied export markets, offering international defense customers enhanced targeting accuracy and reliability.
- 2026: General Atomics expanded its loitering munition production capacity, strengthening its ability to supply growing demand for unmanned platform-integrated ISR and precision strike systems.
- 2026: MBDA launched a new hypersonic-capable precision strike weapon development program, targeting European and allied defense forces seeking next-generation standoff strike capability.
Precision Guided Munition Market key players are:
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- RTX Corporation
- The Boeing Company
- General Dynamics Corporation
- BAE Systems plc
- MBDA
- Thales Group
- Leonardo S.p.A.
- Israel Aerospace Industries Ltd.
- Rheinmetall AG
- Saab AB
- Elbit Systems Ltd.
- Kongsberg Gruppen ASA
- General Atomics
- Diehl Defence GmbH & Co. KG
- Roketsan A.S.
- Nammo AS
- Hanwha Aerospace Co., Ltd.
- Denel Dynamics
Precision Guided Munition Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 43.99 Billion |
| Market Size by 2035 | USD 82.62 Billion |
| CAGR | CAGR of 6.51% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (GPS, Laser Guidance, Infrared, Radar Homing, Others) • By Speed (Subsonic, Supersonic, Hypersonic) • By Range (Short-Range, Medium-Range, Long-Range) • By Product Type (Tactical Missiles, Guided Rockets & Artillery, Guided Ammunition, Loitering Munitions, Interceptor Missile, Torpedoes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, The Boeing Company, General Dynamics Corporation, BAE Systems plc, MBDA, Thales Group, Leonardo S.p.A., Israel Aerospace Industries Ltd., Rheinmetall AG, Saab AB, Elbit Systems Ltd., Kongsberg Gruppen ASA, General Atomics, Diehl Defence GmbH & Co. KG, Roketsan A.S., Nammo AS, Hanwha Aerospace Co., Ltd., Denel Dynamics. |
Frequently Asked Questions
Key players in the Precision Guided Munition Market include Lockheed Martin Corporation, Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems plc, and General Dynamics Corporation, among others.
Key opportunities in the Precision Guided Munition Market include AI-enabled guidance systems, loitering munitions, stockpile replenishment, network-centric warfare capabilities, and military modernization programs.
The market is driven by increasing military expenditure, advancements in missile defense systems, and technological developments in guidance technology.
The GPS segment dominated the Precision Guided Munition Market, accounting for approximately 31% market share.
The North America region dominated the Precision Guided Munition Market in 2025 with a market share of 38.03%.
