
Inclusive Packaging Market Report Scope & Overview:
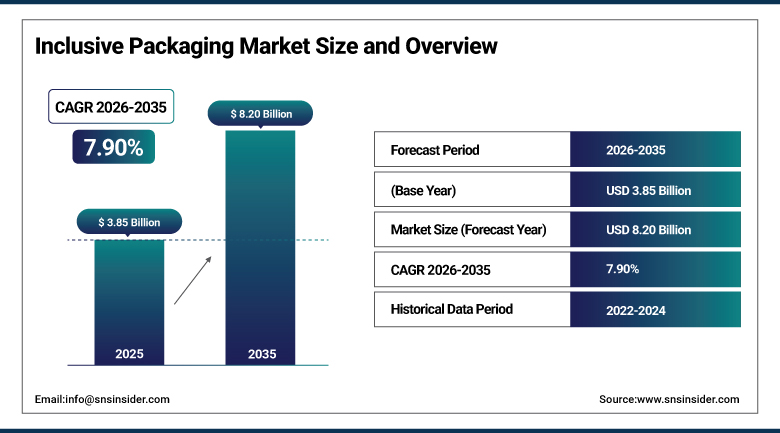
The Inclusive Packaging Market was valued at USD 3.85 Billion in 2025 and is expected to reach USD 8.20 Billion by 2035, growing at a CAGR of 7.90% from 2026 to 2035.
The inclusive packaging market rests on a fact most brands overlooked for decades, people with disabilities and arthritis control a genuinely enormous share of consumer spending, with disposable income among people with disabilities in the United States alone exceeding USD 490 billion and global figures topping USD 1.2 trillion. Frustrating packaging, a jar that will not twist open, text too small to read, a cap that requires two functioning hands, causes real product abandonment and misuse rather than just mild annoyance, and brands are increasingly recognizing that fixing this problem serves a far broader audience than the disability community alone. Seniors, caregivers, and simply anyone juggling groceries with one hand all benefit from the same design principles, which is turning inclusive packaging from a niche accessibility initiative into a mainstream competitive differentiator.
The body wash from Procter & Gamble’s OLAY line that came out in 2025 is the Indulgent Moisture Body Wash with a tactile identifier built into the packaging of the bottle itself, making it the first body wash to feature a tactile identifier for the visually impaired.
To Get more information Inclusive Packaging Market - Request Free Sample Report
Inclusive Packaging Market Trends
- Tactile symbols molded directly onto product packaging are expanding beyond pharmaceuticals into mainstream personal care and food categories.
- Brands are increasingly declining to patent accessible packaging innovations, sharing designs openly to accelerate industry-wide adoption.
- High-contrast labeling and larger typography are becoming standard specifications rather than premium accessibility features.
- Universal Design principles are extending from packaging into broader product and workplace accessibility initiatives at major consumer goods companies.
- Award recognition programs for inclusive packaging design are pushing brands to compete on accessibility alongside sustainability credentials.
The U.S. Inclusive Packaging Market Outlook
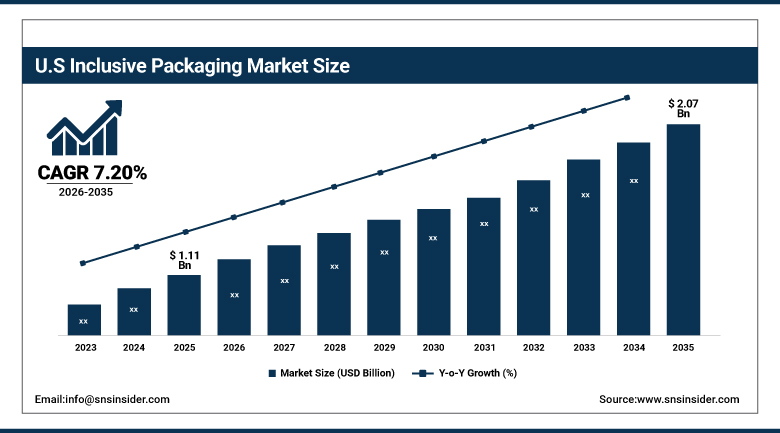
The U.S. inclusive packaging market was valued at USD 1.11 Billion in 2025 and is projected to reach USD 2.07 Billion by 2035, growing at a CAGR of 7.20% during 2026-2035.
The trend of inclusive packaging design in the U.S. is now largely driven by the innovation in the field of consumer goods developed domestically with accessibility and usability as primary aims. For instance, the U.S. division of Procter & Gamble company has launched Olay’s Easy Open Lid with a winged cap, an elevated grip, high contrast labeling, and braille text for some of their moisturizers. Created with consideration of customers’ needs suffering from difficulties of movement, joint pains, limb dissimilarities, and vision problems, the design itself was deliberately left open to patents to stimulate its application throughout the whole industry. Tactile elements have also been integrated into the packaging of Herbal Essences by P&G to help recognize shampoo and conditioner through touch.
Procter & Gamble Company developed an Easy Open lid for its Olay North America line featuring a winged cap, extra-grip raised design, Braille text, and high-contrast labeling, and chose not to patent the design so other manufacturers could adopt it freely.
Inclusive Packaging Market Segment Analysis
- By Feature Type, easy-open closures dominates the inclusive packaging market with easy-open closures holding 38% share in 2025 while tactile & braille labeling grows fastest registering a CAGR of 9.60% from 2026 to 2035.
- By End-Use Industry, pharmaceuticals dominates the inclusive packaging market with pharmaceuticals holding 34% share in 2025 while food & beverage grows fastest registering a CAGR of 9.20% from 2026 to 2035.
- By Material, plastic dominates the inclusive packaging market with plastic holding 46% share in 2025 while paper & paperboard grows fastest registering a CAGR of 8.80% from 2026 to 2035.
- By End-User Demographic, seniors & elderly dominates the Inclusive packaging market with seniors & elderly holding 42% share in 2025 while individuals with disabilities grows fastest registering a CAGR of 10.20% from 2026 to 2035.
By Feature Type, easy-open closures dominates the inclusive packaging market while tactile & braille labeling grows fastest
Easy-open closures hold 38% of the inclusive packaging market, the largest single category, benefiting from being the most universally applicable accessibility feature across virtually every packaged product category, from food jars to household cleaning products to personal care bottles. Winged caps and extra-grip raised lid designs address the single most common packaging frustration, difficulty applying enough torque to open a container, making this feature the natural starting point for most brands' inclusive packaging initiatives.
Tactile & braille labeling is growing at a 9.60% CAGR, the fastest pace among feature types, as brands increasingly mold identifying symbols and text directly into packaging to help blind and low-vision consumers identify products independently rather than relying on separate, easily lost labeling accessories. Growing brand recognition programs specifically rewarding tactile innovation are reinforcing adoption well beyond the pharmaceutical applications where Braille labeling originated.
By End-Use Industry, pharmaceuticals dominates the inclusive packaging market while food & beverage grows fastest
Pharmaceuticals accounts for 34% of end-use demand, the largest single category, reflecting how directly medication access ties to patient safety and independence, a stakes level that has made accessible packaging close to a baseline expectation rather than a discretionary feature in this industry. Regulatory attention to medication error prevention has reinforced pharmaceutical packaging's leadership position in accessibility innovation for decades.
Food & beverage is the fastest-growing end-use industry, expanding at a 9.20% CAGR, as major consumer goods brands increasingly extend accessibility features from flagship personal care products into everyday grocery and household items where the same population of arthritis sufferers and seniors does the bulk of their shopping. Growing consumer expectation that accessibility features should extend across an entire brand portfolio, not just a single flagship product, is reinforcing this segment's above-average growth.
By Material, plastic dominates the inclusive packaging market while paper & paperboard grows fastest
Plastic holds 46% of the market by material, remaining the dominant choice because it offers the manufacturing flexibility needed to mold tactile symbols, ergonomic grip textures, and winged cap designs directly into the packaging structure itself. Established plastic molding infrastructure across the packaging industry also keeps this material the most economical option for brands scaling accessible redesigns across large product portfolios.
Paper & paperboard is growing fastest, at an 8.80% CAGR, as brands increasingly combine sustainability commitments with accessibility goals, developing embossed tactile elements and high-contrast printed labeling on fiber-based packaging that used to be considered too limited for accessible design features. This convergence of two previously separate brand priorities, sustainability and accessibility, is opening genuinely new material innovation territory.
By End-User Demographic, seniors & elderly dominates the inclusive packaging market while individuals with disabilities grows fastest
Seniors & elderly account for 42% of end-user demographic demand, the largest single category, reflecting the sheer scale of the aging population combined with age-related conditions like arthritis that make conventional packaging genuinely difficult to use. Rising global life expectancy and aging population trends across major markets continue expanding this demographic's share of overall consumer spending and packaging design priority.
Individuals with disabilities is the fastest-growing end-user demographic, expanding at a 10.20% CAGR, as growing disability advocacy, workplace accessibility conferences, and brand recognition programs push companies to design specifically for this population rather than treating disability-friendly features as an incidental benefit of senior-focused design. Rising awareness that this demographic controls genuinely substantial disposable income is reinforcing brands' willingness to invest specifically in this population's needs.
Regional Analysis
|
Region |
Country |
Share within Region, 2025 (%) |
|
North America |
United States |
85.20% |
|
Asia Pacific |
China |
34.60% |
|
Europe |
Germany |
25.60% |
|
Middle East & Africa |
Saudi Arabia |
17.20% |
|
Latin America |
Brazil |
26.40% |
North America Inclusive Packaging Market Insights
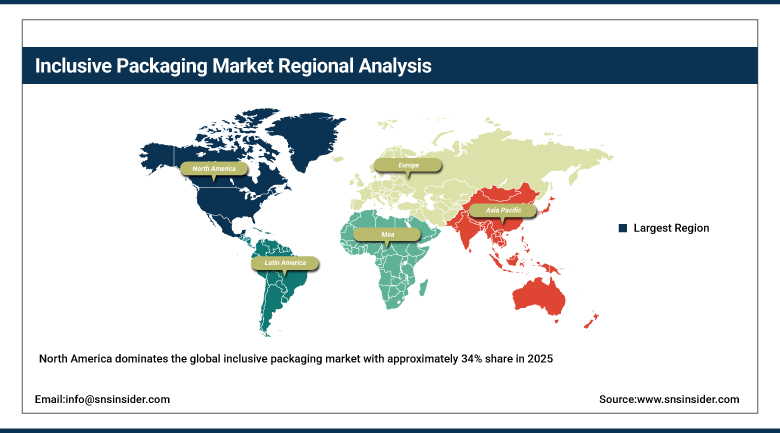
North America dominates the global inclusive packaging market with approximately 34% share in 2025, supported by the substantial disposable income controlled by people with disabilities in the United States, a well-established consumer goods manufacturing base, and leading brands actively competing on accessibility innovation. Growing brand recognition programs and award competitions for inclusive design continue reinforcing steady investment across the region's largest consumer goods companies.
The United States accounts for approximately 85.20% of the North American market, reflecting its concentration of major consumer goods manufacturers and advanced accessibility design research capability. Canada contributes a smaller but steady share, tied to its own consumer goods industry and comparable accessibility awareness trends.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Inclusive Packaging Market Insights
Europe's inclusive packaging market is mature and steady, shaped by comprehensive accessibility regulation, including the European Accessibility Act, that has pushed brands toward genuinely inclusive design well ahead of most other regions. Strong consumer expectation around product accessibility continues reinforcing steady demand even as growth in absolute terms remains more measured than in Asia Pacific.
Germany leads the European market with a 25.60% share, supported by its large consumer goods manufacturing base and strict accessibility compliance standards. France and the United Kingdom follow, with demand in both countries tied to comprehensive accessibility regulation and growing premium product positioning around inclusive design.
Asia Pacific Inclusive Packaging Market Insights
Asia Pacific is growing faster than any other region in this market, registering a CAGR of approximately 9.40% during 2026-2035, driven by growing urbanization and an aging population in economies like China, India, and Japan that is expanding demand for accessible product design well beyond the region's historical focus on younger, mainstream consumers. Rising middle-class disposable income across the region is also expanding the addressable market for premium, accessibility-focused packaged products.
China constitutes about 34.60% of the regional market due to the fast aging of its population along with the increasing manufacture of consumer products. The markets in India and South East Asia are witnessing rapid growth due to increasing awareness about accessibility, and the Japanese market because of their expertise in designing products for an aging population.
Middle East & Africa and Latin America Inclusive Packaging Market Insights
The Middle East & Africa region is growing steadily as modern retail infrastructure and consumer goods availability expand across the Gulf states, supported by rising disposable incomes and growing awareness of accessible product design. Latin America's growth follows a similar arc, driven by expanding consumer goods manufacturing in Brazil and growing regional awareness of inclusive design principles.
The UAE leads the Middle East & Africa market with a 17.20% share, supported by its role as a regional retail and consumer goods distribution hub. Brazil represents 26.40% of the Latin American market, reflecting its large consumer goods manufacturing base, with Mexico also contributing through its growing packaged goods sector.
Market Dynamics
Growth Drivers: Aging Population and Disability Spending Power Fueling Market Growth
The substantial disposable income controlled by people with disabilities and seniors, exceeding USD 1.2 trillion globally, is the clearest driver behind this market's growth, as brands increasingly recognize accessible packaging as a genuine business opportunity rather than a compliance cost. Rising global life expectancy and aging population trends across major markets are reinforcing this demand, since age-related conditions like arthritis make conventional packaging genuinely difficult for a growing share of consumers to use.
Growing brand competition on accessibility, reinforced by award recognition programs and industry conferences dedicated to inclusive design, is adding a meaningful additional demand line as companies increasingly view accessible packaging as a genuine differentiator rather than a niche accommodation.
Restraints: Design Complexity and Cost Premium Limiting Market Expansion
Developing genuinely accessible packaging requires meaningfully more design research and user testing than conventional packaging, since features like tactile symbols and ergonomic grips need direct input from people with the disabilities they are intended to serve. This added development complexity, along with tooling changes required for features like molded tactile elements, can translate into a cost premium that smaller brands find difficult to absorb without clear near-term sales justification.
Regulatory requirements and accessibility standards vary considerably across markets, creating genuine complexity for brands trying to sell standardized accessible packaging designs internationally without running into differing national requirements.
Opportunities: Open-Design Sharing and Sustainability Convergence Creating New Growth Avenues
Open, unpatented design sharing represents a genuine growth opportunity for the category as a whole, as leading brands choosing not to patent accessible packaging innovations accelerate industry-wide adoption and normalize accessibility as a baseline expectation rather than a competitive secret. Suppliers who can help smaller brands implement these shared designs stand to capture meaningful service revenue as adoption spreads.
Convergence between sustainability and accessibility goals offers a second clear opportunity, particularly as brands increasingly develop fiber-based packaging with embossed tactile elements and high-contrast printing that serves both priorities simultaneously rather than treating them as competing design considerations.
Recent Developments:
- 2025: Procter & Gamble's Tide brand received 'Best in Class' recognition for Inclusive Design at the PAC Global Awards for Tide evo, a tile-form laundry detergent activated instantly with water.
- 2025: Procter & Gamble adopted Domino Printing Sciences' D-Series technology to apply accessible tactile labelling across its shampoo and conditioner product lines.
- 2024: Procter & Gamble launched its first IT Accessibility Hub at its Geneva Business Center, extending its Universal Design principles from packaging into broader workplace and product accessibility initiatives.
- 2025: Procter & Gamble participated in the 2025 Disability:IN Conference, continuing to expand its Braille labeling, tactile symbols, and high-contrast packaging design across its global brand portfolio.
Inclusive Packaging Market key players are:
- Amcor plc
- Sealed Air Corporation
- Mondi Group
- Tetra Pak International S.A.
- AptarGroup, Inc.
- CCL Industries Inc.
- Avery Dennison Corporation
- Colgate-Palmolive Company
- Procter & Gamble Company
- Kimberly-Clark Corporation
- Unilever PLC
- L'Oréal S.A.
- The Estée Lauder Companies Inc.
- Reckitt Benckiser Group plc
- GSK plc
- Pfizer Inc.
- Johnson & Johnson
- Sonoco Products Company
- Berlin Packaging LLC
- Diageo plc
Inclusive Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.85 Billion |
| Market Size by 2035 | USD 8.20 Billion |
| CAGR | CAGR of 7.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Feature Type (Easy-Open Closures, Tactile & Braille Labeling, Ergonomic Grip Design, High-Contrast Visual Labeling, Resealable & Single-Hand Opening Systems, Others) • By End-Use Industry (Pharmaceuticals, Food & Beverage, Personal Care & Cosmetics, Household Products, Others) • By Material (Plastic, Metal, Glass, Paper & Paperboard, Others) • By End-User Demographic (Seniors & Elderly, Individuals with Disabilities, General Consumers, Caregivers & Assisted Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Sealed Air Corporation, Mondi Group, Tetra Pak International S.A., AptarGroup, Inc., CCL Industries Inc., Avery Dennison Corporation, Colgate-Palmolive Company, Procter & Gamble Company, Kimberly-Clark Corporation, Unilever PLC, L'Oréal S.A., The Estée Lauder Companies Inc., Reckitt Benckiser Group plc, GSK plc, Pfizer Inc., Johnson & Johnson, Sonoco Products Company, Berlin Packaging LLC, Diageo plc |
Frequently Asked Questions
Key players include Procter & Gamble Company, Colgate-Palmolive Company, Unilever PLC, L'Oréal S.A., and Amcor plc, alongside other established consumer goods and packaging manufacturers.
Key opportunities include open, unpatented design sharing accelerating industry-wide accessibility adoption, convergence between sustainability and accessibility goals in fiber-based packaging into mainstream categories.
The market is driven by the substantial disposable income controlled by people with disabilities and seniors, rising global life expectancy and aging population trends, and growing brand competition on accessibility.
The Easy-Open Closures segment dominated the Inclusive Packaging Market in 2025.
The North America region dominated the Inclusive Packaging Market in 2025.
