
Industrial and Institutional Cleaning Chemicals Market Report Scope & Overview:
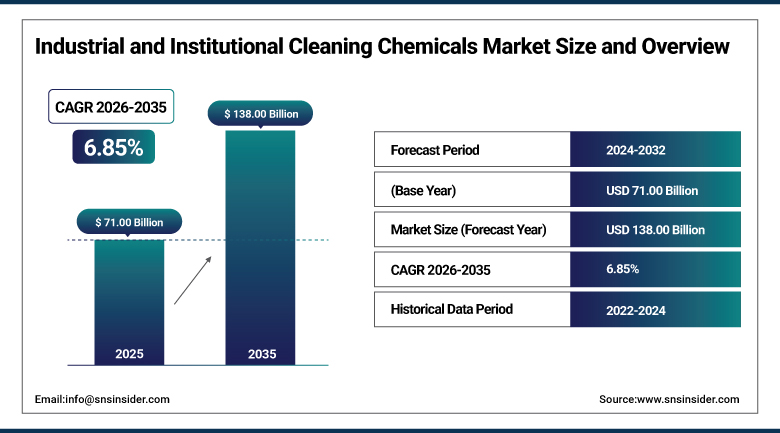
The Industrial and Institutional Cleaning Chemicals Market was valued at USD 71.00 Billion in 2025 and is expected to reach USD 138.00 Billion by 2035, growing at a CAGR of 6.85% from 2026–2035.
Industrial and institutional cleaning chemicals are the specialized formulations, disinfectants, degreasers, laundry detergents, general purpose cleaners, that keep hospitals, food plants, offices, and factories sanitary at a scale far beyond what household cleaning products were ever designed to handle. Hospitals can't risk a surface disinfectant that doesn't reliably kill pathogens, and a food processing plant can't risk a degreaser that leaves residue behind, which is why this category runs on rigorous formulation science and regulatory compliance rather than the marketing-driven differentiation that dominates consumer cleaning products. Stricter hygiene regulations, amplifying awareness of workplace cleanliness, and stringent infection control requirements across healthcare have all been pushing demand steadily upward across nearly every end-use sector.
Diversey, now operating under Solenis, launched its IntelliDish CONTROL system in late 2025, an IoT-connected dishwashing platform that uses sensors to automatically optimize detergent usage and water flow in large commercial dishwashers. That kind of automated dosing matters more than it might sound, since overusing cleaning chemical concentrate is one of the most common and avoidable cost leaks in industrial and institutional kitchens, and a sensor that adjusts dosing in real time can cut chemical waste in ways a human following a fixed recipe never quite manages.
To Get more information Industrial and Institutional Cleaning Chemicals Market - Request Free Sample Report
Industrial and Institutional Cleaning Chemicals Market Trends
-
Low-toxicity, eco-friendly formulations continue gaining share as organizations aim to reduce environmental impact while maintaining high cleaning efficacy, particularly across commercial building management and facility services.
-
Low-VOC, green solvent formulations continue advancing as manufacturers work to comply with tightening environmental regulations without sacrificing degreasing and stain-removal performance across industrial applications.
-
IoT-connected dosing and dishwashing systems continue expanding across commercial kitchens and institutional facilities, letting operators optimize chemical usage and water flow through real-time sensor data.
-
Consolidation and specialty chemical acquisitions continue reshaping the competitive landscape, as larger players seek deeper R&D capability in water treatment, hygiene, and sustainability technologies.
-
Proprietary dilution systems installed directly within commercial plumbing infrastructure continue creating high switching barriers, extending contract durations across industrial and institutional supply agreements.
U.S. Industrial and Institutional Cleaning Chemicals Market Outlook
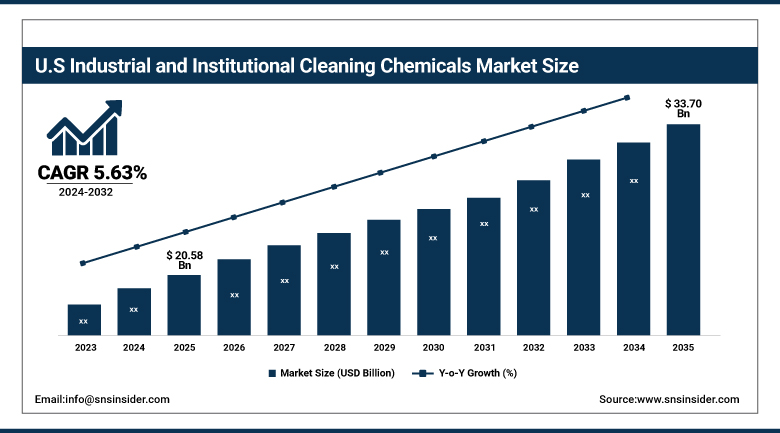
The U.S. Industrial and Institutional Cleaning Chemicals Market was valued at approximately USD 20.58 Billion in 2025 and is expected to reach approximately USD 33.70 Billion by 2035, growing at a CAGR of approximately 5.63%.
Demand in the United States is anchored by growth in the healthcare sector, enhancements in food safety standards, and heightened awareness surrounding workplace hygiene across commercial, institutional, and manufacturing facilities. A concentration of the world's largest cleaning chemical manufacturers, including several long-established American specialty chemical companies, continues anchoring domestic research and production capacity. Growing outsourcing of commercial cleaning to specialized contract providers continues reshaping how cleaning chemicals reach end users, favoring manufacturers with strong enterprise account and dilution-system service capability over smaller regional suppliers.
Solenis, the U.S. specialty chemicals company that acquired Diversey in 2023, opened a new Global Research Center in Wilmington, Delaware in late 2025, aimed at developing next-generation chemistries including biodegradable polymers, specialty enzymes, and advanced coagulants alongside smart system controls. The company says more than 75% of its R&D budget now focuses specifically on water, hygiene, and sustainability technologies, a concentration of research spending that reflects how much competitive advantage in this industry now comes from chemistry innovation rather than simply undercutting rivals on price.
Industrial and Institutional Cleaning Chemicals Market Segment Analysis
-
By Raw Material, the Surfactants segment dominated the Industrial and Institutional Cleaning Chemicals Market with approximately 36.20% share in 2025, while the Solvents segment is the fastest growing with a CAGR of approximately 8.30%.
-
By Product, the General Purpose Cleaners segment dominated the Industrial and Institutional Cleaning Chemicals Market with approximately 36.00% share in 2025, while the Disinfectants & Sanitizers segment is the fastest growing with a CAGR of approximately 8.20%.
-
By End-Use, the Commercial segment dominated the Industrial and Institutional Cleaning Chemicals Market with approximately 67.80% share in 2025, while the Manufacturing/Industrial segment is the fastest growing with a CAGR of approximately 8.60%.
By Raw Material, surfactants dominates, solvents grows fastest
Surfactants had the largest market share within the raw-materials segment in 2025 because surfactants serve as the main active component in most cleanser formulations based on their multi-purposed capabilities in cleaning. Because of their function in reducing the surface tension and in the emulsification of oil, surfactants remain the key raw material that the entire cleaning chemicals industry depends on.
On the other hand, solvents are experiencing the highest growth rate based on the increasing demand for specialty cleaners for tough greases and low-VOC green solvents. In addition to this, the shift to solvents driven by environmental regulation requirements and by the performance enhancements made by new solvent technologies keeps propelling the growth of the solvents raw material category ahead of the total material market.
By Product, general purpose cleaners dominates, disinfectants & sanitizers grows fastest
General purpose cleaners accounted for the largest market share in the product type segment in 2025 due to their high flexibility of usage in commercial buildings, schools, office spaces, healthcare facilities, and industrial facilities. The usage of these products is associated with their ability to remove various kinds of dirt, dust, and stain marks from different surfaces; therefore, they are highly demanded due to increasing concerns regarding clean workplace environments and strict facility management rules.
Disinfectants and sanitizers experienced the highest growth rate due to increased concerns of consumers regarding health and hygiene and strict infection control policies implemented in the healthcare industry as well as strict food safety requirements in the food and beverages processing industry. This factor is likely to have a positive impact on the growth rates of this segment going forward.
By End-Use, commercial dominates, manufacturing/industrial grows fastest
Commercial end-use dominated the end-use sector in 2025 due to the stringent cleaning measures, rising health and safety concerns, and increasing focus on creating hygienic and welcoming surroundings for employees as well as visitors. The increase in commercial building and facility management services around the globe has been contributing significantly to the demand for the products, with businesses ensuring that their premises are hygienic enough to not only safeguard occupants but also protect business reputation, making commercial end-use the dominant end-use category that is continuously expanding its market base.
The manufacturing and industrial end-use segment remains the fastest-growing end-use application in the cleaning chemicals industry owing to the adoption of stringent cleaning protocols by manufacturers due to rising compliance issues and increasing focus on maintaining safety standards within workplaces. Sustainability practices have been influencing manufacturers as end-users of cleaning products to use environmentally friendly cleaning agents.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.40% |
|
Europe |
Germany |
25.60% |
|
Asia Pacific |
China |
39.20% |
|
Latin America |
Brazil |
35.80% |
|
Middle East & Africa |
UAE |
30.40% |
North America Industrial and Institutional Cleaning Chemicals Market Insights
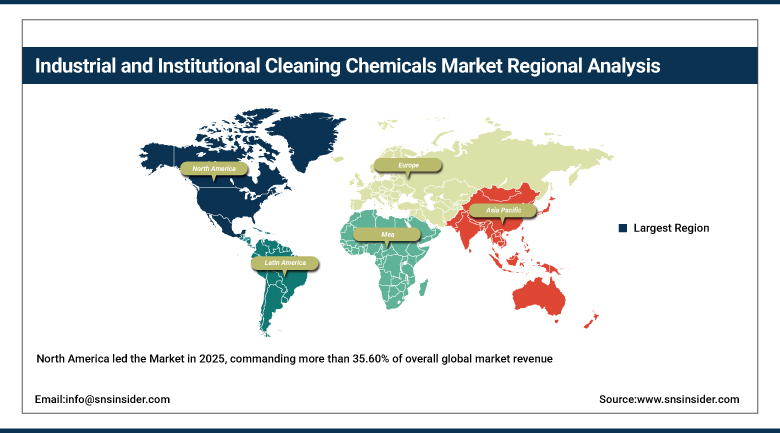
North America led the Industrial and Institutional Cleaning Chemicals Market in 2025, commanding more than 35.60% of overall global market revenue, anchored by the United States' large healthcare sector, stringent food safety standards, and deep concentration of the world's largest specialty cleaning chemical manufacturers. Established enterprise service relationships between major manufacturers and commercial facility customers, often backed by proprietary dilution systems installed directly within customer plumbing infrastructure, continue reinforcing this leading position across the broader region.
Canada contributes a meaningful share through its own healthcare and commercial facility management sector, while Mexico's market continues expanding alongside growing manufacturing and industrial investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production and distribution networks.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Industrial and Institutional Cleaning Chemicals Market Insights
The Asia Pacific region is projected to witness the highest regional growth rate up to 2035, due to rapid urbanization and industrialization, improving healthcare infrastructure, and increased food safety regulations in the largest and rapidly growing economies in the region. With increasing innovations in nanotechnology and functionalization along with increasing manufacturing capabilities in the region, the growth trajectory of the market has been further strengthened.
China's huge manufacturing and healthcare infrastructure provides the region with an initial demand base, whereas the organized retail, healthcare, and hospitality segments in India have attracted investments in cleaning chemical manufacturing. Japan and South Korea are technologically advanced markets having well-established hygiene standards, while markets in Southeast Asia are growing on the same trajectory as a result of urbanization.
Europe Industrial and Institutional Cleaning Chemicals Market Insights
Europe represents a mature, regulation-conscious industrial and institutional cleaning chemicals market, shaped by comprehensive environmental regulation pushing manufacturers toward low-VOC, biodegradable, and green-certified formulations across nearly every product category. Germany anchors regional demand, home to a large healthcare and manufacturing base and several major cleaning chemical companies with deep formulation science expertise.
France, Italy, and the United Kingdom contribute meaningful volume as well, each with substantial commercial and institutional facility management sectors adapting to tightening EU sustainability requirements. Growing regional emphasis on eco-friendly, low-toxicity formulations continues shaping product development across the region more directly than in most other global markets.
MEA & Latin America Industrial and Institutional Cleaning Chemicals Market Insights
The Middle East and Africa represent a smaller but strategically developing industrial and institutional cleaning chemicals market, with the UAE driving demand through growing healthcare, hospitality, and commercial facility investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader healthcare and commercial infrastructure development across neighboring markets.
Latin America is a growing market led by Brazil, where expanding healthcare infrastructure and food processing manufacturing continue driving demand for industrial and institutional cleaning chemicals. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing manufacturing and commercial facility management sectors.
Growth Drivers: Healthcare sector growth and workplace hygiene awareness fueling adoption
Growth in the healthcare sector is one of the clearest forces behind rising industrial and institutional cleaning chemicals demand, as expanding hospital and clinic infrastructure worldwide continues requiring rigorous infection control and disinfection protocols that depend directly on specialized cleaning chemical formulations. That healthcare-driven demand base gives the market a foundation that holds up reliably regardless of broader economic conditions, since infection control requirements aren't optional in regulated healthcare settings.
Enhancements in food safety standards add a second major driver, as stricter regulatory requirements across food processing and food service continue expanding demand for degreasers, sanitizers, and specialized cleaning formulations that meet increasingly rigorous compliance standards. Increased levels of urbanization and industrialization, combined with the outsourcing trend in cleaning services, continue reinforcing this demand base across commercial and institutional facility categories worldwide.
Restraints: Raw material price volatility and regulatory compliance costs limiting margin stability
Fluctuating surfactant and solvent prices add real cost unpredictability for manufacturers, since cleaning chemical producers remain exposed to broader petrochemical commodity market swings that directly affect production costs and, ultimately, project budgets for commercial and institutional customers. Manufacturers without long-term raw material supply contracts are particularly exposed to these swings, which can compress margins even when finished-product demand remains steady.
Tightening regulatory compliance requirements around chemical safety and environmental impact add a further restraint, as manufacturers face genuine reformulation costs navigating varying VOC and toxicity mandates across different jurisdictions simultaneously. That compliance burden falls disproportionately on smaller manufacturers without dedicated regulatory affairs and R&D capability built into their operations.
Opportunities: Green formulation innovation and smart dosing technology opening new growth avenues
Green formulation innovation offers manufacturers a genuine path to capturing premium business from commercial and institutional customers chasing credible sustainability commitments ahead of tightening environmental regulation across major markets. Companies that successfully develop low-VOC, biodegradable formulations matching conventional performance are positioned to capture significant new business as regulatory and customer pressure on conventional formulations continues building.
Smart dosing and IoT-connected dispensing technology represents a second significant opportunity, as commercial kitchens and institutional facilities increasingly value sensor-based systems that optimize chemical usage and reduce waste beyond what manual dosing ever achieved. Companies that build genuine smart dispensing capability are positioned to capture premium pricing from customers seeking both cost efficiency and sustainability credentials simultaneously.
Recent Developments
-
2025: Diversey, under Solenis, was named “Best Sustainability-Focused Chemicals Company” in Southeast Asia, reflecting its continued investment in eco-chemistry and waste reduction.
-
May 2025: EarthSafe Chemical Alternatives introduced its ECO+ cleaning line, a range of Green Seal-certified products tailored for high-traffic environments such as healthcare, education, and hospitality facilities.
-
2025: Ecolab and Diversey continued securing enterprise agreements by installing proprietary dilution systems within commercial plumbing infrastructure, extending contract durations across industrial and institutional supply agreements.
-
2025: Multiple major manufacturers, including Ecolab and BASF, continued expanding low-VOC, green solvent product lines to comply with evolving environmental regulations.
Industrial and Institutional Cleaning Chemicals Companies are:
-
Procter & Gamble Co.
-
BASF SE
-
Henkel AG & Co. KGaA
-
Reckitt Benckiser Group plc
-
Croda International Plc
-
3M Company
-
Diversey Holdings, Ltd. (Solenis)
-
Church & Dwight Co., Inc.
-
Betco Corporation
-
Buckeye International, Inc.
-
Arrow-Magnolia International, Inc.
-
Avmor Ltd.
-
SC Johnson Professional
-
Spartan Chemical Company, Inc.
-
The Clorox Company
-
Kao Corporation
-
Stepan Company
-
Solvay S.A.
Industrial and Institutional Cleaning Chemicals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 71.00 Billion |
| Market Size by 2035 | USD 138.00 Billion |
| CAGR | CAGR of 6.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Raw Material (Surfactants, Solvents, Chelating Agents, pH Regulators, Solubilizers/Hydrotropes, Enzymes, Others) • by Product (General Purpose Cleaners, Disinfectants & Sanitizers, Laundry Care Products, Vehicle Wash Products, Others) • by End-Use (Commercial, Industrial/Manufacturing, Institutional, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Procter & Gamble Co., BASF SE, Henkel AG & Co. KGaA, Reckitt Benckiser Group plc, Croda International Plc, 3M Company, Ecolab Inc., Diversey Holdings, Ltd. (Solenis), Church & Dwight Co., Inc., Betco Corporation, Buckeye International, Inc., Arrow-Magnolia International, Inc., Avmor Ltd., SC Johnson Professional, Spartan Chemical Company, Inc., Zep Inc., The Clorox Company, Kao Corporation, Stepan Company, Solvay S.A. |
Frequently Asked Questions
Key players in the Industrial and Institutional Cleaning Chemicals Market include Procter & Gamble Co., BASF SE, Henkel AG & Co. KGaA, Ecolab Inc., and Diversey Holdings, Ltd., among others.
Key opportunities in the Industrial and Institutional Cleaning Chemicals Market include green formulation innovation for credible sustainability commitments and smart, IoT-connected dosing technology reducing chemical waste.
The market is driven by growth in the healthcare sector requiring rigorous infection control, combined with enhancements in food safety standards across food processing and food service.
The General Purpose Cleaners segment dominated the Industrial and Institutional Cleaning Chemicals Market, accounting for approximately 36.00% market share.
The North America region dominated the Industrial and Institutional Cleaning Chemicals Market in 2025 with more than 35.60% share, driven by the United States' large healthcare sector and stringent food safety standards.
