
Internet of Robotic Things Market Report Scope & Overview:
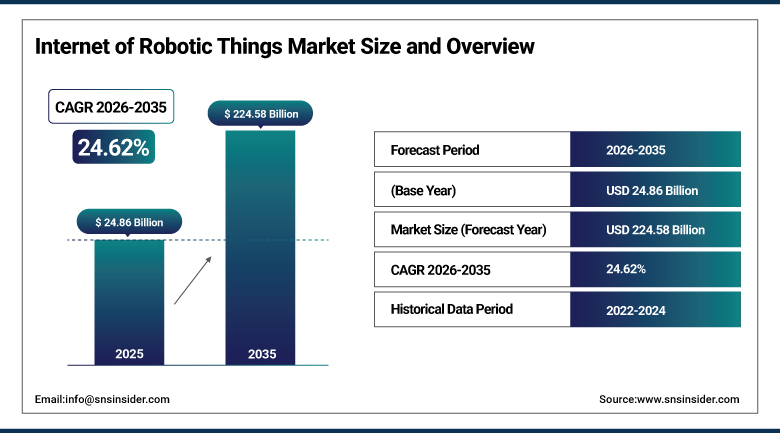
The Internet of Robotic Things Market was valued at USD 24.86 Billion in 2025 and is expected to reach USD 224.58 Billion by 2035, growing at a CAGR of 24.62% from 2026-2035.
The Internet of Robotic Things Market covers robots that are connected to sensors, cloud platforms, edge computing and one another so they can share data, learn from fleets and be managed remotely. It combines robotics, the Internet of Things and artificial intelligence in factories, warehouses, hospitals, farms and public places. Growth is supported by automation needs, labor shortages, 5G and edge computing, and advances in AI, while cybersecurity risk, interoperability gaps and high deployment cost shape adoption.
⮞Ownership of a leading robot maker is changing. On October 8, 2025, SoftBank Group signed a definitive agreement to acquire ABB's robotics business, which has about 7,000 employees and reported pro forma revenue of USD 2.28 billion in fiscal 2024, for USD 5.38 billion. Closing was expected in mid-to-late 2026, subject to approvals in the European Union, China and the United States.
To Get more information Internet of Robotic Things Market - Request Free Sample Report
Internet of Robotic Things Market Trends
- Fleet-wide AI models that coordinate many robots in warehouses and factories
- Edge computing and private 5G that cut response time for robot control
- Collaborative robots and humanoids working alongside people
- Digital twins used to test robot tasks before deployment
- Remote monitoring and predictive maintenance for robot fleets
- Cybersecurity and open standards for connected robot systems
U.S. Internet of Robotic Things Market Outlook
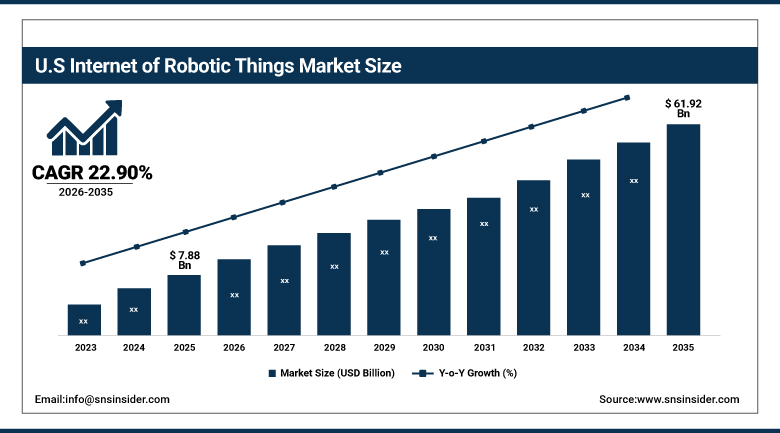
The U.S. Internet of Robotic Things Market was valued at USD 7.88 Billion in 2025 and is expected to reach USD 61.92 Billion by 2035, growing at a CAGR of 22.90% from 2026-2035.
The U.S. Internet of Robotic Things Market is the largest national market in the region, supported by large e-commerce and logistics operators, advanced manufacturing, strong cloud and AI providers and heavy investment in robotics start-ups. Warehouses, hospitals and factories are connecting robots to cloud tools. Growth is moderated by high integration costs, labor skill gaps and cybersecurity concerns.
⮞Warehouse robot fleets are being managed by AI. On July 1, 2025, Amazon announced that it had deployed its one millionth robot, delivered to a fulfillment facility in Japan, and introduced DeepFleet, a generative AI model that coordinates robot routes inside warehouses. Amazon said DeepFleet would increase the speed of its robotic fleet by 10%.
Internet of Robotic Things Market Segment Analysis
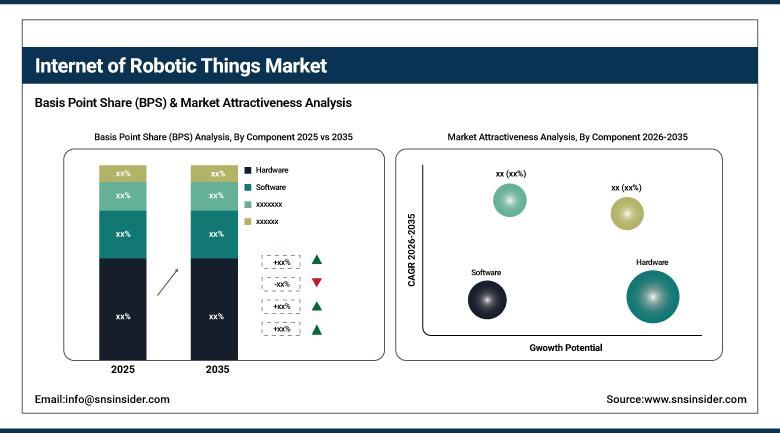
- By Component, hardware segment dominated the Internet of Robotic Things Market in 2025 with an estimated 52.00% share; software segment is the fastest-growing segment, with an estimated CAGR of 29.50% during 2026–2035.
- By Robot Type, industrial robots segment dominated the Internet of Robotic Things Market in 2025 with an estimated 47.00% share; service robots segment is the fastest-growing segment, with an estimated CAGR of 28.00% during 2026–2035.
- By Connectivity Technology, Wi-Fi segment dominated the Internet of Robotic Things Market in 2025 with an estimated 47.00% share; 5G/Cellular segment is the fastest-growing segment, with an estimated CAGR of 28.00% during 2026–2035.
- By Application, manufacturing segment dominated the Internet of Robotic Things Market in 2025 with an estimated 38.00% share; logistics and warehousing segment is the fastest-growing segment, with an estimated CAGR of 29.50% during 2026–2035.
By Component, Hardware Dominates Internet of Robotic Things Market; Software to Register Fastest Growth.
Hardware dominates the Internet of Robotic Things Market because every connected robot needs sensors, controllers, actuators, communication modules and power systems, and these physical parts make up most of the cost of a deployment. Large fleets of robots in factories and warehouses require many units, and sensors and control systems are also added to existing robots to connect them. Falling sensor and chip prices, along with better batteries and communication modules, are widening the range of tasks that robots can perform, and replacement cycles for older components add steady hardware demand across factories and warehouses. Service contracts for spare parts also bring recurring income to hardware suppliers.
Software is projected to register the fastest growth as fleet management, remote monitoring, digital twin and AI platforms become the way users coordinate and improve robot performance. Subscription pricing and cloud delivery allow software revenue to grow with each robot added. Vendors are releasing models trained on fleet data to optimize routes and tasks. Open application interfaces and app-store models allow third-party developers to build tools for vision, navigation and analytics, which increases the value of each deployed robot and encourages users to keep paying for updates.
By Robot Type, Industrial Robots Dominates Internet of Robotic Things Market; Service Robots to Register Fastest Growth.
Industrial robots dominate the Internet of Robotic Things Market because factories already operate large installed fleets of arms and automated vehicles, and connecting them to networks for monitoring, quality control and maintenance delivers clear returns. Automotive, electronics and metal plants lead adoption, with strong demand for predictive maintenance and traceable production data. Retrofit kits that add sensors and gateways to older arms let plants join connected networks without replacing machines, which spreads adoption beyond new lines. Safety standards for collaborative operation also support growth.
Service robots are projected to register the fastest growth as hospitals, hotels, retailers and logistics providers use connected delivery, cleaning, inspection and assistance robots. Cloud connectivity lets these robots update maps, share tasks and be supervised remotely. Falling hardware costs and labor shortages are encouraging wider use outside factories. Suppliers are offering robots that can be rented by the hour or by task, which makes adoption easier for small firms. Humanoid and mobile manipulator pilots in logistics and care are widening the range of applications. Pilot projects in hotels and hospitals are growing from single units to multi-site deployments.
By Connectivity Technology, Wi-Fi Dominates Internet of Robotic Things Market; 5G/Cellular to Register Fastest Growth.
Wi-Fi is the technology that dominated the Internet of Robotic Things Market in 2025. This domination is due to a number of reasons, including the presence of wireless network infrastructure, affordable implementation, large bandwidth for data transfer, and the ability to work together with robotic systems functioning in manufacturing units, warehousing, hospitals, and business settings. The Wi-Fi technology allows robots to communicate sensor data and operational data and collaborate with the help of the central platform.
The 5G/cellular segment is expected to register the highest growth rate in the forecast period. This would be because of the rising need for low-latency communications and connectivity, as well as for real-time coordination of autonomous robots. The 5G technology can help achieve this along with its other capabilities such as fast data exchange, robotic control, mobile robotics, and automation. Expanding private 5G networks and investments in smart manufacturing, logistics automation, and intelligent infrastructure are expected to accelerate segment growth.
By Application, Manufacturing Dominates Internet of Robotic Things Market; Logistics and Warehousing to Register Fastest Growth.
Manufacturing dominates the Internet of Robotic Things Market because factories have the largest base of robots and the strongest case for connecting them to improve uptime, quality and flexibility. Plants link robots to manufacturing systems and digital twins, allowing production lines to be reconfigured quickly. Smart factory investments in Asia, Europe and North America sustain demand. Quality inspection with connected vision systems, welding, assembly and material handling are the most common tasks, and data from robots feeds analytics that reduce scrap. Automotive and electronics makers remain the biggest buyers.
Logistics and warehousing is projected to register the fastest growth as e-commerce volumes, labor shortages and demand for faster delivery lead operators to deploy large fleets of mobile robots, picking arms and sorting systems. Fleet-wide AI and cloud coordination raise throughput, and operators are adding more robots as software improves. Large operators run thousands of robots per site and use fleet software to balance workloads and reduce congestion. Third-party logistics providers are adopting robots as a service, which lets them scale for peak seasons without heavy capital spending.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
88.00 |
|
Asia Pacific |
China |
46.00 |
|
Europe |
Germany |
28.00 |
|
MEA & Latin America |
Brazil |
24.00 |
North America Internet of Robotic Things Market Insights
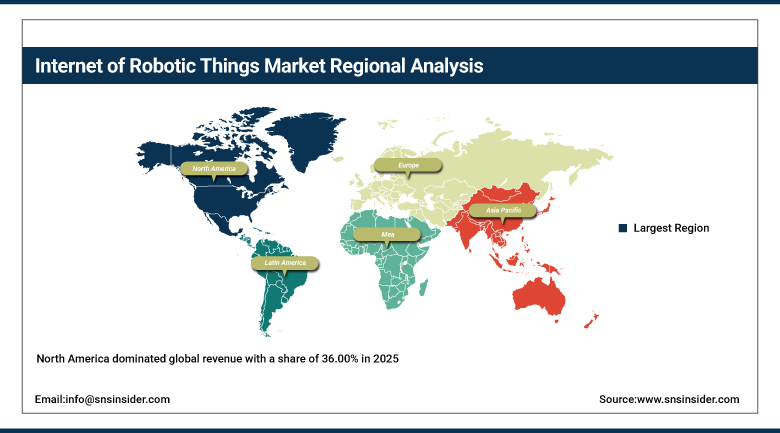
North America dominated global revenue with a share of 36.00% in 2025. The United States accounts for majority of the regional demand, with Canada and Mexico adding volume. Amazon, Intel, NVIDIA, Cisco, Rockwell Automation, Northrop Grumman, Boston Dynamics and iRobot serve the region. Hyperscale cloud providers offer robotics platforms and simulation tools, and US universities and start-ups feed a steady pipeline of new products. Retailers and parcel carriers are among the largest buyers of connected robots in the region.
Large logistics operators, cloud platform providers, advanced manufacturers and defense programs support demand, and venture funding for robotics is strong. Companies pair robots with edge AI and private networks. High integration cost, shortages of skilled technicians, cybersecurity concerns and regulation of autonomous systems moderate growth. Government programs for advanced manufacturing and reshoring, along with defense research, support deployment. Standards bodies and industry groups are working on safety and security guidelines to make multi-vendor systems easier to run. Co-operation between utilities and carriers is also building private wireless networks for large industrial sites.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Internet of Robotic Things Market Insights
Asia Pacific is the second-largest region and is projected to be the fastest-growing region, at a CAGR of 27.30% during 2026-2035. China, Japan, South Korea, India and Singapore lead regional demand. FANUC, Yaskawa, Samsung, Hyundai, UBTech, DJI and Omron serve the region. China accounts for about majority of the regional demand. Chinese manufacturers are rapidly expanding production of both industrial and service robots, and local cloud and AI companies offer platforms tailored to factories and cities. Japan and South Korea export robots and components worldwide. Local suppliers are also lowering prices for sensors and controllers, which helps smaller factories adopt connected robots.
The region has the world's largest industrial robot base, strong electronics manufacturing and government plans for smart factories and 5G. Japan and South Korea lead in robot technology, while China is scaling service and humanoid robots. India is adding robots as manufacturing expands. Uneven standards, trade restrictions and skill shortages moderate growth. National plans for 5G, industrial internet and robot density are encouraging factories to connect their machines, and electric vehicle and battery plants are adding large automated lines. Regional supply chains for sensors and motors are deepening.
Europe Internet of Robotic Things Market Insights
Europe is the third-largest region. Germany, France, Italy, the United Kingdom and the Nordic countries lead regional demand. Siemens, ABB, KUKA, Bosch, Schneider Electric, Neura Robotics and Blue Ocean Robotics serve the region. Germany anchors the region through its machinery and automotive sectors, while the Nordic countries lead in service robots and the United Kingdom in robotics research. Cross-border projects supported by European funding spread new tools. Public research institutes in Germany and France also work with firms on safe human-robot cooperation.
Strong automotive and machinery industries, Industry 4.0 programs and research support demand for connected robots. Rules on data, safety and artificial intelligence shape product design. The higher energy cost as well as less investment in certain industries keeps the pace of growth lower, although labor shortage and digital twin technology stimulate adoption. The new European AI Act and the guidelines for handling data are influencing the development and use of connected robots, which is advantageous for the providers who comply with those regulations.
⮞On April 19, 2026, press reports from Hannover Messe described Siemens showing an AI-ready industrial automation data center built with NVIDIA and Palo Alto Networks, and a humanoid robot running logistics tasks autonomously at its Erlangen electronics plant using NVIDIA's physical AI stack.
MEA & Latin America Internet of Robotic Things Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina and Chile, with regional demand growing at steady pace annually. Automotive plants, logistics centers and mining operations are early adopters, and cloud services are lowering entry costs. Currency swings and limited local integrators moderate growth. Mining, agriculture and automotive plants in Brazil and Mexico are testing connected robots, and distributors help foreign vendors reach midsize firms. Cloud-based services reduce the need for large local investment. Mining operators also use connected inspection robots in remote sites.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Israel and South Africa lead demand, with stronger growth annually. Inspection and logistics robots are being used for national smart cities and industries programs, ports, airports and energy plants, but lack of skills and infrastructure is holding back many African countries. The gulf nations are financing smart city, port and logistics robot projects including delivery and inspection robots, while Israel provides robotics and cyber security technologies. Collaboration with international vendors and training programs are helping to build up skills locally.
Market Dynamics
Growth Drivers: Automation Needs, Labor Shortages and AI at the Edge
Labor shortages and rising wages push factories, warehouses and hospitals to automate tasks with connected robots. Aging populations in Japan, Europe and China reduce the available workforce, and companies see connected robots as a way to keep output steady while improving safety. Rising demand for same-day delivery and personalized production increases the need for flexible automation that can be changed through software updates rather than new hardware. Growth in e-commerce and omnichannel retail is pushing fulfillment centers to automate picking, packing and sorting, and each new site tends to add hundreds of connected robots managed by shared software.
Advances in AI, 5G and edge computing allow robots to share data, learn from fleets and respond faster, raising their value. Government subsidies for smart factories and digital transformation also lower the cost of pilot projects and speed up adoption. Falling cost of cloud storage and AI training makes it easier for vendors to collect fleet data and improve their models for customers. Healthcare providers are also adopting disinfection, delivery and telepresence robots, and connected tracking helps hospitals manage staff and supply flows more efficiently. Defense, border and public safety agencies are testing connected ground and aerial robots, which adds specialized demand for secure communication and sensing.
Restraints: Cybersecurity, Interoperability and Cost
Connected robots create new attack surfaces, and a breach can stop production or put people at risk. Many firms still run mixed fleets from several vendors, and the lack of common data formats makes it hard to manage them on one platform. Concerns about job losses and worker acceptance can slow adoption in some countries, and safety rules for robots working near people add certification time. Data privacy rules and customer worries about sharing production data with cloud vendors can delay projects, and some firms insist on on-site processing that adds hardware cost.
There are no common standards between the vendors, and high costs of integration hamper adoption, especially in small and medium enterprises. Integration experts and robot mechanics are hard to come by, and that may further slow down implementation and increase maintenance costs. Unreliable network and latency issues in large buildings will prevent real-time control unless there is private 5G or edge computing. Technological advancements are quite fast, which means robots may become obsolete in just a few years' time. This may deter certain customers from making long-term investments. There might be supply issues with advanced chips and rare-earth magnets used in robots, thus increasing their costs.
Opportunities: Robots-as-a-Service, Digital Twins and Emerging Markets
Subscription models lower upfront cost and allow smaller firms to try connected robots. Insurance products, financing and robot rental programs can reduce the barriers to entry and widen the customer base beyond large firms. Partnerships between robot makers, telecom operators and cloud providers can create bundled offerings that include connectivity, security and support. Edge AI chips and private networks give vendors a chance to sell integrated packages that combine compute, connectivity and software, and these packages can be priced by outcome rather than by unit. Training and certification programs for robot operators can create new service revenue for vendors and colleges.
Digital twins, fleet AI and expanding manufacturing in India, Southeast Asia and the Middle East open new customers and use cases. Applications in agriculture, construction, energy inspection and elder care are still early and offer room for new platforms and services. Growth of humanoid and general-purpose robots creates new demand for sensors, compute and fleet software from specialist suppliers. Public funding for robotics research, test beds and workforce training in several countries reduces risk for early adopters and helps create skilled local labor for installation and support.
Recent Developments:
- 2026: iRobot Corporation published Roomba 100/1000 Series software release notes covering stability improvements and support for Wi-Fi network credentials using additional character sets.
- 2026: Samsung Electronics Co., Ltd. announced a strategy to transition global manufacturing operations into AI-driven factories by 2030, using digital twins and AI agents for production, quality, logistics, and safety.
- 2026: Yaskawa Electric Corporation developed an agentic robot system combining its MOTOMAN NEXT robot with Google DeepMind’s Gemini Robotics ER model to interpret conditions, plan work procedures, and execute tasks autonomously.
Internet of Robotic Things Market Key Players
- ABB Ltd.
- FANUC Corporation
- KUKA AG
- Siemens AG
- Amazon.com, Inc.
- Intel Corporation
- NVIDIA Corporation
- Cisco Systems, Inc.
- Yaskawa Electric Corporation
- Robert Bosch GmbH
- Rockwell Automation, Inc.
- Northrop Grumman Corporation
- iRobot Corporation
- Samsung Electronics Co., Ltd.
- Omron Corporation
- Microsoft Corporation
- PTC Inc.
- Blue Ocean Robotics
- Aethon Inc.
- Bluefin Robotics
Internet of Robotic Things Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 24.86 Billion |
| Market Size by 2035 | USD 224.58 Billion |
| CAGR | CAGR of 24.62% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Hardware, Software, Services) • By Robot Type (Industrial Robots, Service Robots, Autonomous Mobile Robots, Others) • By Connectivity Technology (Wi-Fi, 5G/Cellular, Bluetooth, LPWAN, Industrial Ethernet, Others) • By Application (Manufacturing, Logistics and Warehousing, Healthcare, Construction, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ABB Ltd., FANUC Corporation, KUKA AG, Siemens AG, Amazon.com, Inc., Intel Corporation, NVIDIA Corporation, Cisco Systems, Inc., Yaskawa Electric Corporation, Robert Bosch GmbH, Rockwell Automation, Inc., Northrop Grumman Corporation, iRobot Corporation, Samsung Electronics Co., Ltd., Omron Corporation, Microsoft Corporation, PTC Inc., Blue Ocean Robotics, Aethon Inc., Bluefin Robotics |

Frequently Asked Questions
Key players include ABB Ltd., FANUC Corporation, KUKA AG, Siemens AG, Amazon.com, Inc., Intel Corporation, NVIDIA Corporation and Cisco Systems, Inc.
Key opportunities include robots-as-a-service models, digital twins and growing manufacturing in emerging markets.
The major growth factor is labor shortages and the need for automation, supported by advances in AI, 5G and edge computing.
By Component, the Hardware segment dominated the market in 2025 with an estimated 52.00% share, as every connected robot needs sensors, controllers and actuators.
North America dominated the market with a share of 36.00% in 2025, driven by logistics operators, cloud providers and advanced manufacturers.
