
Synthetic Media Market Report Scope & Overview:
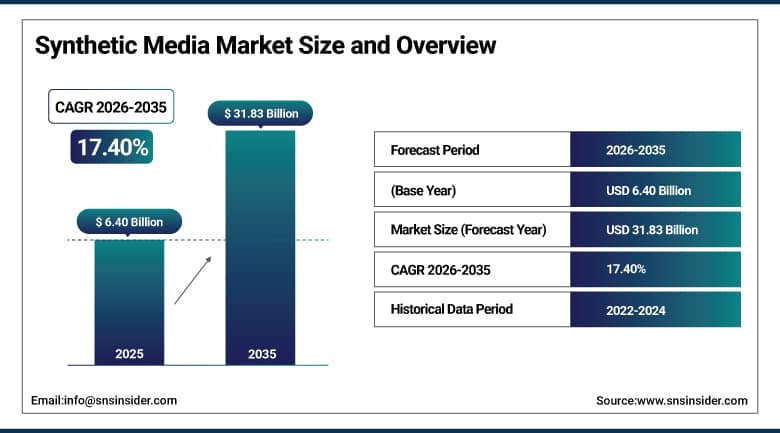
The Synthetic Media Market was valued at USD 6.40 Billion in 2025 and is expected to reach USD 31.83 Billion by 2035, growing at a CAGR of 17.40% from 2026-2035.
The Synthetic Media Market is expanding rapidly as artificial intelligence generates images, video, voice, text and virtual avatars that were once produced only through cameras, studios and human performers. Growth is supported by falling content production costs, demand for personalized and multilingual marketing, enterprise training and communication videos, game and film production pipelines, and conversational voice agents. Enterprises value the speed and scale of synthetic production, while platforms add watermarking, consent controls and content provenance features to address misuse and trust concerns. North America leads in revenue, and Asia Pacific is advancing quickly as technology investment and mobile content consumption rise across China, India and South Korea.
⮞In October 2026, ElevenLabs reported to have reached a USD 22 billion valuation through a USD 300 million employee tender offer led by Wellington and T. Rowe Price, double the valuation set at its February Series D. The company said weekly conversations handled by its ElevenAgents platform had more than tripled since February to over 15 million, with enterprise customers contributing 55% of revenue and financial services emerging as a key sector, which shows that synthetic voice is moving from creative tooling into customer-facing operations.
To Get More Information On Synthetic Media Market - Request Free Sample Report
Synthetic Media Market Trends
-
Shift from experimental creative tools to enterprise video, voice and avatar platforms
-
Growth of text-to-video models and world models that generate dynamic scenes
-
Adoption of synthetic voice agents in customer service and financial services
-
Rising use of synthetic data and virtual environments to train robotics and autonomous systems
-
Introduction of watermarking, provenance standards and consent frameworks for generated content
-
Large private funding rounds and valuations for leading generative media developers
U.S. Synthetic Media Market Outlook
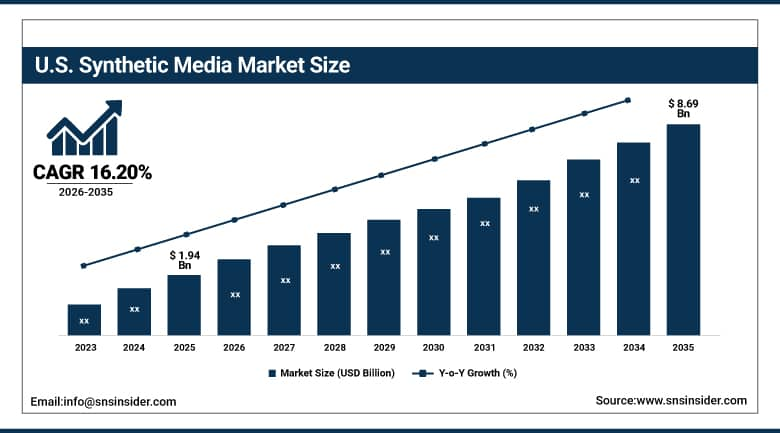
The U.S. Synthetic Media Market was valued at USD 1.94 Billion in 2025 and is expected to reach USD 8.69 Billion by 2035, growing at a CAGR of 16.20% from 2026-2035.
The U.S. Synthetic Media Market is the largest national market in North America, supported by the concentration of generative AI developers, cloud providers, studios, advertising agencies and technology investors. Enterprises use synthetic video for training, marketing and internal communications, while media companies and game developers apply generative tools to visual effects, localization and asset creation. Voice cloning, avatars and image generation are being embedded in creative software and consumer apps, and brands seek personalized content at scale. State laws on deepfakes and election content, copyright litigation and industry agreements on likeness shape adoption, and compute availability remains a competitive advantage.
⮞In February 2026, Runway announced a USD 315 million Series E led by General Atlantic at a USD 5.3 billion valuation, nearly double its prior valuation, with participation from Nvidia, Fidelity, AllianceBernstein, Adobe Ventures and AMD Ventures. The New York-based company said the funds would support pre-training of the next generation of world models for new products and industries, and it reported growing adoption in gaming and robotics, which indicates that synthetic media vendors are extending from content creation into simulation.
Synthetic Media Market Segment Analysis
-
By Component, the Solutions segment dominated the Synthetic Media Market with approximately 65.90% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 18.60%.
-
By Technology, the Generative AI segment dominated the Synthetic Media Market with approximately 45.30% share in 2025, while the Speech Synthesis segment is the fastest growing with a CAGR of approximately 19.20%.
-
By Media Type, the Image segment dominated the Synthetic Media Market with approximately 41.20% share in 2025, while the Video segment is the fastest growing with a CAGR of approximately 20.30%.
-
By Deployment Mode, the Cloud segment dominated the Synthetic Media Market with approximately 72.40% share in 2025, and is also the fastest growing with a CAGR of approximately 18.10%.
-
By Application, the Media and Entertainment segment dominated the Synthetic Media Market with approximately 29.35% share in 2025, while the Gaming segment is the fastest growing with a CAGR of approximately 20.10%.
By Component, Solutions Dominates the Synthetic Media Market and Services Grows Fastest
Solutions lead because software platforms, application programming interfaces and creative tools are the primary way enterprises and creators access generative models. Subscription products for video, voice, image and avatar generation offer predictable revenue and rapid onboarding, and developers continue to improve output quality, language coverage and editing control. Integration with existing creative suites, marketing platforms and learning systems embeds these solutions in daily workflows, which supports a large and growing base of paying users.
Services are growing fastest as organizations seek help with custom avatars, brand voice models, localization, compliance review and workflow integration. Enterprise buyers often lack the in-house skill to fine-tune models, manage consent and rights, or measure return on synthetic production, so vendors and agencies provide consulting, managed production and training. Rising concern about misuse also drives demand for detection, watermarking and governance services, and large customers increasingly bundle these offerings into multi-year agreements.
⮞In May 2025, AI dubbing provider Dubformer and media localization technology company OOONA announced a strategic partnership to explore integrating their platforms, streamlining localization workflows while addressing data security, intellectual property protection, and responsible AI use.
By Technology, Generative AI Dominates the Synthetic Media Market and Speech Synthesis Grows Fastest
Generative AI is the leading technology because diffusion, transformer and multimodal models underpin most image, video, text and avatar products. Rapid improvement in realism, controllability and speed has made these models usable for commercial campaigns, film pre-visualization, game assets and enterprise communication. Investment from technology companies and venture funds sustains frequent model releases, and platforms integrate multiple models so users can move between creation, editing and distribution without leaving a single environment.
Speech synthesis is advancing fastest as voice models become natural enough for audiobooks, dubbing, customer support and conversational agents. Low latency and emotional range allow real-time interaction, and multilingual voice cloning opens content to global audiences without re-recording. Enterprises in financial services, insurance and telecommunications are deploying voice agents at scale, and creators use synthetic narration for video and podcasts, which expands the addressable base beyond entertainment into operational use.
⮞In April 2025, Amazon introduced Nova Sonic, a speech-to-speech foundation model available through Amazon Bedrock, combining speech understanding and speech generation to support natural, real-time voice applications, including automated customer service and conversational AI agents.
By Media Type, Image Dominates the Synthetic Media Market and Video Grows Fastest
Image generation leads because it was the first modality to reach commercial quality and requires comparatively little compute. Marketing teams, designers, e-commerce sellers and social media creators use generated images for campaigns, product visuals, concept art and editing. Smartphone applications from large software companies have brought image generation to mass audiences, and integration into design tools ensures daily use, while licensing frameworks and indemnification offers address concerns about training data and ownership.
Video is the fastest-growing media type as text-to-video and image-to-video models improve motion consistency, duration and resolution. Advertisers use short generated clips for social platforms, studios adopt them for previsualization and effects, and enterprises produce training and product videos with avatars in dozens of languages. Chinese and American developers are releasing tools that turn still images into short clips, and rising compute capacity is reducing generation time, which supports adoption by small businesses and independent creators.
⮞In October 2025, Google introduced Veo 3.1 and Veo 3.1 Fast through its Gemini API in paid preview, improving image-to-video generation, synchronized audio, and cinematic control for developers building advanced synthetic video creation applications.
By Deployment Mode, Cloud Dominates the Synthetic Media Market and Also Grows Fastest
Cloud deployment dominates because generative models require large graphics processing capacity that few organizations can maintain. Providers offer model access through web applications and interfaces billed by usage, allowing customers to scale production during campaigns and avoid capital expenditure. Updates to models reach all users immediately, and cloud platforms provide storage, collaboration and rights management in one environment, which suits distributed creative teams and agencies working across regions.
The segment also advances fastest as hyperscale providers expand specialized compute and as vendors move from experimentation to production services with service level guarantees. Enterprise buyers value security certifications, regional data residency options and integration with existing identity and content systems. On-premises and private deployments remain relevant for regulated sectors and studios protecting unreleased content, but most growth is concentrated in managed cloud services that lower cost per generated minute and simplify governance.
⮞In August 2025, Google Cloud made Gemini 2.5 Flash Image available through Vertex AI, enabling enterprise developers to generate and edit images, combine multiple visual references, and maintain character consistency through managed cloud-based generative AI services.
By Application, Media and Entertainment Dominates the Synthetic Media Market and Gaming Grows Fastest
Media and entertainment lead because studios, broadcasters, streaming platforms and publishers use synthetic tools for visual effects, dubbing, de-aging, trailers, news graphics and personalized content. Cost pressure and production schedules encourage adoption of generative workflows for previsualization and post-production, and unions and rights agreements are shaping how likeness and performance data can be used. Large media groups sign enterprise licenses and form partnerships with model developers to secure legal clarity and brand-safe outputs.
Gaming is growing fastest as developers use generative tools for characters, environments, dialogue, voices and non-player character behavior. Runway reports growing adoption of its models in gaming, and open and commercial tools for three-dimensional assets are shortening development cycles. Live-service titles need constant new content, and synthetic generation allows rapid iteration and localization, while player-facing features such as adaptive characters create new experiences that increase engagement and monetization.
⮞In February 2025, Microsoft Research introduced Muse, a generative World and Human Action Model developed with Xbox Game Studios' Ninja Theory to generate gameplay sequences and controller actions, supporting game ideation and experimentation with AI-generated interactive experiences.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
78.35 |
|
Asia Pacific |
China |
36.42 |
|
Europe |
United Kingdom |
29.17 |
|
Latin America |
Brazil |
46.58 |
|
Middle East & Africa |
United Arab Emirates |
31.26 |
North America Synthetic Media Market Insights
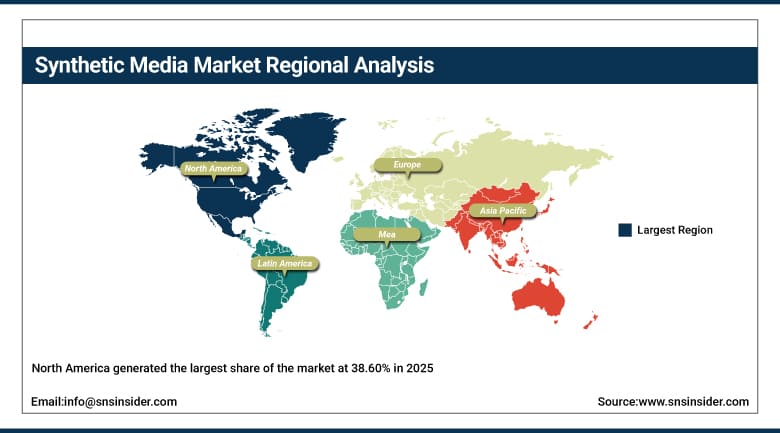
North America generated the largest share of the market at 38.60% in 2025, reflecting its concentration of leading model developers, cloud providers, studios, advertising agencies and venture capital. The United States accounts for most regional revenue, with Canada adding research strength in artificial intelligence and a growing creative technology sector. Enterprises in media, retail, financial services and technology adopt synthetic video and voice at scale, and creative software providers embed generation features into widely used applications.
Capital formation is a distinctive strength. Runway raised USD 315 million in February 2026, ElevenLabs reached a USD 22 billion valuation in October 2026, and Adobe launched an image-generation app for smartphones in June 2025. Regulation of deepfakes, election-related content and digital replicas is evolving at state and federal levels, and industry groups are developing provenance standards. Growth is strong but slower than in emerging regions because adoption is already advanced and compute costs remain high.
⮞In July 2025, Character.AI introduced TalkingMachines, an audio-driven video-generation model capable of producing real-time, interactive character videos from an image and voice input, advancing applications for virtual characters and conversational entertainment.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Synthetic Media Market Insights
Asia Pacific is the fastest-growing region, advancing at a CAGR of 19.60% during 2026-2035, supported by large mobile audiences, short-video platforms, gaming industries and active government support for artificial intelligence. China leads regional revenue, with major technology companies releasing video and image models, while India, South Korea and Japan add demand from entertainment, advertising and e-commerce. Baidu unveiled its MuseStreamer tool for converting images into short videos in July 2025, illustrating the pace of local innovation.
Brands use virtual influencers, live-stream avatars and automated product videos to reach consumers on platforms with enormous scale, and multilingual voice models help content cross language boundaries in India and Southeast Asia. Regulators in China and elsewhere require labeling of generated content, which encourages providers to build provenance features. Competitive pricing, abundant engineering talent and rapid consumer adoption suggest that the region will gain share of global revenue through 2035.
⮞In August 2025, Alibaba introduced Wan2.2-S2V, an open-source speech-to-video model that animates portrait photographs using audio inputs, generating digital humans capable of speaking and singing for synthetic video production and avatar-based content creation.
Europe Synthetic Media Market Insights
Europe is a regulation-aware market in which the United Kingdom, Germany and France lead adoption, and in which the European Union's artificial intelligence rules set transparency requirements for synthetic content. London has become a hub for enterprise video generation, with Synthesia raising a USD 180 million Series D in January 2025 and expanding across North America, Europe, Japan and Australia. Media groups, advertisers and learning providers use avatars and voice generation for multilingual communication across the region's many languages.
Privacy law, copyright concerns and requirements to disclose generated content shape product design, and vendors emphasize consent management, data governance and brand-safe outputs. Public broadcasters and publishers are experimenting with synthetic dubbing and personalized news formats, while game studios in the Nordics, France and the United Kingdom adopt generative tools for assets. Growth is healthy but constrained by compliance costs and a smaller venture funding pool than in North America.
⮞In April 2026, News UK launched Times ExplorAItion with synthetic-audience specialist Electric Twin, enabling advertisers to test campaign concepts, messaging, and creative strategies against AI-generated audience models before committing real-world advertising budgets.
MEA & Latin America Synthetic Media Market Insights
Latin America is a developing market in which Brazil and Mexico lead adoption through advertising, social media and entertainment. Spanish and Portuguese voice models support dubbing and localization for streaming platforms, and brands use synthetic influencers and personalized campaigns to engage young, mobile-first audiences. Fintech and e-commerce companies are testing voice agents and automated video, although limited local compute, currency volatility and uneven regulation temper investment and keep many buyers dependent on global platforms.
The Middle East and Africa is a smaller but ambitious market, with the United Arab Emirates and Saudi Arabia funding national artificial intelligence strategies, data centers and creative industry initiatives. Arabic language models and voice tools are expanding, and governments use synthetic media for public communication and education. Africa's growth is driven by mobile content and language localization for diverse populations, while infrastructure gaps and limited venture capital moderate speed, though partnerships with global providers open access to advanced tools.
⮞In September 2026, Dubai Press Club released its “Arab Media in the Age of AI” report at the Arab Media Summit, documenting regional adoption of AI-generated content and identifying synthetic media as an expanding application within the UAE's media industry.
Growth Drivers: Content Cost Reduction, Personalization and Enterprise Adoption
Falling production cost and faster turnaround are the primary drivers of adoption. Synthetic tools generate images, videos and voices in minutes without cameras, studios or actors, allowing small businesses to produce professional content and large enterprises to scale marketing across channels and languages. Synthesia reports more than 60,000 customers for its avatar video platform, and training, onboarding and product videos are among the first workloads to move from traditional production to generation because they require frequent updates.
Personalization and enterprise adoption add momentum. Brands want tailored messages for audiences segmented by language, region and behavior, and synthetic media makes variant production economical. Voice agents handle customer conversations at scale, with ElevenLabs reporting more than 15 million weekly conversations on its agent platform in October 2026, and financial institutions are deploying them for service and collections. Investment from technology firms and venture funds continuous model improvement, which widens the range of commercial use cases each year.
⮞In January 2026, Dentsu launched Generative Audiences, an AI-powered audience intelligence and activation solution, with the United Kingdom as its first deployment market, enabling advertisers to create AI-generated audience personas calibrated against real-world data for more targeted media planning.
Restraints: Misuse and Deepfake Risk, Copyright Uncertainty and Compute Cost
Misuse and deepfake risk is the most significant restraint because realistic synthetic content can be used for fraud, impersonation, harassment and disinformation. Governments are introducing disclosure and labeling rules, and platforms are adding detection and watermarking, but the cost of compliance and the risk of reputational damage make some enterprises cautious. Consent for voice and likeness is a central issue, and high-profile incidents can trigger regulation that limits specific uses or increases liability for vendors and customers.
Uncertainty over copyright and compute costs add yet another layer of challenge. Issues concerning lawsuits over the training datasets and questions about the copyright of generated content pose legal challenges, making companies reluctant to allow use of their platform without an indemnity clause. Video and world models take up significant graphics processing power for training and providing services, hence, putting pressure on margins due to high costs and supply limitations. Smaller players have a tough time competing with the more well-endowed companies, and customers tend to be wary of unstable pricing and model quality.
Opportunities: World Models, Voice Agents and Synthetic Data
World models and interactive video offer significant opportunity as developers extend generation from clips to simulated environments. Runway is pre-training next-generation world models for gaming and robotics, and NVIDIA introduced Physical AI Data Tools and Cosmos World Foundation Models in March 2025 to generate synthetic environments for training robots and autonomous systems. These applications create demand beyond media, linking synthetic content to industrial simulation, digital twins and autonomous vehicle testing, where realistic data is expensive to collect.
Voice agents and synthetic data provide further opportunities. Organizations in the banking, insurance, health care, and retail industries are automating components of their call centers by adopting conversation-based voice technology that rapidly solves problems, and multilingual technology gives access to new markets. Synthetic data created for training computer vision and voice technologies helps enterprises train their system without divulging any personal data. Providers of auditable and industry-specific solutions with provenance and consent capabilities stand a chance of getting a long-term enterprise contract.
⮞In September 2025, Luma AI launched Ray3, a reasoning-based video generation model supporting high-dynamic-range EXR output and faster draft generation, with Dentsu Digital adopting the technology for video advertising production in Japan and additional agency partners targeting professional creative workflows.
Recent Developments:
-
2025: Synthesia raised a USD 180 million Series D led by NEA at a valuation of USD 2.1 billion. The funding supports product development, hiring and expansion in North America, Europe, Japan and Australia, and the company reported more than 60,000 customers for its enterprise video platform.
-
2025: Baidu unveiled MuseStreamer, a generative AI tool that converts images into short videos. The release extends the company's multimodal portfolio and reflects growing competition among Chinese technology firms in video generation.
-
2025: Adobe launched an AI image-generation app for smartphones. The app brings generative creation to mobile users and strengthens the company's position in consumer-facing creative tools.
-
2025: NVIDIA introduced Physical AI Data Tools and Cosmos World Foundation Models for generating synthetic environments to train robotics and autonomous systems. The offering links synthetic media techniques to industrial simulation and reduces the cost of collecting real-world training data.
Synthetic Media Market Key Players are:
-
Adobe Inc.
-
NVIDIA Corporation
-
Alphabet Inc. (Google)
-
IBM Corporation
-
Baidu, Inc.
-
OpenAI
-
Runway AI, Inc.
-
Synthesia Ltd.
-
ElevenLabs
-
DeepBrain AI
-
HeyGen
-
D-ID
-
Descript, Inc.
-
Veritone, Inc.
-
Soul Machines
-
Resemble AI
-
Colossyan
-
Midjourney, Inc.
Synthetic Media Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.40 Billion |
| Market Size by 2035 | USD 31.83 Billion |
| CAGR | CAGR of 17.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions, Services) • By Technology (Generative AI, Speech Synthesis, Computer Vision, Natural Language Processing, Others) • By Media Type (Image, Video, Audio and Voice, Text, Virtual Avatars) • By Deployment Mode (Cloud, On-Premises) • By Application (Media and Entertainment, Advertising and Marketing, Gaming, Education and E-Learning, Healthcare, Retail and E-Commerce, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Google LLC, Microsoft Corporation, Amazon Web Services, Inc., International Business Machines Corporation, Oracle Corporation, SAP SE, Snowflake Inc., Databricks, Inc., Teradata Corporation, Informatica Inc., TIBCO Software Inc., Qlik Technologies Inc., SAS Institute Inc., Cloudera, Inc., Domo, Inc., Alteryx, Inc., ThoughtSpot, Inc., Fivetran Inc., Matillion Limited, Hitachi Vantara LLC |

Frequently Asked Questions
Key players include Adobe, NVIDIA, Microsoft, Google, IBM, and Midjourney, among others.
Key opportunities include world models and interactive video for gaming and robotics, enterprise voice agents, synthetic training data, and multilingual content localization for global audiences supported by provenance and consent features.
The major growth factor is the sharp reduction in the cost and time of producing images, video and voice, combined with demand for personalized content and enterprise adoption of generative AI platforms.
By Technology, the Generative AI segment dominated the market with approximately 45.30% share in 2025, owing to the use of diffusion and transformer models across image, video, text and avatar products.
North America dominated the market with a share of 38.60% in 2025, supported by leading model developers, cloud providers, studios and venture capital in the United States.
